

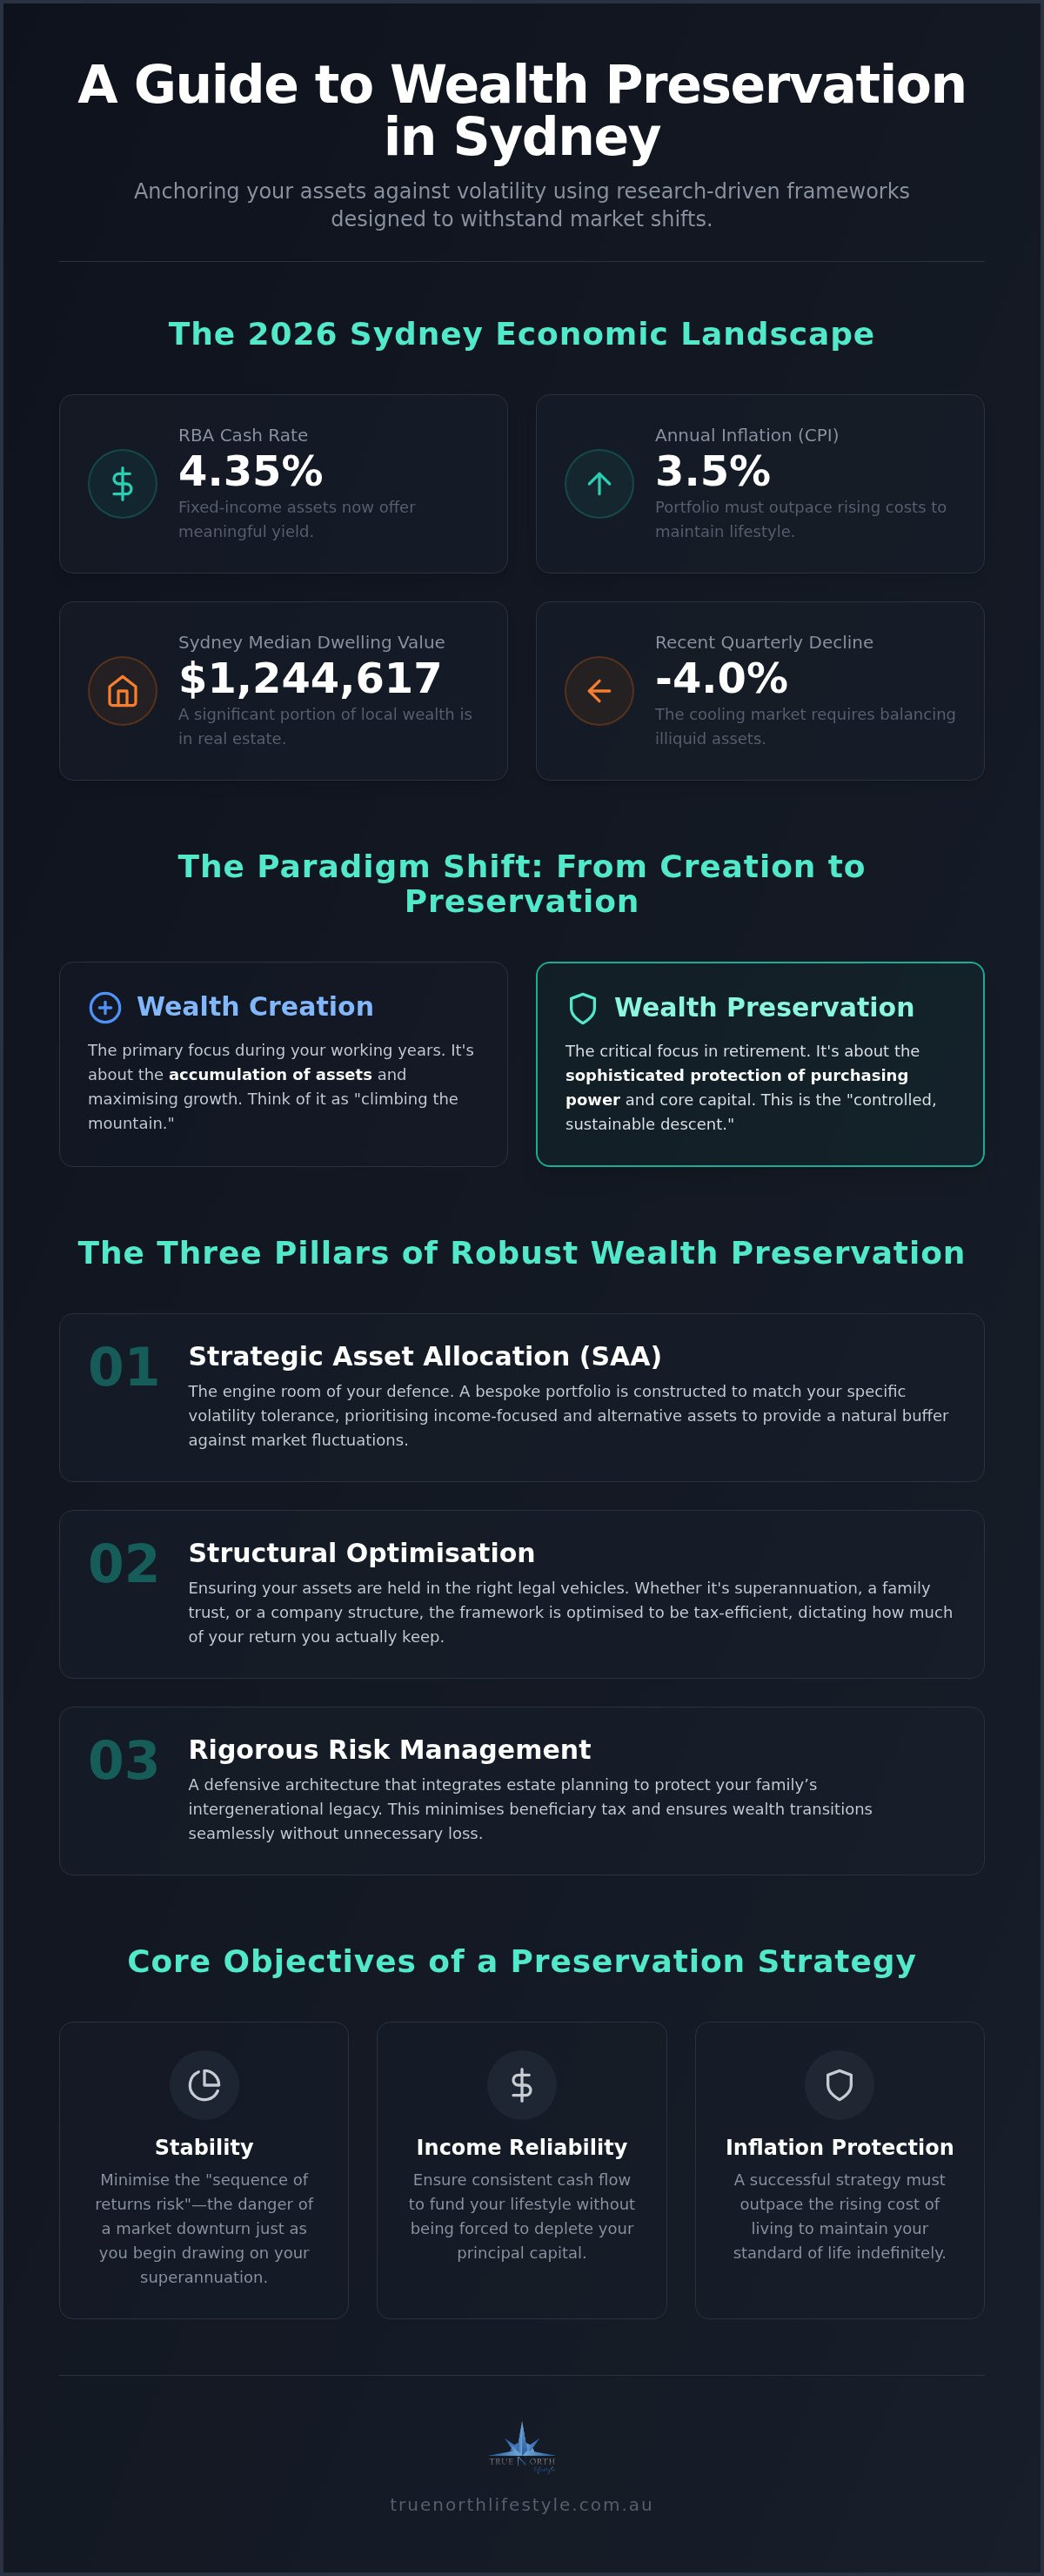
What if the greatest risk to your retirement isn't a sudden market crash, but the quiet, compounding erosion of your capital by inflation and legislative shifts you didn't see coming? For many local families, identifying the right wealth preservation investment strategies Sydney offers is no longer just about growth; it's about defence. You've worked hard to build a significant portfolio, yet the current environment feels increasingly unpredictable. With the RBA holding the cash rate at 4.35 per cent and inflation still sitting at 3.5 per cent, the ground beneath your feet can feel less than solid.
We understand that complexity often breeds anxiety, especially when your family's legacy is on the line. This guide will show you how to anchor your assets using research-driven frameworks designed to withstand volatility and minimise tax liabilities. You'll discover a structured path toward a stable, low-volatility income stream that protects your lifestyle. We'll explore bespoke portfolio construction, the impact of the 12 per cent Superannuation Guarantee, and strategies to ensure your wealth transitions seamlessly to the next generation without unnecessary loss.
Key Takeaways
- Learn to distinguish between wealth creation and preservation to maintain your lifestyle and purchasing power in a shifting 2026 economic environment.
- Discover how bespoke wealth preservation investment strategies Sydney utilise Strategic Asset Allocation to build a low-volatility shield around your core capital.
- Optimise your superannuation structure to leverage low-tax environments, ensuring your retirement savings are protected from unnecessary tax erosion.
- Protect your family’s intergenerational legacy by integrating estate planning with robust risk management frameworks to minimise beneficiary tax.
- Use advanced retirement modelling to transform complex financial data into a clear, actionable plan that provides genuine emotional reassurance.
Understanding Wealth Preservation in the 2026 Sydney Market
Wealth preservation is a defensive architectural task. It moves beyond the simple gathering of assets to the sophisticated protection of purchasing power and core capital. While wealth creation focuses on the accumulation phase, preservation centres on the maintenance and decumulation phase. For many families in Sydney, this shift is often accompanied by a sense of unease. You've spent decades climbing the mountain; now you must ensure the descent is controlled, sustainable, and protected. Understanding Wealth Preservation requires a deliberate focus on longevity and the mitigation of risks that didn't matter as much during your working years.
Our city presents a unique set of challenges. With a median dwelling value of $1,244,617 as of July 2026, a significant portion of local wealth is often tied to the family home. However, the market has recently cooled, recording a quarterly decline of -4.0 per cent. This environment demands wealth preservation investment strategies Sydney families can trust to balance their illiquid real estate holdings with liquid, income-generating assets. At True North Lifestyle, we act as your Steady Navigator. We replace financial anxiety with a structured order, ensuring your capital isn't just sitting idle, but is actively defended against erosion.
The Core Objectives of a Preservation Strategy
Stability is paramount. We aim to minimise "sequence of returns risk," which is the danger of a market downturn occurring just as you begin drawing on your superannuation. This can permanently impair your portfolio's longevity. Secondly, we prioritise income reliability. You need consistent cash flow to fund your lifestyle without depleting your principal. Finally, we address inflation protection. With the annual CPI at 3.5 per cent, your portfolio must outpace the rising cost of living in Sydney to maintain your standard of life. A preservation strategy is successful only if it maintains your standard of living indefinitely.
Why 2026 Requires a Different Approach
The landscape has changed. With the RBA cash rate at 4.35 per cent, fixed-income assets finally offer a meaningful yield, but they also bring new volatility. Speculative trends are no longer sufficient. Modern wealth preservation investment strategies Sydney require a research-driven methodology that prioritises "defensive architecture." This means constructing portfolios that can withstand global geopolitical shifts and local regulatory changes, such as the legislated 12 per cent Superannuation Guarantee rate. We value proven outcomes over flashy innovation, providing a reliable anchor in a fluctuating environment. It's about replacing guesswork with technical depth and logical grounding.
The Three Pillars of Robust Wealth Preservation
Foundations ensure durability. Effective wealth preservation investment strategies Sydney families employ aren't just about picking stocks; they're about defensive architecture. We view this through three integrated pillars: Strategic Asset Allocation (SAA), structural optimisation, and rigorous risk management. Managing these in isolation creates cracks. A high-growth portfolio is useless if held in a tax-inefficient structure, just as a tax-effective trust is wasted on a portfolio that can't weather a market dip. These elements must be synchronised to protect your lifestyle.
SAA is the engine room, specifically tailored to your tolerance for volatility. However, it must sit within the right legal vehicle. Whether it's superannuation, a family trust, or a company structure, the legal framework dictates how much of your return you actually keep. As you develop an investment plan, our focus remains on ensuring these components work in unison to protect your core capital. It's a methodical process that moves the reader from uncertainty toward a well-defined path.
Low-Volatility Portfolio Construction
Quiet certainty. Our in-house Investment Committee provides direct oversight, moving away from speculative trends toward evidence-based stability. We focus on bespoke portfolio construction that prioritises income-focused assets. These instruments provide a natural buffer, reducing the sharp fluctuations often found in growth-heavy portfolios. While shares and property remain relevant, true diversification in 2026 requires looking further. We integrate alternative assets that don't always move in lockstep with the ASX, providing an extra layer of defence. You can explore how bespoke portfolio construction can stabilise your financial future.
Portfolio Sustainability Modelling
Numbers provide clarity. We use advanced retirement modelling to stress-test your wealth against historical shocks, like the 2008 GFC or the 2020 pandemic. This isn't just about "best-case" projections. It's about understanding how your capital behaves when the world feels uncertain. By simulating various market scenarios, we can predict capital longevity with a high degree of confidence. True sustainability is found where your lifestyle goals meet evidence-based probability. This rigorous process replaces the anxiety of the unknown with a structured, documented path. It allows you to step into a role of confident oversight, knowing the heavy lifting and testing are already complete.
Superannuation: The Engine Room of Australian Wealth Protection
Structure provides safety. Within the landscape of wealth preservation investment strategies Sydney, superannuation remains the most powerful low-tax sanctuary for your capital. For the 2026-27 financial year, the Superannuation Guarantee rate has risen to 12 per cent, further cementing its role as the primary vehicle for long-term maintenance. By utilising the concessional contribution cap of $32,500, you can effectively reduce your personal tax liability while building a robust defence for your future. The goal is to move from the accumulation phase to a tax-free pension phase where earnings are no longer eroded by the ATO.
Transitioning requires precision. Longevity planning is not merely about reaching retirement; it's about ensuring your capital outlives your requirements in a high-cost city like Sydney. A comprehensive superannuation review is the first step in ensuring your fund remains aligned with your long-term preservation goals. We focus on the "decumulation" phase, where the priority shifts from aggressive growth to sustainable, low-volatility income. This methodical shift replaces the anxiety of a fluctuating balance with the quiet certainty of a structured cash flow.
The Re-contribution Strategy Explained
Protect your beneficiaries. While Australia does not have a formal inheritance tax, the "death benefits tax" can still claim a significant portion of your super if paid to non-dependents, such as adult children. The re-contribution strategy is a vital wealth preservation tool that involves withdrawing a portion of your "taxable" component and contributing it back as a "tax-free" non-concessional contribution, within the $130,000 annual cap. This process effectively washes the tax out of the fund. It ensures that more of your legacy stays with your family rather than being diverted to the government. For Sydney couples with significant balances, this single tactical move can save their estate tens of thousands of dollars.
SMSF vs. Industry Funds for Preservation
Control versus convenience. A Self-Managed Super Fund (SMSF) offers the highest level of strategic flexibility, allowing for bespoke asset protection and the inclusion of unique assets like business real property. This level of oversight is ideal for those who want to be the "Steady Navigator" of their own ship. However, with control comes an administrative burden, including strict audit and compliance requirements. For others, a high-quality industry or retail fund may provide the necessary low-volatility options without the hands-on management. The choice depends on the complexity of your estate and your desire for direct involvement. We help you weigh the strategic flexibility of an SMSF against the streamlined nature of managed funds to find the right fit for your preservation journey.
Estate Planning and the Intergenerational Legacy
Preservation is a lifecycle. It doesn't end when you stop working, nor does it conclude with your own longevity. In a city like Sydney, where property values and investment portfolios have reached historic highs, we are witnessing the "Great Wealth Shift." This period marks a massive transfer of capital between generations, yet many families remain unprepared. A common misconception is that estate planning is reserved for the ultra-wealthy. If you own a family home and a superannuation balance in today's market, you have a significant legacy that requires protection. Robust wealth preservation investment strategies Sydney families employ must include a clear strategy for how that wealth enters the hands of the next generation.
Clarity protects harmony. Beyond the technicalities of tax, the primary goal of wealth transfer strategies is to ensure your family remains united. By removing ambiguity and providing a structured roadmap, you replace potential conflict with a sense of order. This is where the role of a Steady Navigator becomes most valuable, moving your family from the anxiety of the unknown toward a well-defined and documented path.
The Power of Testamentary Trusts
Defend your lineage. A standard Will often falls short because it distributes assets directly to beneficiaries, leaving that capital vulnerable to external risks like a child's potential divorce or bankruptcy. In contrast, a Testamentary Trust acts as a protective wrapper. It offers a superior layer of defensive architecture, allowing for the tax-effective distribution of income to minor grandchildren. Under current laws, these minors can be taxed at adult rates on trust income, providing a significant tax advantage compared to standard discretionary trusts. This ensures your capital remains productive and stays within the family line.
Minimising "Death Taxes" in Australia
The ATO is a silent partner. While it's true that Australia has no formal inheritance or gift tax, the transfer of wealth is rarely tax-free. Capital Gains Tax (CGT) can be a significant burden when non-cash assets, such as investment properties or shares, are eventually sold by your heirs. We focus on identifying "tax-heavy" assets within your portfolio and implementing strategies to clean them up before they pass on. This might involve re-balancing your portfolio or using the re-contribution strategies discussed earlier to wash the tax out of your superannuation. To ensure your legacy is protected from unnecessary erosion, you can explore our bespoke estate planning strategy services.
Achieving Clarity: The True North Lifestyle Approach
Clarity replaces chaos. Our Steady Navigator process is designed to strip away the complexity of wealth preservation investment strategies Sydney residents face, replacing it with a logical, step-by-step roadmap. We believe that a strategy is only as strong as the understanding behind it. It's not enough to have a portfolio that works; you must understand why it works and how it protects your specific lifestyle. This methodical progression moves you from a state of uncertainty toward a role of confident oversight.
Our structured process follows four distinct phases of strategic construction:
- Step 1: Discovery. We conduct a deep-dive into your personal values, family dynamics, and the specific lifestyle requirements you wish to maintain.
- Step 2: Technical Modelling. Our team performs rigorous stress-testing of your current assets, using retirement modelling to project longevity against various market scenarios.
- Step 3: Implementation. We execute a bespoke investment strategy that synchronises your portfolio with tax-minimisation and superannuation structures.
- Step 4: Ongoing Oversight. Your plan is never static. Our Investment Committee provides proactive adjustments to navigate RBA rate cycles and legislative changes.
Retirement Modelling in the Sutherland Shire
Local context matters. For residents in Miranda and across the Sutherland Shire, wealth preservation is often about the "human outcome" rather than just the spreadsheet. You've built a life in one of the most beautiful parts of the world, and you want to ensure your capital supports that reality indefinitely. Our modelling provides what we call "Permission to Spend." It is the technical reassurance that you can enjoy your retirement and fund your lifestyle without the persistent fear of running out of capital. Having a local Miranda-based advisor allows for face-to-face strategic reviews where we can discuss these projections in detail, ensuring your plan remains anchored in your real-world needs.
Your Next Steps Toward Financial Calm
Stability is a choice. Seeking independent financial advice is the most effective way to ensure your strategies are unbiased and focused solely on your best interests. To prepare for an initial consultation, we suggest gathering your latest superannuation statements, a summary of your current investment holdings, and a clear list of your annual lifestyle expenses. Bringing these details allows us to begin the modelling process with precision from day one. If you are ready to replace anxiety with a structured path, you can organise a strategy session with our Sydney advisors to begin your journey toward lasting financial calm.
Securing Your Financial Future in a Shifting World
Your retirement should be a period of quiet certainty. True wealth preservation requires more than just picking assets; it demands a synchronised approach where technical modelling meets personal values. By integrating strategic asset allocation with robust structural optimisation, you protect your capital from the quiet erosion of tax and inflation. We've explored how synchronising your superannuation reviews with intergenerational estate planning ensures your legacy remains intact for the years ahead.
At True North Lifestyle, we act as your Steady Navigator. Our in-house Investment Committee provides rigorous oversight, while our specialists in Sydney retirement modelling offer the technical clarity you need to move forward. Through our collaborative approach with Resonant Asset Management, we deliver wealth preservation investment strategies Sydney families can rely on for long-term stability. It's about replacing the anxiety of the unknown with a structured, documented path toward longevity.
You deserve to feel empowered in your financial journey. Secure your legacy with a bespoke wealth preservation strategy today and step into a future defined by clarity and confidence.
Frequently Asked Questions
What is the difference between wealth growth and wealth preservation?
Wealth growth focuses on the accumulation of assets through aggressive appreciation, while wealth preservation prioritises the protection of existing capital and its purchasing power. During the preservation phase, the objective shifts toward generating a stable income stream and mitigating sequence of returns risk. It is a defensive architectural task. Effective wealth preservation investment strategies Sydney residents utilise ensure that their lifestyle is maintained without significantly depleting the core principal, even during market fluctuations.
How much do I need to retire comfortably in Sydney in 2026?
A comfortable retirement in Sydney generally requires a higher capital base than other Australian cities due to a median house price exceeding $1.5 million. While industry standards suggest couples need approximately $72,000 annually, Sydney retirees often require more to sustain their lifestyle. We use bespoke retirement modelling to determine your specific "Permission to Spend" figure. This technical process accounts for local costs, your specific longevity projections, and the 3.5 per cent inflation rate recorded in July 2026.
Is a re-contribution strategy legal and how does it work?
Yes, the re-contribution strategy is a legitimate and widely utilised tool within Australian superannuation law. It involves withdrawing a portion of your superannuation and contributing it back as a non-concessional contribution, within the $130,000 annual cap for the 2026-27 financial year. This process effectively converts "taxable" components into "tax-free" components. It is particularly valuable for minimising the death benefits tax that non-dependent beneficiaries, such as adult children, might otherwise face upon your passing.
Do I need a testamentary trust if I already have a will?
A standard Will provides for the direct distribution of assets, whereas a testamentary trust offers a layer of defensive architecture for your legacy. These trusts are established within a Will and only come into effect upon death. They provide significant asset protection against a beneficiary’s potential divorce or bankruptcy. Additionally, they allow for the tax-effective distribution of income to minor grandchildren, who are taxed at adult rates, ensuring your family’s wealth is preserved across generations.
How does inflation affect wealth preservation strategies in Australia?
Inflation acts as a quiet erosion of your capital’s real-world value. With the annual CPI inflation rate at 3.5 per cent as of mid-2026, a static portfolio effectively loses value every year. Successful wealth preservation investment strategies Sydney families implement must focus on assets that provide a "real" return above inflation. This ensures your income stream maintains its purchasing power, allowing you to meet the rising costs of local goods, services, and council rates without compromising your lifestyle.
What are the risks of managing my own wealth preservation strategy?
Managing your own strategy often leads to emotional decision-making during market volatility, which can be catastrophic during the decumulation phase. DIY investors frequently overlook complex tax-minimisation opportunities or fail to account for "sequence of returns risk." This is the danger of a market downturn occurring early in retirement. Without professional stress-testing and retirement modelling, it is difficult to maintain the disciplined, research-driven methodology required to ensure your capital lasts as long as you do.
How often should a wealth preservation portfolio be reviewed?
We recommend a comprehensive strategic review at least once every twelve months. However, significant life events or legislative shifts, such as changes to the Superannuation Guarantee or tax brackets, may necessitate more frequent oversight. Regular reviews allow our Investment Committee to make proactive adjustments to your portfolio’s defensive architecture. This methodical approach ensures your strategy remains anchored to your personal values while responding to the RBA’s current cash rate of 4.35 per cent.
Can I use my superannuation for wealth preservation before I retire?
You can certainly utilise superannuation for wealth preservation before full retirement through a Transition to Retirement (TTR) pension. Once you reach your preservation age, a TTR allows you to access a portion of your super while you are still working. This can be synchronised with salary sacrifice strategies to reduce your taxable income. It is a sophisticated way to begin the structural optimisation of your wealth, ensuring you are building a tax-effective foundation well before you stop working.


