

An SMSF can still buy property, but the property itself shouldn’t be the first decision. If you’re weighing the SMSF property investment rules Sutherland Shire investors need to understand, consider the rules on borrowing, related parties and your fund’s purpose alongside the property’s location and expected return.
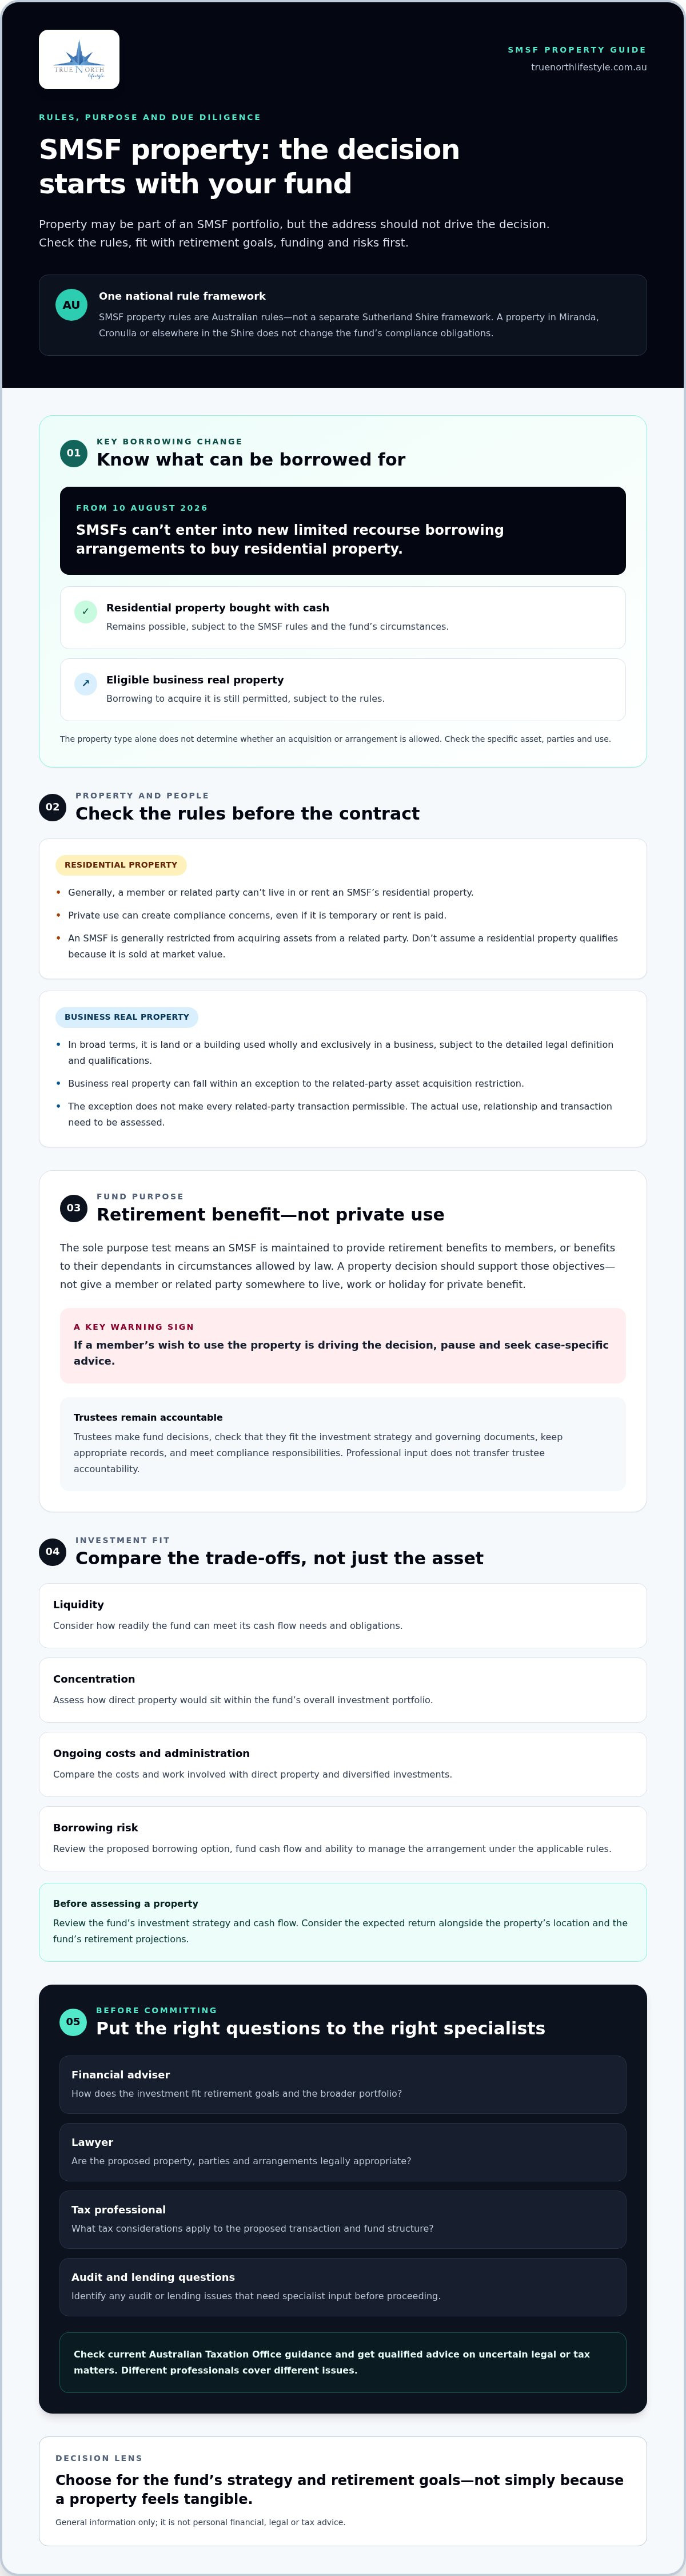
It’s understandable to see property as a tangible way to build retirement wealth and still feel unsure about what your SMSF can and can’t do. Since 10 August 2026, SMSFs can’t enter into new limited recourse borrowing arrangements to buy residential property, although buying residential property with cash remains possible. Borrowing to acquire eligible business real property is still permitted, subject to the rules.
This 2026 guide explains the key rules and exceptions, including restrictions on personal use and related-party transactions. It compares SMSF property with other investment approaches and outlines the liquidity, concentration and borrowing risks to consider. You’ll also find practical questions to discuss with qualified financial, legal and tax advisers, so you can assess whether property fits your fund’s strategy and retirement projections without treating general information as personal advice.
Key Takeaways
- The SMSF property investment rules Sutherland Shire trustees need to consider are Australian rules, not a separate local framework.
- Check how residential and business property are treated, especially before a member or related party is involved in the property’s use or ownership.
- Compare direct property with diversified investments by looking at liquidity, concentration, ongoing costs and administration.
- Review your fund’s investment strategy and cash flow before assessing a property or borrowing option.
- Identify which financial, tax, legal, audit and lending questions need specialist input before you commit.
SMSF property investment rules in the Sutherland Shire: what trustees need to know
An SMSF property investment is property held by a self-managed super fund as part of its investment portfolio, rather than a home or asset held for a member’s personal use. The fund’s trustee makes decisions on the fund’s behalf. The property must be treated as a fund asset, not as an extension of a member’s private finances.
The Superannuation in Australia system provides useful background, but an SMSF has specific obligations trustees need to understand. The SMSF property investment rules Sutherland Shire trustees must consider are Australian rules. Owning property in Miranda, Cronulla or elsewhere in the Shire doesn’t create a separate local rule set. The location may affect the investment case, but not the fund’s compliance obligations.
What does the sole purpose test mean for SMSF property?
In broad terms, the sole purpose test requires an SMSF to be maintained to provide retirement benefits to its members, or benefits to their dependants in the circumstances allowed by law. A property decision should therefore support the fund’s retirement objectives, not give a member or related party somewhere to live, work or holiday for private benefit.
Personal use can raise serious compliance concerns. For example, a member’s wish to stay in a residential property owned by the fund shouldn’t drive the investment decision. The rules can be detailed, and specific arrangements may need closer review. Before acting, check current Australian Taxation Office guidance and get advice on how the rules apply to the proposed property and fund structure.
Who makes decisions for an SMSF?
Trustees are responsible for making fund decisions and ensuring they’re consistent with the fund’s governing documents and obligations. In practice, this means checking whether an investment fits the fund’s strategy, keeping appropriate records and meeting compliance responsibilities. Record the reasons for a decision where appropriate, along with the information used to reach it.
Professionals can help with different parts of the process, but they don’t take over trustee accountability. A financial adviser can help assess how an investment fits retirement goals and the broader portfolio. A lawyer can advise on legal questions, while a tax professional can explain tax considerations. These roles are distinct, so don’t assume one professional’s input covers every issue.
This section is general information, not personal financial, legal or tax advice. Before committing, have the proposed investment reviewed in light of your circumstances and seek qualified advice on any uncertain legal or tax matters.
Which SMSF property rules apply to residential and business property?
Property type matters, but it doesn’t determine by itself whether a fund can acquire or use an asset. Trustees need to check who is selling it, how it will be used, whether a related party is involved and whether the purchase and ongoing arrangements comply with SMSF rules. A property can look like a suitable investment and still be structured incorrectly.
Can an SMSF buy a residential property from a related party?
As a general rule, an SMSF is restricted from acquiring assets from a related party. Business real property can fall within an exception, but that doesn’t make every related-party property transaction permissible. Don’t assume a residential property qualifies because it’s being sold at market value or the fund has a strong investment rationale. The specific relationship, asset and transaction need to be assessed against current requirements.
Residential property held by an SMSF generally can’t be lived in or rented by a fund member or related party. Private use can conflict with the fund’s purpose and create compliance concerns, even if the arrangement is temporary or rent is paid. Before signing a contract or transferring an existing asset, seek case-specific legal and tax advice and confirm the position using current Australian Taxation Office guidance.
When can an SMSF invest in business real property?
In broad terms, business real property is land or a building used wholly and exclusively in a business, subject to the detailed legal definition and any applicable qualifications. Commercial premises used in an operating business may be worth investigating, but the property’s actual use matters. A label such as “commercial” doesn’t, by itself, establish that an asset meets the test.
SMSF rules may allow a fund to lease qualifying business real property to a related party, provided the relevant conditions are met. Have qualified professionals confirm that the property meets the definition and check the lease terms, market rent, documentation and ongoing use. Rent and other dealings should be on arm’s-length, market-based terms where required. Keep evidence of how rent was assessed and review the arrangement if the tenant, use or terms change.
Permission to acquire an asset doesn’t automatically make its purchase, valuation, lease or ongoing management compliant. The fund’s investment strategy, transaction documents, property valuation and related-party arrangements all need appropriate scrutiny. The SMSF property investment rules Sutherland Shire investors face are national, so local market knowledge can inform the investment case but can’t replace compliance checks.
A financial adviser can help assess how property fits your retirement strategy and wider portfolio. Direct legal and tax questions to appropriately qualified professionals. For a broader view of your superannuation and retirement position, explore superannuation and retirement planning.
Is SMSF property better than other investments for Sutherland Shire investors?
A property can feel tangible, but ownership alone doesn’t make it suitable for an SMSF or guarantee dependable retirement income. The practical question is how it fits alongside the fund’s other assets, expected cash needs and members’ time horizons. Understanding the SMSF property investment rules Sutherland Shire trustees must follow is only part of the decision. Portfolio fit matters too.
What risks can direct property create inside an SMSF?
Direct property can concentrate a large share of a fund’s wealth in one asset, location or tenant. It’s also relatively illiquid: selling can take time, and a property can’t usually be divided to meet a smaller cash need. Rent may help meet expenses, but vacancies, repairs, insurance and other outgoings can affect cash flow. Consider how the fund would cover costs if rental income stopped or an unexpected expense arose.
Keep accessible funds available for the SMSF’s obligations and members’ circumstances, rather than assuming the property can be sold quickly if cash is needed. Include likely expenses and possible vacancy periods in the fund’s cash-flow planning. Don’t rely on forecast local price growth or rent to make the strategy work.
How does property compare with a diversified SMSF portfolio?
Different assets bring different trade-offs. A diversified portfolio may spread exposure across asset types, while direct property can make one holding a substantial part of the fund. Use the comparison below as a starting point, not a recommendation.
| Decision factor | Direct property | Other diversified assets |
|---|---|---|
| Liquidity | Sale can take time; ongoing costs continue while held. | Some assets may be easier to sell, depending on the investment and market conditions. |
| Diversification | A single property can create concentrated exposure to one asset and market. | Holdings across asset types may spread exposure, depending on portfolio construction. |
| Administration | Requires attention to property management, expenses, records and any tenancy arrangements. | Administration varies by asset and investment structure. |
| Exposure to one asset | Fund outcomes may be closely tied to that property and its income. | Exposure can be distributed across multiple investments, but diversification doesn’t remove risk. |
The appropriate mix depends on objectives, time horizon, cash-flow needs and capacity to tolerate risk. Also compare holding property inside super with owning investments outside super. The structures, tax treatment and borrowing considerations differ, so seek advice specific to your circumstances. A whole-of-fund review can put the property decision in context. See this Sutherland Shire superannuation advice guide and explore wealth preservation strategies for broader portfolio considerations.
How should Sutherland Shire trustees assess borrowing and property due diligence?
Work through the decision before committing the fund or signing a contract. Start with the SMSF’s investment strategy and retirement objectives. Then test cash flow, investigate the specific property, review any finance proposal and obtain professional input. The SMSF property investment rules Sutherland Shire trustees need to meet are national. Local property checks add another layer, but don’t replace SMSF compliance checks.
What should trustees check before considering an SMSF loan?
A limited recourse borrowing arrangement (LRBA) is a specialised SMSF borrowing structure. In broad terms, the lender’s rights in a default are limited to the asset acquired under the arrangement, subject to strict legal requirements. Borrowing isn’t automatically suitable just because it may be permitted.
As at September 2026, SMSFs can’t enter new LRBAs to purchase residential property. Existing residential LRBAs established before 10 August 2026 are grandfathered and may continue until repaid or be refinanced. Borrowing to acquire eligible business real property remains possible, but trustees should verify current requirements and the proposed structure with specialists before proceeding.
Test whether the fund could manage repayments and property costs if rent stopped, a tenant left or an unexpected repair arose. Review the loan terms and fund cash flow under less favourable conditions, not just the expected scenario. Ask qualified legal, tax and lending professionals to assess the arrangement. A lender’s approval alone doesn’t establish that it complies with SMSF rules or suits the fund.
What local property checks still matter?
Once you understand the fund-level and finance questions, investigate the property itself. Confirm title details and permitted use, review its condition and insurance needs, and check relevant planning information with the appropriate council or authority. For a Sutherland Shire property, this can include checking current information from Sutherland Shire Council about planning controls applicable to the address.
Keep the two assessments distinct. Local planning, title or building checks don’t determine whether the SMSF can acquire or borrow for the property. Likewise, an SMSF-compliant structure doesn’t confirm the property is suitable or free of local restrictions.
- Strategy: Does the proposed investment align with the fund’s documented objectives?
- Cash flow: Can the fund meet costs and obligations if income is interrupted?
- Property: Have title, permitted use, condition, insurance and planning matters been checked?
- Finance and advice: Have the borrowing structure and transaction received appropriate specialist review?
Link the decision to long-term retirement projections, not just the purchase. This retirement planning guide for Sydney offers broader context. To assess how a property decision may fit your retirement projections and superannuation strategy, explore retirement modelling and superannuation advice.
Plan an SMSF property decision around retirement goals, not the address
A property’s location may attract your attention, but the decision should stand up to a broader review. Before proceeding, check that the proposed investment is permitted, fits the fund’s strategy, leaves enough cash for obligations and doesn’t create an unsuitable level of concentration or administration. Then have the relevant professionals review the transaction. Understanding the SMSF property investment rules Sutherland Shire trustees face is one part of a decision that should serve members’ retirement objectives.
Which questions should trustees take to their advisers?
Prepare questions that test the strategy, not just the property. For example:
- How would the property affect the fund’s diversification, liquidity and projected retirement outcomes?
- Which specialists should review the purchase, any lease or borrowing arrangement, and the tax treatment?
- Could the fund manage vacancies, repairs or other costs without disrupting its plans?
- How would the investment fit if a member’s circumstances or retirement timing changed?
Different professionals have different roles. A financial adviser can help assess portfolio fit and retirement implications. An SMSF accountant can assist with fund accounting and tax matters. A lawyer can advise on legal and transaction questions, while an auditor independently examines the SMSF’s financial statements and compliance as required. A lender assesses a finance application, but lending approval isn’t confirmation that the investment meets SMSF rules or suits the fund.
How can retirement modelling clarify the decision?
Modelling can compare a property scenario with alternative portfolio assumptions and show how different cash-flow conditions may affect retirement plans. Trustees might test what happens if rental income is interrupted, costs rise or the fund needs more accessible cash. These projections help make trade-offs visible; they don’t predict returns or guarantee an outcome.
True North Lifestyle’s retirement modelling, long-term projections and superannuation advice can support a strategic assessment of how an investment may fit within wider retirement goals. These services aren’t a substitute for legal advice, tax advice, SMSF audit services or lending services. For related context, read this guide to tax planning for retirement.
Take a measured next step: discuss your superannuation and retirement strategy with a local advice team. A considered review can help clarify the questions to resolve before you act, without assuming property is the right choice for every fund.
Make your next SMSF decision with a clear plan
The SMSF property investment rules Sutherland Shire trustees need to understand are only one part of the decision. Before acting, confirm the investment is compliant, assess how it fits the fund’s strategy, and consider liquidity, diversification and ongoing responsibilities. A property’s location or appeal can’t replace that careful review.
Connect the choice to your retirement goals. Retirement modelling and long-term projections can help you compare a property scenario with other portfolio approaches. A superannuation review and bespoke investment portfolio advice can bring the wider picture into focus. These strategic services don’t replace specialist legal or tax advice where your circumstances call for it.
If you’re ready to consider your options, discuss your superannuation and retirement strategy. A considered conversation can help you clarify what to ask and which decisions need further review. Take it one step at a time, with your long-term financial wellbeing guiding the way.
Frequently Asked Questions
Can an SMSF buy a residential property in the Sutherland Shire?
Yes, an SMSF can buy residential property outright with cash if the investment complies with superannuation rules, fits the fund’s investment strategy and serves retirement purposes. However, as at September 2026, an SMSF can’t enter a new limited recourse borrowing arrangement to purchase residential property. These SMSF property investment rules Sutherland Shire trustees face apply nationally, including to a property in Miranda. Confirm current requirements before making a commitment.
Can I live in a property owned by my SMSF?
No, generally you and your related parties can’t live in a residential property owned by your SMSF, even temporarily or if you pay rent. The property must be held for the fund’s retirement purpose, not for a member’s private use. If an arrangement involves unusual circumstances, don’t assume an exception applies. Check current Australian Taxation Office guidance and get advice from appropriately qualified professionals before using or leasing any fund-owned property.
Can my SMSF buy a property from me or a related party?
Generally, an SMSF is restricted from acquiring assets from related parties, so a trustee shouldn’t assume the fund can buy a property from a member or relative. A specific exception may apply to qualifying business real property, but it isn’t automatic and doesn’t generally make a residential property eligible. The asset, relationship and proposed transaction all matter. Get legal and tax advice based on the facts before agreeing to a sale or transfer.
Can an SMSF rent business property to a member’s business?
Potentially, if the property qualifies as business real property and the relevant conditions are met. In broad terms, the property must meet the applicable test for use in a business; simply describing premises as commercial isn’t enough. The lease should be properly documented, and rent and other dealings should reflect market terms where required. Ask qualified legal and tax professionals to verify eligibility and review the lease and ongoing arrangement.
Can an SMSF borrow money to buy an investment property?
It depends on the property type and current rules. As at September 2026, new SMSF limited recourse borrowing arrangements can’t be used to buy residential property, while borrowing to acquire eligible business real property remains possible subject to requirements. Certain existing residential arrangements established before 10 August 2026 are grandfathered. An LRBA has specific structural rules and isn’t suitable by default. Have qualified lending, legal and tax specialists review any proposal before proceeding.
What happens if an SMSF breaches property investment rules?
A breach can lead to Australian Taxation Office scrutiny and consequences that depend on the facts, the nature of the breach and how it’s addressed. Possible outcomes may include compliance action, penalties or adverse tax treatment, and serious issues can affect the fund’s complying status. Don’t assume a breach can be fixed simply by selling the property. Trustees should seek prompt advice from an SMSF professional and respond to any regulator or auditor concerns.
Is buying property through an SMSF suitable for every investor?
No. Suitability depends on the fund’s objectives, members’ retirement timeframes, cash-flow needs, diversification and capacity to manage property costs and administration. A property may concentrate a large share of the fund in one asset and may be difficult to sell quickly. For members in Miranda or across the Sutherland Shire, local knowledge doesn’t replace a whole-of-fund assessment. Retirement modelling and superannuation advice can help compare property with alternative portfolio approaches, without guaranteeing an outcome.


