

What if your final years of full-time work weren't a stressful countdown to an abrupt stop, but a deliberate bridge to the Sutherland Shire lifestyle you've spent decades building? It's a common tension for many professionals in our community. You're at your peak earning capacity, yet the tax burden feels heavier than ever and the evolving complexity of superannuation rules often creates more questions than clarity. You shouldn't have to choose between your current lifestyle and your future legacy.
Seeking expert transition to retirement advice Sutherland Shire is no longer just about finding a tax loophole. It's about reclaiming your time without compromising your long-term financial security. This 2026 guide reveals how to access your superannuation while still working to effectively reduce your tax, optimise your savings under the latest contribution limits, and prepare for a seamless transition. We'll explore how bespoke modelling can transform your retirement goals into a structured, evidence-based reality, allowing you to scale back your hours while your wealth continues to grow with quiet certainty.
Key Takeaways
- Master the mechanics of a Transition to Retirement Income Stream (TRIS) to bridge the gap between your peak earning years and a more relaxed lifestyle without sacrificing your final balance.
- Navigate the 2026 regulatory landscape with confidence, specifically how to leverage tax-free pension earnings and the latest Superannuation Guarantee rates to your advantage.
- Utilise bespoke retirement modelling to stress-test your strategy, ensuring the transition to retirement advice Sutherland Shire professionals provide is grounded in your unique long-term projections.
- Align your financial structure with your personal aspirations, from a comprehensive superannuation review to planning for more leisure time at the Cronulla Golf Club.
- Understand the importance of a research-driven Investment Committee in constructing low-volatility portfolios that provide stability and peace of mind during your transition.
What is a Transition to Retirement (TTR) Strategy for Shire Residents?
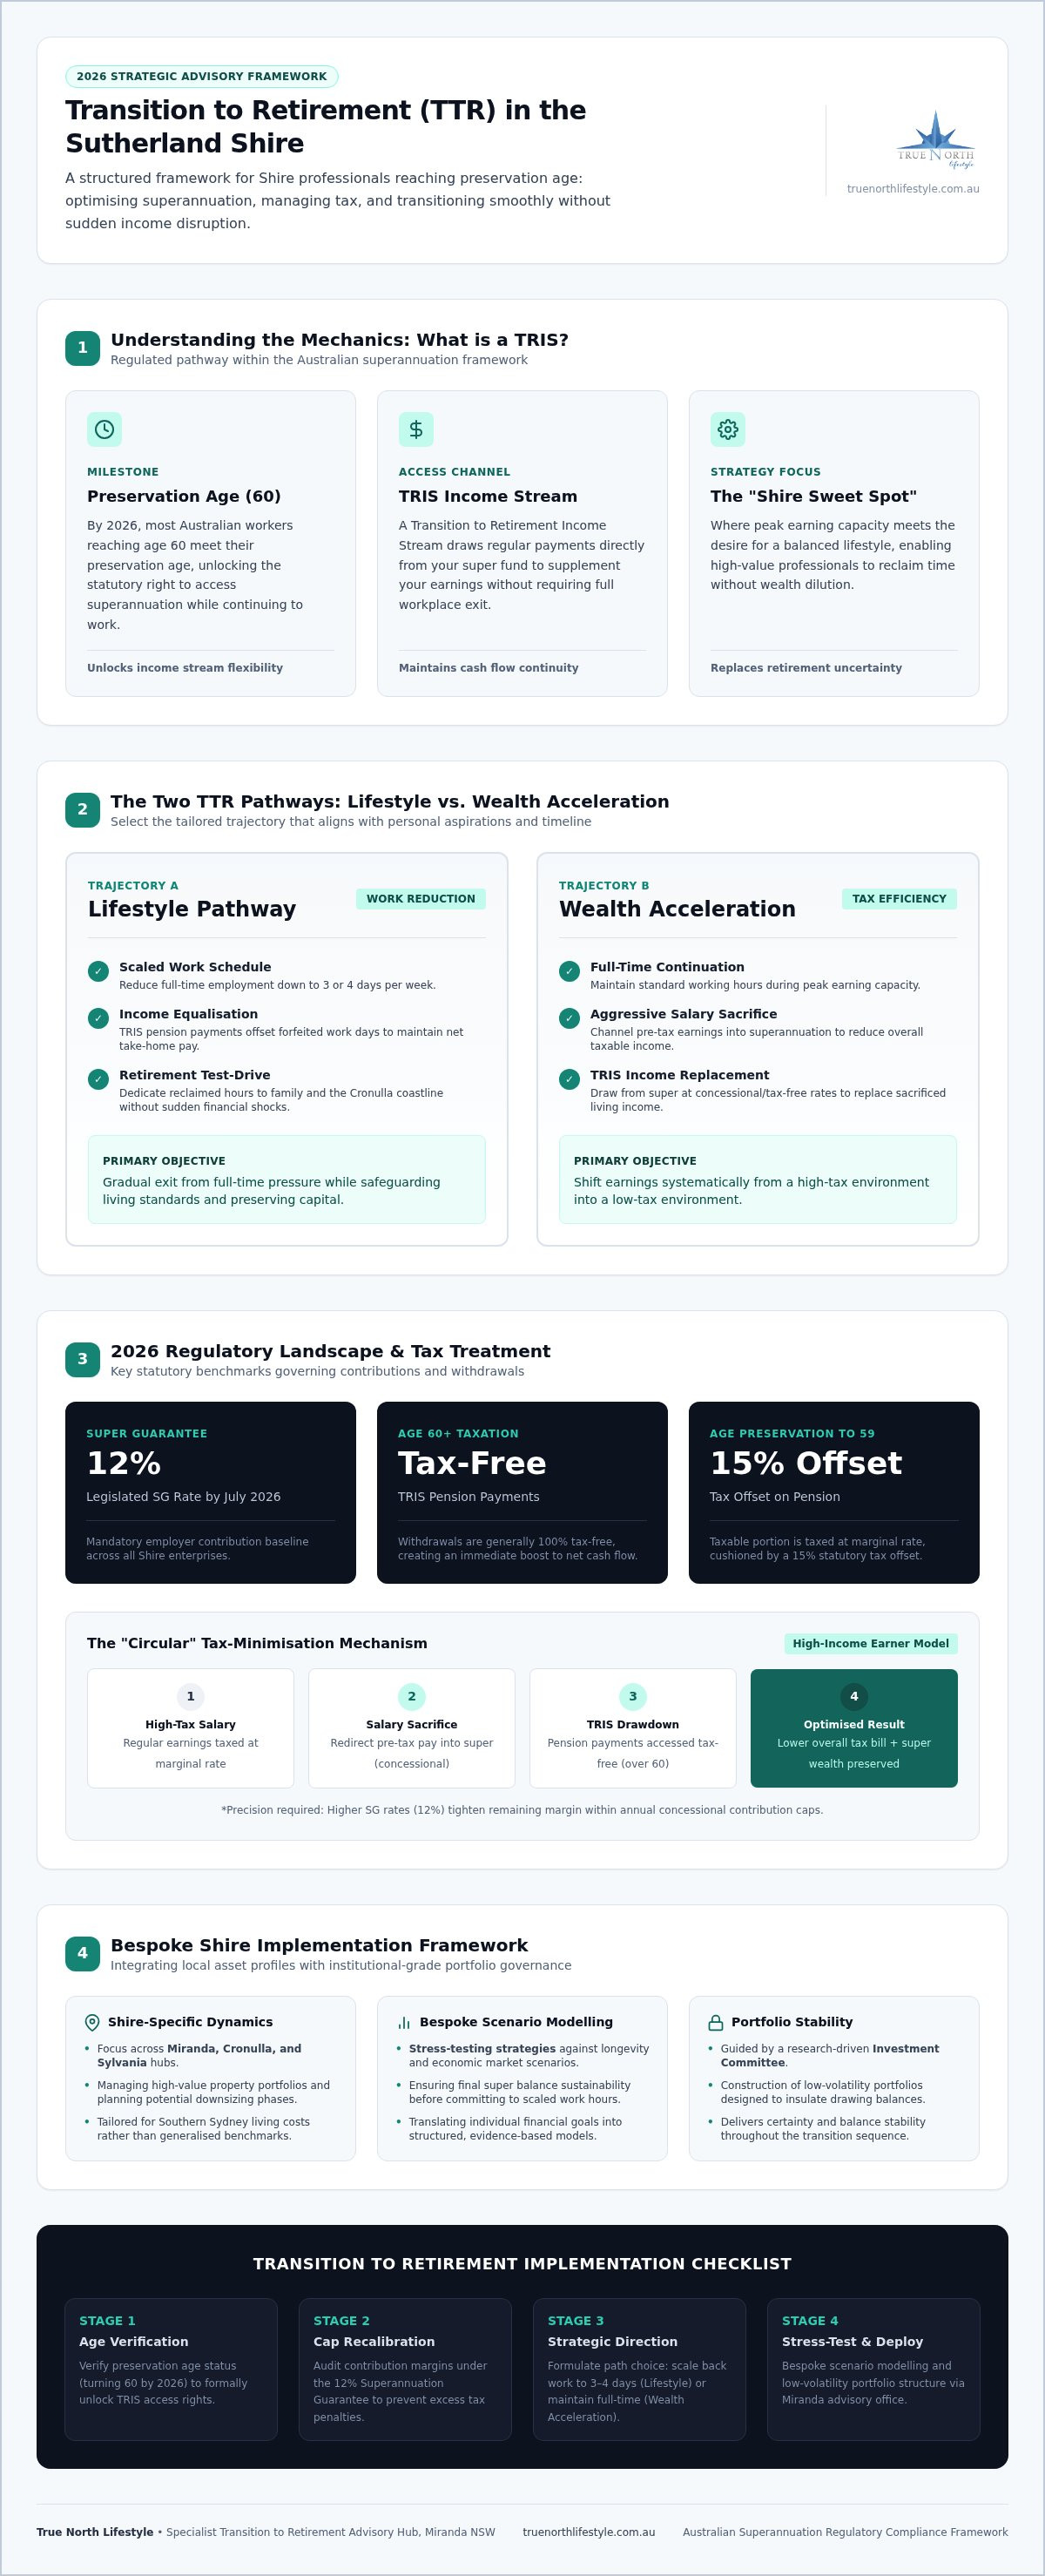
A Transition to Retirement Income Stream, commonly known as a TRIS, is a strategic financial tool designed to provide flexibility. It's not a complex loophole; it's a regulated pathway within the Australian superannuation framework that allows you to access a portion of your superannuation while you continue to work. By 2026, most residents reaching age 60 will have met their preservation age, unlocking the opportunity to restructure their income with precision. It's about taking control of your timeline.
For many local professionals, the appeal lies in what we call the "Shire Sweet Spot." This is the intersection where your career experience is at its highest, but your desire for a more balanced life is growing. Seeking transition to retirement advice Sutherland Shire helps you navigate this phase without the inherent anxiety of a sudden income drop. The goal is to replace uncertainty with a structured, modelled path that respects both your financial needs and your personal aspirations.
The Two Paths of TTR: Lifestyle vs. Wealth
Every person's "True North" is different. Your strategy will typically follow one of two distinct paths. Path A focuses on lifestyle. You might choose to reduce your working week to three or four days, perhaps spending more time at the Cronulla coastline or with family, while using your TRIS payments to maintain your current take-home pay. It's a way to test-drive retirement without fully committing to an exit.
Path B is about wealth acceleration. You continue working full-time but salary sacrifice a larger portion of your pay into super to reduce your taxable income. You then use the TRIS to replace that income, effectively moving money from a high-tax environment into a low-tax one. Deciding which path aligns with your goals requires rigorous modelling to ensure your final balance remains sustainable for the long term.
Why the Sutherland Shire Context Matters
Local context is vital. Residents in Miranda, Cronulla, and Sylvania often manage significant assets, including high-value property. Your retirement plan must account for the specific cost of living in Sydney’s south and the potential for future downsizing. Face-to-face transition to retirement advice Sutherland Shire ensures your modelling isn't just a generic projection. It's a bespoke plan that understands the nuances of our local community. Having a specialist office in Miranda provides a convenient hub for these important conversations, offering the quiet certainty you need to step forward with confidence.
The Mechanics of TTR: Navigating the 2026 Regulatory Landscape
Precision is paramount. By July 2026, the Superannuation Guarantee (SG) rate will have stabilised at 12%, providing a robust foundation for your retirement savings. While this legislated increase means your employer is contributing more, it also tightens the margin for error within your concessional contribution caps. Miscalculating these limits can lead to unnecessary tax penalties, making professional transition to retirement advice Sutherland Shire essential for high-income earners who want to maximise their contributions without breaching the rules.
The tax treatment of your income stream depends heavily on your age. For those over 60, pension payments from your TRIS are generally tax-free, offering a significant boost to your net cash flow. If you're between your preservation age and 60, the taxable portion of your pension is taxed at your marginal rate, but you'll receive a 15% tax offset to soften the impact. Following the ATO transition to retirement guidelines ensures your strategy remains compliant while you access these powerful financial incentives.
Tax-Minimisation Through Salary Sacrifice
Strategy matters. The most effective TTR plans involve a "circular" mechanism where you swap a portion of your high-tax salary for low-tax super contributions. You then draw a pension from your super to replace that sacrificed income. For a 62-year-old Shire professional, this strategy can effectively lower your total tax bill while simultaneously increasing your total super balance. It's a sophisticated way to keep more of what you earn while maintaining your lifestyle in the Miranda or Cronulla area.
2026 Thresholds and Limits
Stability requires vigilance. For the 2026 financial year, you must stay within the concessional and non-concessional cap limits to avoid unintended consequences. The Transfer Balance Cap also plays a critical role, limiting the total amount you can move into a tax-free pension phase over your lifetime. A "set and forget" approach is dangerous in this shifting regulatory environment. Regular reviews and bespoke retirement modelling are the only ways to ensure your portfolio remains optimised as legislation evolves, providing the quiet certainty you need for a successful transition.
Retirement Modelling: Proving the Sustainability of Your Transition
Logic and structure are the pillars of a successful transition. Think of retirement modelling as the GPS for your financial journey. It provides a clear, visual representation of your wealth over time, allowing you to see exactly how different TTR scenarios impact your capital. By using bespoke projections, we can determine if you can afford to reduce your working hours now without compromising your lifestyle in twenty years. This level of detail is the core of effective transition to retirement advice Sutherland Shire, moving beyond generic estimates to provide a personalised roadmap.
Timing is everything. One of the most significant threats during this phase is "Sequence of Returns Risk". This occurs when market volatility hits your portfolio just as you begin drawing down a pension. If values drop early in your transition, you're forced to sell more assets to meet the minimum drawdown requirements, which can permanently damage your fund's longevity. Modelling allows us to stress-test your strategy against these "bad timing" scenarios, ensuring your plan remains resilient regardless of market cycles. It replaces the anxiety of the unknown with a sense of quiet certainty.
Cash Flow Analysis: The Foundation of Clarity
Clarity precedes confidence. We begin by mapping your current expenses against your projected retirement lifestyle in the Shire. This isn't just about the weekly groceries; it's about accounting for "lumpy" expenses like a long-awaited European trip or renovations to a Cronulla home. The Moneysmart transition to retirement guide highlights the importance of balancing these drawdowns with salary sacrifice to maintain momentum. Our modelling identifies the precise "point of no return" for your capital, giving you the emotional reassurance to actually start working less.
Stress Testing Your Bespoke Portfolio
Resilience is built, not found. We test your plan against variables like high inflation or sustained market downturns to ensure it holds up under pressure. This process directly informs our portfolio construction. For TTR strategies, we often focus on low-volatility, income-focused investments that provide a steady stream of cash flow regardless of market sentiment. By linking your portfolio's structure to the results of your modelling, we ensure your wealth preservation is grounded in real-world probability. This research-driven approach allows you to step into a role of confident oversight during your transition.
Implementing Your TTR Plan in the Sutherland Shire
Execution requires a disciplined approach. Once the modelling has confirmed the viability of your strategy, moving from theory to practice involves a structured five-step process. This progression ensures that your transition is not only tax-effective but also aligned with the lifestyle you've envisioned for your later years. It's a methodical shift from wealth accumulation to a balanced state of preservation and enjoyment.
- Step 1: Conduct a comprehensive superannuation advice Sutherland Shire review to ensure your current fund is optimised for the pension phase.
- Step 2: Define your specific lifestyle goals, whether that's more weekday rounds at the Cronulla Golf Club or planning extended overseas travel.
- Step 3: Run the final numbers to compare a TTR strategy against a traditional retirement path to confirm the net benefit.
- Step 4: Formally establish the TRIS and coordinate with your employer to automate your salary sacrifice contributions.
- Step 5: Commit to an annual review to adjust for legislative changes and shifts in your personal circumstances.
This methodical implementation is what distinguishes professional transition to retirement advice Sutherland Shire from generic financial planning. It's about ensuring every moving part of your financial life is working in harmony to protect your wealth preservation goals. We focus on the human outcome, replacing the inherent complexity of the process with a sense of calm and order.
Centrelink and the Age Pension
Strategic structuring is essential for long-term entitlements. While you may be years away from qualifying for the Age Pension, the way you structure your TRIS assets now can impact future assessments. Centrelink applies both income and assets tests to transition to retirement income streams. For residents considering the "Shire Downsizing" rule, selling a larger family home in Miranda or Sylvania to move closer to the coast can release significant capital. Understanding how this surplus cash is treated under the assets test is vital for maximising your future government support.
Finding the Right Adviser in Miranda
Proximity offers a unique advantage. When seeking transition to retirement advice Sutherland Shire, look for a partner who prioritises research-driven, independent-minded strategies over bank-aligned products. Having a local hub in Miranda allows for regular, face-to-face strategic reviews that keep your plan on track as market conditions fluctuate. A steady navigator doesn't just set the course; they stay on the bridge with you as you move toward full retirement. To begin your own modelling process, you can request a bespoke retirement projection at our Miranda office to review your current trajectory.
Why True North Lifestyle is Your Steady Navigator
Clarity brings stability. At True North Lifestyle, we understand that the final years of your career are often the most complex. Our role as your steady navigator is to replace the inherent anxiety of financial decision-making with a sense of order. By providing expert transition to retirement advice Sutherland Shire, we ensure that every strategic move is grounded in evidence and tailored to your personal journey. We don't just provide numbers; we provide the quiet certainty that your future is protected, allowing you to focus on the life you've worked so hard to build.
Evidence drives outcomes. Our in-house Investment Committee provides rigorous oversight, managing low-volatility, income-focused portfolios that prioritise wealth preservation. This research-driven methodology is essential for Shire residents who require a reliable anchor in a fluctuating economic environment. We focus on longevity planning, ensuring your capital lasts as long as your lifestyle requires, allowing you to step into retirement with confident oversight. By managing risk at the portfolio level, we seek to mitigate the impact of market downturns during your critical transition phase, providing a buffer against the unknown.
Bespoke Solutions, Not Off-the-Shelf Products
Tailoring is essential. Larger institutions often rely on cookie-cutter products that fail to account for the nuances of your family and estate goals. We believe in bespoke investment advice Sydney professionals can trust, where every portfolio is constructed to meet specific risk profiles and income needs. Whether you're planning for your children's inheritance or securing your own comfort in the Shire, your TTR strategy should be as unique as your lifestyle. We avoid the "one size fits all" mentality, focusing instead on the human outcomes of our strategic construction.
Taking the Next Step Toward Clarity
Confidence starts here. Your first discovery meeting at our Miranda office is designed to provide immediate clarity without the burden of complex jargon. We'll discuss your current trajectory, identify potential tax-minimisation opportunities, and begin the process of modelling your ideal transition. The peace of mind that comes from a structured, modelled path is invaluable. It's about moving from a state of uncertainty to knowing you've done the heavy lifting. We invite you to book a strategy session today to see how a modelled approach and specialist transition to retirement advice Sutherland Shire can transform your retirement outlook and provide the stability you deserve.
Secure Your Path to a Purposeful Retirement
Transitioning toward retirement shouldn't be a source of anxiety. By leveraging a Transition to Retirement Income Stream, you can effectively reduce your tax burden while maintaining the lifestyle you enjoy across Miranda and Cronulla. The 2026 regulatory landscape offers unique opportunities for those who act with precision, using bespoke retirement modelling for every client to ensure every decision is grounded in real-world probability rather than guesswork.
True North Lifestyle stands as your steady navigator in this journey. Our research-driven Investment Committee and status as specialists in Sutherland Shire retirement planning provide the disciplined oversight your wealth deserves. We focus on the human outcome, replacing technical complexity with a clear, modelled path that protects your capital longevity. It's about moving from a role of constant effort to one of confident oversight.
Ready to reclaim your time? Book your TTR strategy session at our Miranda office to access specialist transition to retirement advice Sutherland Shire. Let's build a strategy that provides the quiet certainty you need to step forward into your next chapter with confidence.
Frequently Asked Questions
Can I still contribute to my super while receiving a TTR pension?
Yes, you can continue making contributions to your superannuation accumulation account while simultaneously receiving payments from your pension account. Many residents in the Shire use this strategy to replace income that they then salary sacrifice back into super. This approach helps lower your taxable income while continuing to build your retirement nest egg. It's a central element of the transition to retirement advice Sutherland Shire professionals provide to optimise your financial position.
What is the minimum and maximum I can withdraw from a TTR pension in 2026?
For the 2026 financial year, the minimum annual withdrawal is typically 4% of your account balance, while the maximum is strictly capped at 10%. These legislated boundaries ensure the income stream supports your current needs without prematurely exhausting your capital. Our Miranda based team uses bespoke modelling to help you determine a drawdown rate that provides the necessary cash flow while maintaining the long term sustainability of your portfolio.
Will a TTR strategy affect my employer’s Super Guarantee contributions?
A TTR strategy does not reduce your employer's Super Guarantee (SG) obligations. Your employer is still required to pay the legislated SG rate, which reaches 12% by July 2026, based on your ordinary time earnings. These contributions will continue to flow into your accumulation account even though you are drawing an income from your pension account. It's essential to monitor these contributions during your annual review to ensure your employer remains compliant.
Is a Transition to Retirement strategy tax-free if I am over 60?
Yes, for most Australians aged 60 and over, the pension payments you receive from a TTR income stream are tax-free. This provides a significant boost to your take-home pay compared to standard salary. While the investment earnings inside the TTR account itself are still taxed at up to 15%, the actual money you withdraw is generally exempt from personal income tax, making it a highly effective tool for wealth preservation in your peak earning years.
Do I need a certain amount in super to make a TTR strategy worthwhile?
There is no legislated minimum balance, but the strategy is generally most effective for those with substantial super balances. Typically, a balance over A$200,000 provides the scale needed for the tax savings and benefits to outweigh the administrative costs of running the pension. We recommend a comprehensive superannuation review at our Miranda office to ensure the numbers align with your specific goals before you commit to the implementation process.
How does a TTR strategy differ from a standard account-based pension?
The primary differences involve withdrawal limits and tax on earnings. A TTR pension (TRIS) has a 10% maximum annual withdrawal cap, and the investment earnings within the fund are taxed at 15%. In contrast, a standard account-based pension has no maximum withdrawal limit, and the investment earnings are tax-exempt. A TRIS is designed as a bridge while you are still working, whereas a standard pension is for those who have fully retired.
Can I stop a TTR strategy if my circumstances change?
Yes, you have the flexibility to stop a TTR strategy at any time by rolling your pension balance back into an accumulation account. This is particularly useful if your employment situation changes or if your lifestyle goals shift. Expert transition to retirement advice Sutherland Shire ensures that your plan includes a clear exit strategy, allowing you to remain in control of your financial assets and adapt to any unforeseen changes in your personal or professional life.
What happens to my TTR pension when I reach age 65 or fully retire?
When you reach age 65 or notify your super fund that you have fully retired, your TTR pension automatically converts into a standard account-based pension. At this milestone, the 10% maximum withdrawal cap is removed, and the investment earnings within the account become tax-free. This transition is a key part of our longevity planning, helping you move from a working bridge into a permanent, tax-effective retirement phase with quiet certainty.


