

Price is what you pay; value is what you keep. For many families in the Sutherland Shire, researching the cost of financial advice Miranda often leads to more questions than answers. You might feel a lingering anxiety over hidden commissions or the frustration of trying to decode the difference between initial and ongoing fee structures. It's a common concern, especially when you're looking for a partner to protect your legacy rather than just sell a generic product.
We believe that professional guidance should offer total transparency and a clear path toward lifestyle certainty. You deserve to know exactly how your investment in advice translates into a more secure future. This guide provides a clear breakdown of fee structures for 2026 and explains how to measure the real-world impact of bespoke retirement strategies. We'll examine how disciplined tax minimisation and superannuation modelling can transform a professional fee into a vehicle for long-term wealth preservation and personal confidence.
Key Takeaways
- Gain clarity on the modern fee-for-service landscape, where transparent structures replace the uncertainty of hidden commissions.
- Explore how the cost of financial advice Miranda is determined by the complexity of your personal wealth, including SMSFs and bespoke retirement modelling.
- Identify the Statement of Advice as your definitive strategic roadmap, built on rigorous research to ensure your capital lasts through retirement.
- Evaluate the real-world value of professional guidance by looking at the long-term impact of tax-minimisation and superannuation strategies.
- Understand why a tailored approach from an in-house Investment Committee offers greater security than standardised, national advice models.
Understanding the Financial Advice Fee Landscape in Miranda
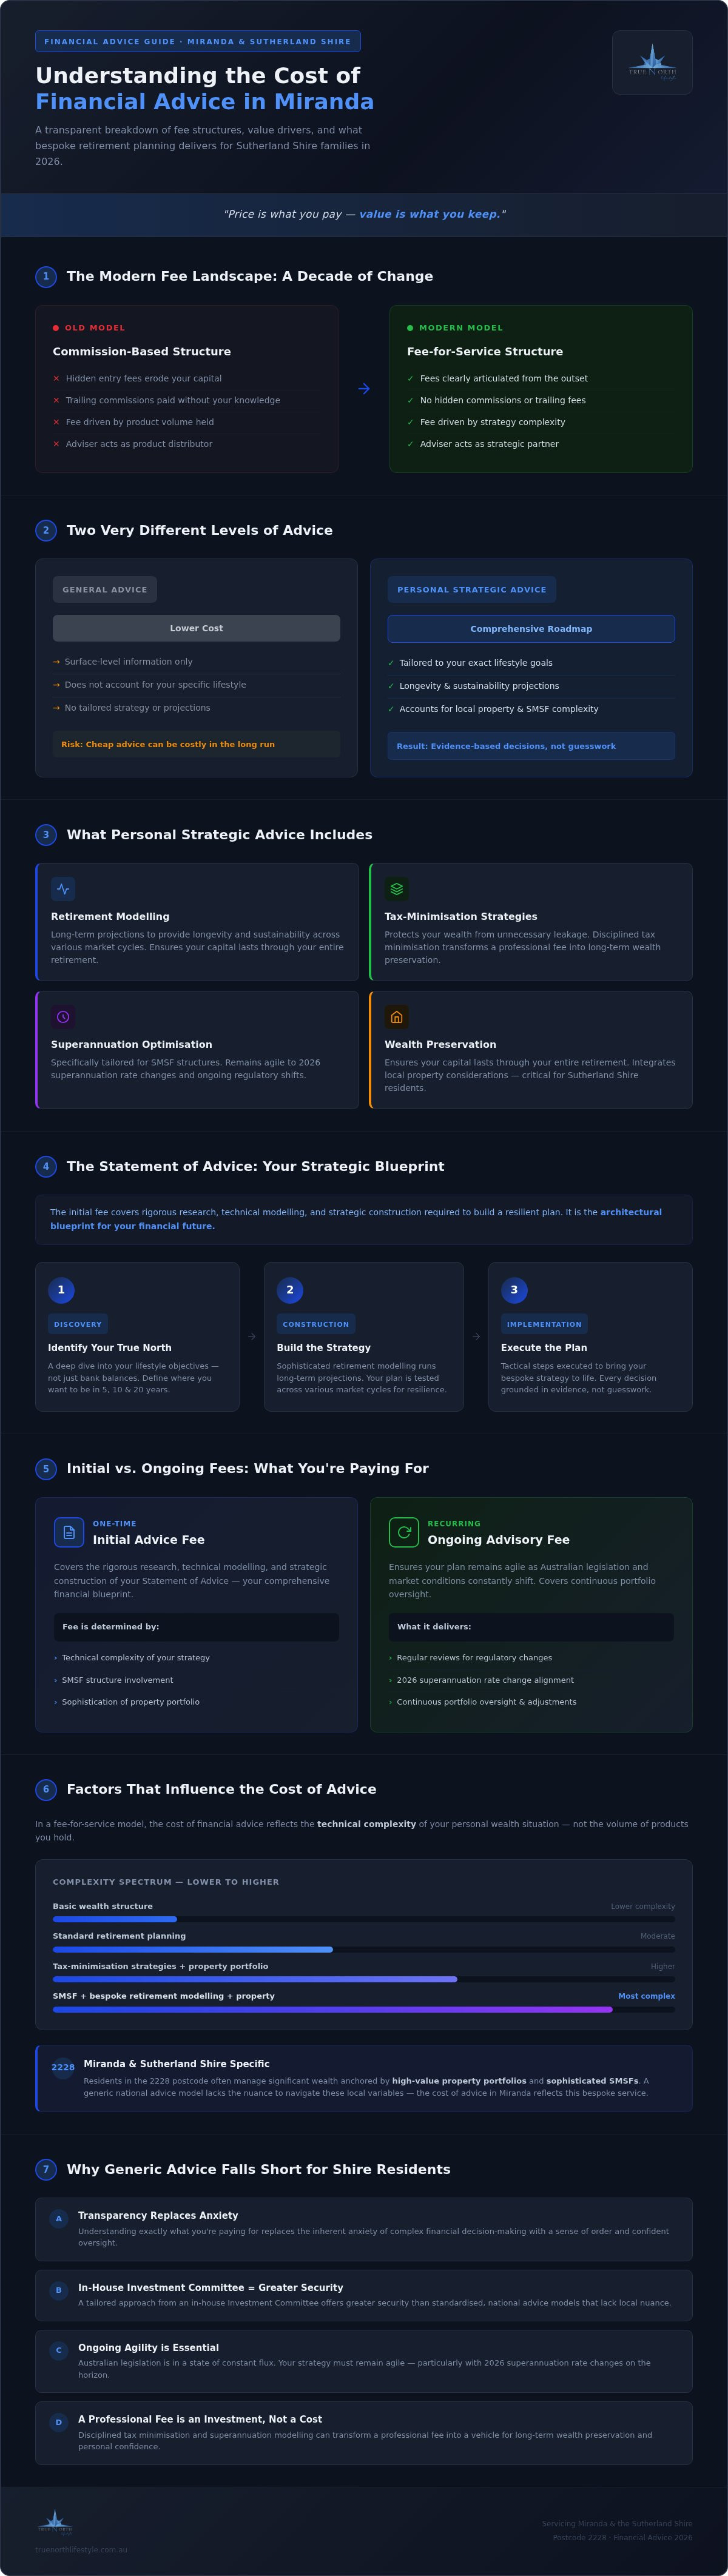
Clarity brings peace. The Australian financial services industry has undergone a significant transformation over the last decade, moving away from opaque commission structures toward a professional, fee-for-service model. The role of a financial adviser has transitioned from a product distributor to a strategic partner. This evolution ensures that the cost of financial advice Miranda is determined by the technical complexity of your strategy rather than the volume of products you hold. It's a shift that prioritises your outcomes above all else.
The Shift from Commissions to Professional Fees
True transparency is the foundation of trust. Modern advisers now operate with the same professional rigour as solicitors or accountants. In a professional practice, you won't encounter hidden entry fees or trailing commissions that erode your capital over time. Instead, fees are clearly articulated at the outset of the engagement. This approach replaces the inherent anxiety of complex financial decision-making with a sense of order. When you understand exactly what you're paying for, you can focus on the human outcomes of your strategy, such as the freedom to retire early or the security of a legacy for your family.
Why Local Expertise Matters in the Sutherland Shire
Miranda is unique. Residents in the 2228 postcode often manage significant wealth, frequently anchored by high-value property portfolios and sophisticated Self-Managed Super Funds (SMSFs). A generic, national advice model often lacks the nuance required to navigate these local variables. For a pre-retiree in the Shire, the cost of financial advice Miranda reflects a bespoke service that integrates local property considerations with complex tax-minimisation strategies.
There is a vital distinction between "general advice" and "personal strategic advice." General advice is often low cost but provides only surface-level information that doesn't account for your specific lifestyle. Personal strategic advice, however, is a comprehensive roadmap tailored to your exact needs. This professional guidance includes:
- Retirement modelling to provide longevity and sustainability projections.
- Tax-minimisation strategies that protect your wealth from unnecessary leakage.
- Superannuation optimisation, specifically for those with SMSF structures.
- Wealth preservation to ensure your capital lasts through your entire retirement.
We act as your Steady Navigator. By simplifying the complex and providing a structured path forward, we help you step into a role of confident oversight. This disciplined, research-focused approach ensures that your financial journey is grounded in evidence rather than guesswork.
Initial vs. Ongoing Fees: What Does a Statement of Advice Cost?
Structure creates stability. When you begin your journey toward financial clarity, the first milestone is the Statement of Advice (SoA). This document is far more than a simple report; it's a comprehensive roadmap designed to navigate the complexities of your personal wealth. Understanding typical financial adviser fee structures is the first step in assessing the cost of financial advice Miranda. The initial fee covers the rigorous research, technical modelling, and strategic construction required to build a resilient plan. It is the architectural blueprint for your financial future.
The Statement of Advice (SoA) Process
Your goals come first. The process begins with a discovery phase where we identify your lifestyle objectives and define your "True North." This isn't a surface-level conversation about bank balances. It's a deep dive into what you want your life to look like in five, ten, and twenty years. Once these goals are established, our team moves into strategy construction. We use sophisticated retirement modelling to run long-term projections, ensuring your capital can withstand various market cycles. The final stage is implementation, where we execute the tactical steps required to bring your bespoke strategy to life. This methodology ensures every decision is grounded in evidence rather than guesswork.
Ongoing Management and Portfolio Oversight
The landscape never stops shifting. Australian legislation is in a state of constant flux, and your strategy must remain agile to be effective. Regular reviews are essential to account for the 2026 superannuation rate changes and other regulatory shifts that impact your wealth. Ongoing advisory fees ensure your plan remains aligned with these developments while providing continuous portfolio oversight. This level of care replaces the anxiety of the unknown with a sense of quiet certainty.
Unlike generic investment platforms that offer "off-the-shelf" solutions, our approach involves active management through an in-house Investment Committee. This provides a layer of institutional-grade research and risk management that "set and forget" models simply cannot match. For those seeking deeper fund optimisation, our guide on Superannuation Advice Sutherland Shire offers further insights into strategic wealth construction. It's about ensuring your portfolio remains resilient against volatility while prioritising longevity.
Maintaining this level of bespoke care requires a disciplined, ongoing commitment. It's about protecting what you've built while seeking steady growth. If you're ready to see how a structured plan can provide lifestyle certainty, you might consider reviewing your current wealth projections with a specialist who understands the Miranda landscape.
Factors Influencing the Cost of Professional Advice in Miranda
Complexity drives time. Wealth in the Sutherland Shire is often multifaceted, involving far more than just a single superannuation account or a primary residence. When assessing the cost of financial advice Miranda, it's essential to understand that professional fees are a direct reflection of the technical hours required to manage your specific asset base. Sophisticated structures, such as family trusts or private company holdings, require a higher level of strategic construction and ongoing compliance than a standard retail fund. We act as your steady navigator, ensuring these moving parts work in harmony.
Tax minimisation requirements also play a pivotal role in determining the depth of an advisory engagement. Navigating Capital Gains Tax (CGT) on investment properties or executing complex re-contribution strategies involves intensive modelling to prevent unnecessary wealth leakage. For a deeper look at these methods, you may find our strategic guide on Tax Planning for Retirement Australia useful for understanding how we protect your capital.
SMSF and Complex Trust Structures
Specialised oversight is vital. Self-Managed Super Funds (SMSFs) are prevalent across Miranda and the wider Shire, yet they demand a rigorous level of compliance and strategic management. Advice in this area isn't just about investment selection; it's about maintaining the structural integrity of the fund while managing intergenerational wealth transfer. A bespoke estate planning strategy is often integrated into these plans to ensure your legacy is protected and passed on according to your exact wishes. This level of comprehensive care requires a disciplined, research-focused approach that moves beyond generic templates.
Retirement Projections and Cash Flow Modelling
Accuracy builds confidence. To provide a sense of quiet certainty, we conduct intensive research to produce accurate long-term projections. This involves stress-testing your portfolio against the specific economic variables of 2026, such as shifting inflation rates and potential market volatility. We don't rely on "off-the-shelf" projections. Instead, we build sustainability models that account for your unique lifestyle goals and longevity needs. You can explore our approach to Retirement Planning Sydney to see how these detailed cash flow models provide the clarity needed for a secure future. By simplifying the complex, we empower you to make informed choices without feeling overwhelmed by the technical data.
Assessing the Value: Why "Cheap" Advice Can Be Costly
Value is objective. While the initial cost of financial advice Miranda is a logical consideration, the true measure of professional guidance is found in the net benefit to your lifestyle. The return on investment for advice is defined as the delta between a self-managed outcome and a professionally optimised strategy. This isn't just about portfolio performance; it's about the technical construction that ensures you keep more of what you earn. Lower-cost alternatives often carry hidden burdens, such as restricted product menus or inherent conflicts of interest that limit your strategic potential.
Certainty is earned through rigorous testing. Beyond the numbers, the most profound benefit of a bespoke strategy is the sense of quiet confidence it provides. Knowing that your capital is protected against market volatility and that your legacy is secure allows you to focus on living your life rather than managing your spreadsheets. This peace of mind is an intangible but vital component of long-term wealth preservation.
Tax and Superannuation Optimisation
Efficiency saves capital. A disciplined re-contribution strategy can save your estate thousands of dollars in death benefits tax, ensuring more of your wealth passes to your beneficiaries rather than the revenue office. We also focus on strategic superannuation contributions to reduce your taxable income, effectively turning a tax liability into a retirement asset. As we move into 2026, maximising the increased Superannuation Guarantee rates is essential for long-term growth. These technical adjustments, while subtle, provide a compounding benefit that far outweighs the professional fee required to implement them.
The Cost of Inaction
Structure provides safety. Many Australians inadvertently miss out on Age Pension entitlements due to poor asset structuring or a failure to understand Centrelink's complex means-testing. In a fluctuating 2026 environment, a "set and forget" approach is a significant liability. One of the greatest risks to a new retiree is sequence of returns risk, where a market downturn in the early years of retirement can permanently damage the longevity of your capital. Without a plan to mitigate this, your lifestyle is left to chance. A professionally managed strategy acts as a steady navigator, adjusting your path as the economic climate shifts. If you are ready to secure your future, book a strategy review to see the tangible value we can add to your retirement journey.
Clarity and Confidence: Tailored Financial Strategies at True North
Clarity is the antidote to anxiety. At True North Lifestyle, our commitment to transparent, value-based pricing ensures that the cost of financial advice Miranda is always aligned with the tangible outcomes we deliver for your family. We don't believe in hidden fees or complex jargon. Instead, we offer a structured path that replaces uncertainty with a sense of order and quiet certainty. By simplifying the technical aspects of wealth preservation, we empower you to make informed choices without feeling overwhelmed by the process.
Bespoke Portfolio Construction
Stability requires discipline. We avoid cookie-cutter portfolios in favour of research-driven strategies constructed by our in-house Investment Committee. This group provides a level of technical depth that standard platforms cannot match, focusing specifically on income generation and wealth preservation for Sydney retirees. By prioritising low-volatility assets, we ensure your capital remains resilient against market fluctuations while maintaining the growth necessary to outpace inflation. Our methodology is grounded in real-world probability, allowing you to step into a role of confident oversight rather than constant worry. You can see our approach to Bespoke Investment Advice Sydney to understand how we craft stability for your lifestyle in 2026.
Your Path to a Calm Retirement
The journey begins with a conversation. Our "Steady Navigator" process moves methodically from initial modelling to comprehensive legacy planning, ensuring every decision is backed by evidence. We invite Miranda residents to gain total clarity on their financial future through a process that values trust and proven outcomes over flashy innovation. This progression from financial anxiety to a well-defined path is the hallmark of our service. It's about protecting what you've built while seeking a life of freedom.
The first step is the discovery meeting. This is a dedicated time to identify your personal "True North" and map out the tactical strategies required to get there. We do the heavy lifting, the rigorous testing, and the complex projections so you don't have to. It's about creating a bespoke strategy that reduces tax and maximises super, giving you the confidence that your capital will last through your entire retirement. If you're ready to secure your legacy, you can enquire about our financial advice fees and services in Miranda to begin your transition toward a state of quiet certainty.
Step Into a Role of Confident Oversight
Lifestyle certainty is a deliberate choice. We've explored how the cost of financial advice Miranda reflects the technical depth of bespoke retirement modelling and the tangible value of strategic tax minimisation. When you look beyond the professional fee, you find a framework specifically designed to protect your legacy and ensure your capital outlasts your retirement years. It's about moving from a place of complexity to a state of order.
Our in-house Investment Committee provides the rigorous oversight required for low-volatility portfolio construction, while our Miranda 2228 local expertise ensures your strategy accounts for the unique wealth landscape of the Sutherland Shire. By replacing financial anxiety with evidence-based logic, we help you transition toward a future defined by quiet certainty. You've done the hard work of building your wealth; now it's time to ensure it's protected for the long term.
If you're ready to secure your legacy with a plan built on research rather than guesswork, we invite you to take the first step toward clarity. Secure Your Financial Future: Book a Consultation in Miranda. You deserve a partner who has already done the heavy lifting, allowing you to enjoy the retirement you've worked so hard to build.
Frequently Asked Questions
How much does an initial Statement of Advice (SoA) cost in Miranda?
The cost of an initial Statement of Advice (SoA) is determined by the technical complexity and depth of the strategy required. For many residents in the Sutherland Shire, high-value property assets and SMSF structures necessitate intensive research and modelling. This professional fee covers the entire discovery process, strategy construction, and the detailed implementation roadmap that brings your retirement goals into clear, actionable focus.
Are financial planning fees tax deductible in Australia?
Generally, ongoing advisory fees related to managing investments that generate assessable income are tax deductible. However, the initial fee for the Statement of Advice is typically viewed as a capital expense and isn't deductible. It's vital to consult with a qualified accountant to determine how these rules apply to your specific situation, as tax legislation is subject to change and individual circumstances vary.
What is the difference between a flat fee and an asset-based fee?
A flat fee is a fixed dollar amount charged for a specific professional service, providing total transparency regardless of your portfolio's size. In contrast, an asset-based fee is calculated as a percentage of your total funds under management. Many modern firms prefer fixed, value-based pricing models to ensure total fee transparency and to eliminate potential conflicts of interest inherent in percentage-based structures.
Do I have to pay for the first meeting with a financial adviser?
Many professional firms offer an initial discovery meeting to identify your lifestyle goals and determine if a strategic partnership is appropriate. This session provides an opportunity to understand our research-driven methodology and for us to assess the technical complexity of your wealth. It's a vital step in replacing the inherent anxiety of financial planning with a sense of order and quiet certainty.
How do ongoing fees work if my financial situation changes?
Ongoing fees are designed to provide continuous oversight and agility as your financial situation evolves over time. If your circumstances change, such as through downsizing your home or receiving an inheritance, your strategy is reviewed and updated. This ensures your retirement modelling remains accurate and your portfolio remains resilient against market volatility, providing the stability you need to make informed choices.
Can I pay for financial advice using my superannuation fund?
You can often pay for advice that specifically relates to your superannuation directly from your fund balance. This approach can assist with your personal cash flow while ensuring your retirement savings are professionally optimised. There are strict regulatory guidelines regarding which types of advice can be funded this way, so we provide clear guidance on how to navigate these requirements with total transparency.
What should be included in a transparent Fee Disclosure Statement (FDS)?
A transparent Fee Disclosure Statement (FDS) must clearly outline the services you were entitled to, the services you actually received, and the exact dollar amount you paid over the previous year. It's a critical document for ensuring you only pay for the professional value provided. This level of reporting reflects a commitment to simplifying the complex and maintaining an honest, trust-based relationship.
Is bespoke investment advice more expensive than a standard retail fund?
The cost of financial advice Miranda for a bespoke strategy reflects the intensive research and customisation required to protect your legacy. While standard retail funds use generic, "off-the-shelf" models, bespoke advice involves in-house Investment Committee oversight and risk-management tailored to your unique tax position. The real-world value is often found in the delta between a DIY outcome and a professionally optimised, low-volatility portfolio.


