

What if the autonomy you are searching for in a Self-Managed Super Fund (SMSF) isn't actually about the individual stocks, but about the quiet certainty of your future lifestyle? It's a question many professionals ask when considering superannuation planning sydney, especially as they feel increasingly like a number in large institutional funds. When transparency is low and the anxiety of 2026 market volatility is high, the desire for bespoke control becomes more than a preference; it becomes a necessity for protecting your family legacy.
We believe that financial decisions should replace stress with order. This article provides a strategic comparison to help you decide if the SMSF structure is the right vehicle for your specific needs. We'll explore how sophisticated retirement modelling and tailored portfolio construction can move you away from generic templates and toward a structured, well-defined path for your Sydney retirement. By the end of this guide, you'll have the clarity required to determine if taking the helm of your superannuation aligns with your long-term vision for stability and growth.
Key Takeaways
- Understand how the direct control of an SMSF provides the transparency needed to navigate market volatility and align with your specific lifestyle goals.
- Evaluate the shift from percentage-based industry fees to a fixed-cost administrative structure as a core component of effective superannuation planning sydney.
- Gain clarity on the legal responsibilities of becoming a trustee, from maintaining compliance to managing annual audit obligations.
- Discover the role of bespoke retirement modelling in transforming complex financial data into a clear, long-term cash flow projection.
- Learn why a research-driven investment strategy is vital for protecting your family legacy and ensuring portfolio sustainability.
Understanding SMSF Advice: Why Control Matters in 2026
Control is clarity. For many Sydney professionals, a Self-Managed Super Fund (SMSF) represents the ultimate strategic vehicle for retirement. It's not just a collection of assets; it's a deliberate choice to step away from the opaque nature of institutional funds. Within the broader Australian superannuation framework, the SMSF stands out as the only structure that grants you total transparency over where your capital is deployed and how it's managed. This isn't about complexity for the sake of it. It's about ensuring your wealth serves your specific lifestyle.
As we navigate the market conditions of 2026, volatility has become a persistent concern. Sydney investors are increasingly wary of being just another number in a retail fund that lacks the agility to respond to shifting economic signals. They want to know exactly how their family legacy is protected. There's a fundamental difference between simply running a fund and executing a bespoke strategy. One is an administrative burden; the other is a visionary path toward longevity. By shifting the focus to strategic oversight, you move from passive participation to active wealth preservation.
The Shift Toward Bespoke Superannuation
One size fits none. The limitations of "balanced" or "growth" templates in industry funds often leave high-net-worth individuals feeling exposed during downturns. Effective superannuation planning sydney allows for the removal of these generic constraints. By tailoring the fund to your specific lifestyle goals, you simplify the complex web of regulatory rules into a manageable, personal roadmap. This provides an immense emotional benefit: the quiet certainty that your retirement isn't left to a committee you'll never meet. It turns your superannuation into a living document that reflects your values and your future needs.
Control vs. Responsibility: The Professional Balance
Ownership requires discipline. While the appeal of an SMSF is the freedom to choose, that freedom must be grounded in a research-driven methodology. It's not about following a market whim; it's about evidence-based portfolio construction. This is where the role of an adviser shifts from a mere service provider to a Steady Navigator. We help you balance personal preferences with the rigorous testing required for long-term sustainability. True control isn't found in doing every task yourself, but in having the oversight to ensure every move is backed by logic and strategic modelling. It's about being empowered to make informed choices without feeling overwhelmed by the technicalities of the law.
SMSF vs Industry Funds: A Strategic Comparison for Sydney Investors
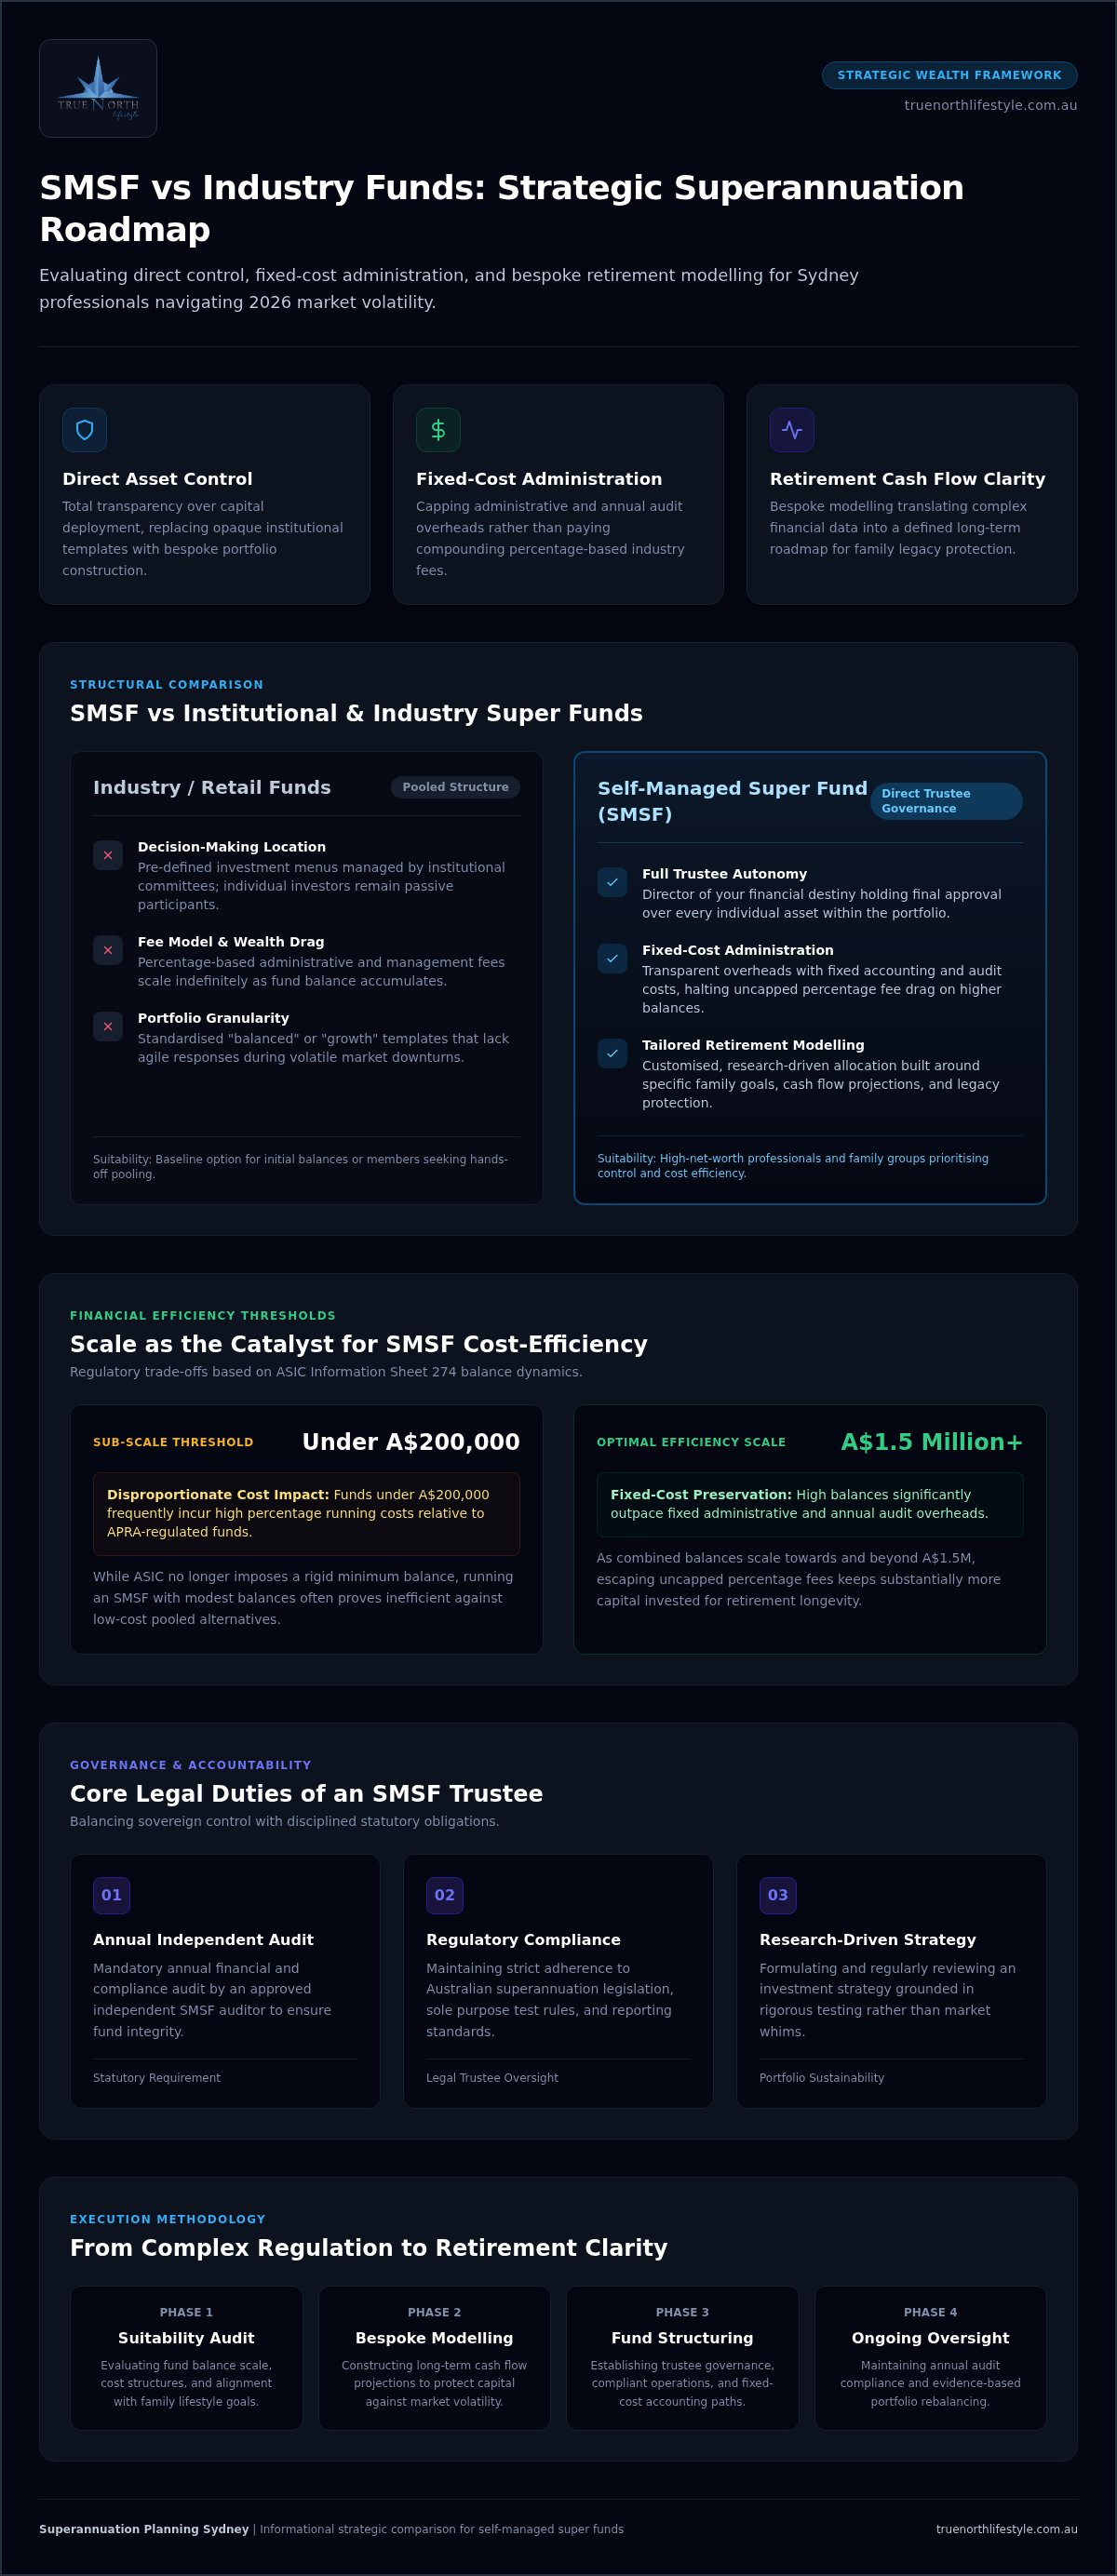
Choice defines your retirement experience. While industry funds offer a functional baseline for many, they often lack the granularity required for sophisticated superannuation planning sydney. The primary distinction lies in transparency and the location of decision-making power. In a retail or industry fund, you're a participant in a pooled environment where investment menus are pre-defined. In an SMSF, you're the director of your financial destiny, holding the final call on every asset within the portfolio. This shift from passive observer to active trustee replaces institutional ambiguity with quiet certainty.
Fee structures represent the second major battleground. Most industry funds charge percentage-based administration and investment fees. While this model is accessible for those starting out, it can become an uncapped drain on wealth for high-balance members. As assets scale towards A$1.5 million or more, the percentage-based "drag" often far exceeds the fixed-cost overheads of an SMSF. By opting for a structure with fixed annual audit and accounting costs, you gain a level of fee transparency that is simply unavailable in traditional institutional models.
When Does an SMSF Become Cost-Effective?
Scale is the catalyst for efficiency. While ASIC's Information Sheet 274 no longer mandates a rigid minimum balance, funds with less than A$200,000 often face disproportionately high percentage running costs compared to APRA-regulated alternatives. Many families in the Sutherland Shire find that as their combined balances grow, the fixed-cost nature of an SMSF becomes a powerful tool for wealth preservation. This allows you to bypass the hidden costs often embedded in retail funds, ensuring more of your capital remains working for your future. For a neutral regulatory perspective on these trade-offs, the Moneysmart guide to self-managed super funds provides a helpful baseline for suitability.
Investment Flexibility and Direct Assets
Diversification goes deeper than just shares and bonds. One of the most compelling reasons for Sydney business owners to pivot toward an SMSF is the ability to hold business real property. Following the regulatory changes in August 2026, which restricted new residential borrowing, the continued exemption for commercial premises remains a vital strategic advantage. This allows medical specialists, consultants, and entrepreneurs to acquire their own offices or suites within their super fund, leasing them back to their trading business at market rates. Achieving this level of integration requires bespoke investment advice Sydney to ensure the strategy is both compliant and optimised for longevity.
Deciding between a pooled fund and a private structure is a significant milestone in your financial journey. If you're questioning whether your current provider still aligns with your lifestyle goals, a professional superannuation review and optimisation can provide the data-driven clarity you need to move forward with confidence.
Navigating the Compliance Landscape: Duties of an SMSF Trustee
Responsibility is the price of control. When you establish an SMSF, you step into a dual role as both a member and a trustee, or a director of a corporate trustee. This shift means you're no longer a passive participant in the superannuation planning sydney landscape; you're the primary person responsible for the fund's adherence to the law. While this level of oversight is empowering, it requires a disciplined approach to governance. Every decision, from asset acquisition to benefit payments, must be backed by a clear understanding of your statutory obligations.
The Australian Taxation Office (ATO) remains the central regulator in this environment. To maintain your fund's complying status, you must navigate a rigorous schedule of annual obligations. This includes the preparation of financial statements, the lodgement of annual tax returns, and the payment of the SMSF supervisory levy, which currently stands at A$259 for established funds. Central to these duties is the "Sole Purpose Test." This foundational rule dictates that your fund must be maintained for the single purpose of providing retirement benefits to its members. Any personal use of fund assets, such as holidaying in a residential property owned by the fund, represents a severe breach that can lead to significant financial penalties. For a detailed breakdown of these responsibilities, refer to the ATO SMSF trustee compliance requirements.
The Compliance Safety Net
Order replaces anxiety. A professional advisory partnership acts as a vital safety net, ensuring your records are organised and your portfolio is regularly stress-tested against shifting regulations. The ATO requires every SMSF to have a documented investment strategy that is reviewed at least annually. This isn't a mere "set and forget" document. It must consider the whole circumstances of the fund, including risk, return, liquidity, and the diversity of assets. By maintaining a meticulous audit trail throughout the year, the annual independent audit becomes a seamless process rather than a source of stress.
Estate Planning and the SMSF
Succession planning is essential. One of the most significant advantages of an SMSF is the ability to draft custom, non-expiring Binding Death Benefit Nominations (BDBN). Unlike industry funds, where a trustee may have discretion over who receives your balance, a well-drafted BDBN in an SMSF provides quiet certainty that your family legacy is protected. This level of control allows you to integrate sophisticated wealth transfer strategies Australia directly into your fund's deed. It ensures that when a trustee passes or loses capacity, the transition of control is structured, legal, and aligned with your long-term vision for wealth preservation.
Strategic SMSF Planning: Beyond Just Setting Up the Fund
Establishing the structure is the technical starting line. However, the true efficacy of superannuation planning sydney is found in the tactical layer that follows. It's the difference between owning a boat and knowing how to navigate a complex coastline. A fund without a robust strategy is merely an administrative shell. To turn that shell into a wealth-generating engine, you must move through a disciplined four-step process:
- Retirement modelling: Transforming static balances into dynamic, long-term cash flow projections that reflect your real-world needs.
- Research-driven construction: Building a bespoke portfolio that prioritises sustainability and logic over speculative market trends.
- Tactical tax-minimisation: Implementing legal structures that protect your capital from unnecessary leakage and inflation.
- Dynamic rebalancing: Ensuring your asset allocation remains aligned with your risk profile as global market conditions evolve.
Retirement Modelling: The True North Approach
Data provides the antidote to anxiety. Within the framework of comprehensive superannuation planning sydney, we use sophisticated projections to map out exactly how your capital will behave over twenty or thirty years. This process accounts for the harsh realities of 2026, including persistent inflation and the "sequence of returns" risk that can devastate a portfolio in the early years of a pension phase. Professional retirement planning Sydney requires this local expertise to ensure your lifestyle remains consistent regardless of market fluctuations. It's about building a fortress around your future, allowing you to step into retirement with quiet certainty.
Optimising Tax and Centrelink Outcomes
Efficiency is paramount. An SMSF provides a level of flexibility for tax-effective withdrawals that institutional funds simply cannot match. We often utilise re-contribution strategies to wash away the taxable component of your super, which can significantly reduce the potential death benefits tax for your beneficiaries. Simultaneously, we structure your assets to maximise any potential Centrelink entitlements. This ensures you aren't leaving valid support on the table while your private wealth continues to grow. This holistic view of wealth preservation ensures that every dollar is optimised for your benefit, protecting your family legacy for the long term.
If you're ready to see the numbers behind your vision, our specialised retirement modelling and long-term projections can provide the roadmap you need to move forward with confidence.
Achieving Retirement Clarity with Expert SMSF Guidance in Sydney
Partnership transforms the retirement experience. While many institutional funds act as distant providers, a true advisory partner serves as a Steady Navigator through the complexities of superannuation planning sydney. This distinction is vital for those who feel like a mere number in a large fund. A partner doesn't just manage assets; they understand the human outcome of every financial decision. For residents in the Sutherland Shire, having a Miranda-based team provides the proximity and local insight required to align your fund with the unique lifestyle goals of the region. It moves the conversation away from generic templates and toward a state of quiet certainty.
Taking the first step toward fund optimisation is about replacing order with chaos. Many professionals arrive at our doors with a sense of underlying anxiety regarding 2026 market volatility and a lack of transparency in their current retail funds. By conducting a thorough superannuation review, we identify the specific leakages and inefficiencies that may be hindering your progress. This process isn't about flashy innovation; it's about the rigorous testing of strategies to ensure they are grounded in real-world probability and evidence. It is a methodical journey from uncertainty toward a well-defined, structured path.
The Value of a Bespoke Portfolio
Logic drives longevity. A bespoke portfolio is constructed to reflect your unique risk tolerance and longevity requirements, moving beyond the "one size fits all" models of industry funds. At True North Lifestyle, our in-house Investment Committee provides the oversight necessary to protect your wealth, ensuring that every asset allocation is backed by research and disciplined methodology. We believe that superannuation advice Sutherland Shire must be about more than just numbers; it must be about the stability of your future lifestyle. By collaborating with Resonant Asset Management, we bring a level of technical depth and strategic construction that allows you to step into a role of confident oversight.
Your Next Steps Toward Confidence
Action creates clarity. If you're ready to explore whether an SMSF aligns with your vision, the process begins with a strategic consultation. During this session, we'll move beyond the setup phase to focus on bespoke retirement modelling and long-term projections. To prepare for this first meeting, it's helpful to gather your current superannuation statements and a clear outline of your desired retirement income. This data allows us to build a more accurate map of your financial future. If you're ready for the clarity that comes with professional guidance, you can book a consultation with our Miranda team to begin your journey toward a more secure and transparent retirement.
Charting Your Path to a Transparent Retirement
Deciding to take control of your superannuation is a profound step toward financial order. It replaces the inherent anxiety of being a number in an institutional fund with the quiet certainty of a structured, well-defined path. We've explored how a Self-Managed Super Fund provides the transparency required to navigate modern volatility, provided it's backed by a disciplined, research-driven methodology. Effective superannuation planning sydney isn't just about the initial setup; it's about the ongoing application of research-driven bespoke portfolios and specialised retirement modelling that projects your capital's longevity with precision.
Our local Sydney expertise in Miranda ensures that Sutherland Shire residents have a partner who understands their specific lifestyle goals. We don't just offer services; we provide a steady hand to help you protect your family legacy through every market cycle. By moving beyond generic templates, you empower yourself to make informed choices that align with your long-term vision for stability. If you're ready to replace uncertainty with a bespoke roadmap, our team is ready to assist. Secure your retirement clarity with bespoke SMSF advice from True North Lifestyle. Your future deserves the stability of expert oversight.
Frequently Asked Questions
Is an SMSF better than an industry superannuation fund?
Success depends on your specific asset balance and desired level of control. SMSFs offer fixed-cost administration and bespoke portfolio construction, whereas industry funds typically utilise percentage-based fees. For Sydney investors with higher balances, the SMSF structure often provides greater transparency and investment flexibility. However, industry funds offer simplicity and automatic insurance cover. The better choice is the one that aligns with your research-driven retirement modelling and long-term lifestyle goals.
How much do I need in my super to start an SMSF in 2026?
While there is no legislated minimum balance, ASIC guidance suggests that funds under A$200,000 often face higher relative costs. In the context of superannuation planning sydney, we generally see the most efficiency when combined member balances exceed A$400,000. This scale allows fixed costs, such as the A$259 annual supervisory levy and independent audit fees, to represent a smaller percentage of your total wealth compared to uncapped retail fund fees.
What are the main risks of running my own super fund?
The primary risks include personal liability for compliance breaches and the potential for inadequate diversification. As a trustee, you're legally responsible for the "Sole Purpose Test" and annual reporting. Failing to meet these duties can result in ATO penalties or the loss of concessional tax status. We mitigate these risks through rigorous portfolio sustainability modelling and ongoing strategic oversight, ensuring your fund remains a stable, complying vehicle for longevity.
Can I buy a residential investment property with my SMSF?
You can purchase residential property using cash, but new borrowing arrangements for residential assets were prohibited on 10 August 2026. Existing arrangements are fully grandfathered. Crucially, any residential property held in your fund must strictly follow the Sole Purpose Test. You cannot live in the property, and you cannot rent it to family members or related parties. Commercial "business real property" remains a more flexible strategic option for Sydney business owners.
What is the role of an SMSF specialist adviser?
A specialist adviser acts as your Steady Navigator, moving beyond simple administration to provide bespoke portfolio construction. We handle the technical depth of retirement modelling and tax-minimisation strategies, allowing you to step into a role of confident oversight. Our role is to simplify the complex regulatory environment of 2026, ensuring your investment strategy is research-driven and your wealth preservation plan is robust enough to protect your family legacy.
How much time does it take to manage an SMSF?
The time commitment varies depending on your level of professional support. While trustees have ultimate legal responsibility, a structured advisory partnership reduces the administrative burden significantly. You'll need to review your investment strategy annually and sign off on financial statements. Most Sydney professionals find that with expert guidance, the actual time required is minimal, allowing them to enjoy the benefits of control without the stress of daily management.
Can I use an SMSF to pay for my insurance premiums?
Yes, your fund can pay for Life, Total and Permanent Disability, and Income Protection insurance for its members. This is often a tax-effective way to manage premiums using pre-tax contributions. However, the policies must be structured correctly to ensure they are compliant and that any payouts can be legally released from the fund. We include risk management reviews as a core part of our superannuation planning sydney and optimisation process.
What happens to my SMSF if I move overseas?
Moving overseas can jeopardise your fund's status as a complying Australian superannuation fund. To maintain tax concessions, the fund must meet strict residency tests, including the central management and control test. If you become a non-resident for an extended period, you may need to appoint a local attorney or consider winding up the fund. It's a complex area that requires bespoke strategic planning to avoid severe tax consequences on your balance.


