

What if your retirement wasn't a series of guesses about market cycles and tax thresholds, but a structured sequence of outcomes you could actually see? For many Australians, the transition from accumulation to drawdown feels like stepping into a fog of legislative complexity and market noise. You've worked hard to build your nest egg, yet the fear of outliving your savings or being caught out by shifting superannuation rules remains a constant weight. Understanding the benefits of professional retirement planning is about more than just numbers; it's about replacing that underlying anxiety with a sense of calm and order. It's the difference between hoping your money lasts and knowing exactly how your lifestyle will be funded for the next thirty years.
We provide the professional retirement modelling and strategic advice required to turn your financial resources into a sustainable, long-term roadmap. In this guide, we'll explore how bespoke portfolio construction and wealth preservation strategies protect you from volatility. You'll discover how to minimise tax through the $32,500 concessional cap and optimise Centrelink entitlements to ensure your lifestyle remains uninterrupted. By the end, you'll have the clarity needed to step into your next chapter with quiet certainty and total confidence.
Key Takeaways
- Understand how the benefits of professional retirement planning extend beyond simple savings to include a comprehensive, research-driven navigation system for your future.
- Learn how detailed retirement modelling and cash flow projections can provide a clear, 30-year roadmap to ensure your desired lifestyle remains sustainable.
- Discover strategic superannuation techniques, such as re-contribution strategies, designed to minimise tax and optimise the eventual transfer of wealth to your beneficiaries.
- Identify critical threats to your longevity, including sequence of returns risk, and how bespoke portfolio construction acts as a buffer against market volatility.
- Transition from a state of financial anxiety to one of confident oversight, allowing for more transparent and informed discussions with your family regarding your financial future.
What is Professional Retirement Planning in the Australian Context?
Planning for the future. It's often mistaken for a simple tally of superannuation balances or a quick glance at an online calculator. However, the true benefits of professional retirement planning lie in the construction of a cohesive, evidence-based strategy that addresses the complex interplay of tax, legislation, and lifestyle goals. In 2026, the environment has become increasingly technical. With the Superannuation Guarantee rate now at 12% and the implementation of "Payday Super", the margin for error has narrowed. A generic calculator cannot account for the specific nuances of your family trust, your desired travel frequency, or the preservation of wealth for the next generation. We act as a Steady Navigator, filtering the noise of market volatility to provide a clear, structured path forward that a basic spreadsheet simply cannot replicate.
The Shift from Accumulation to Decumulation
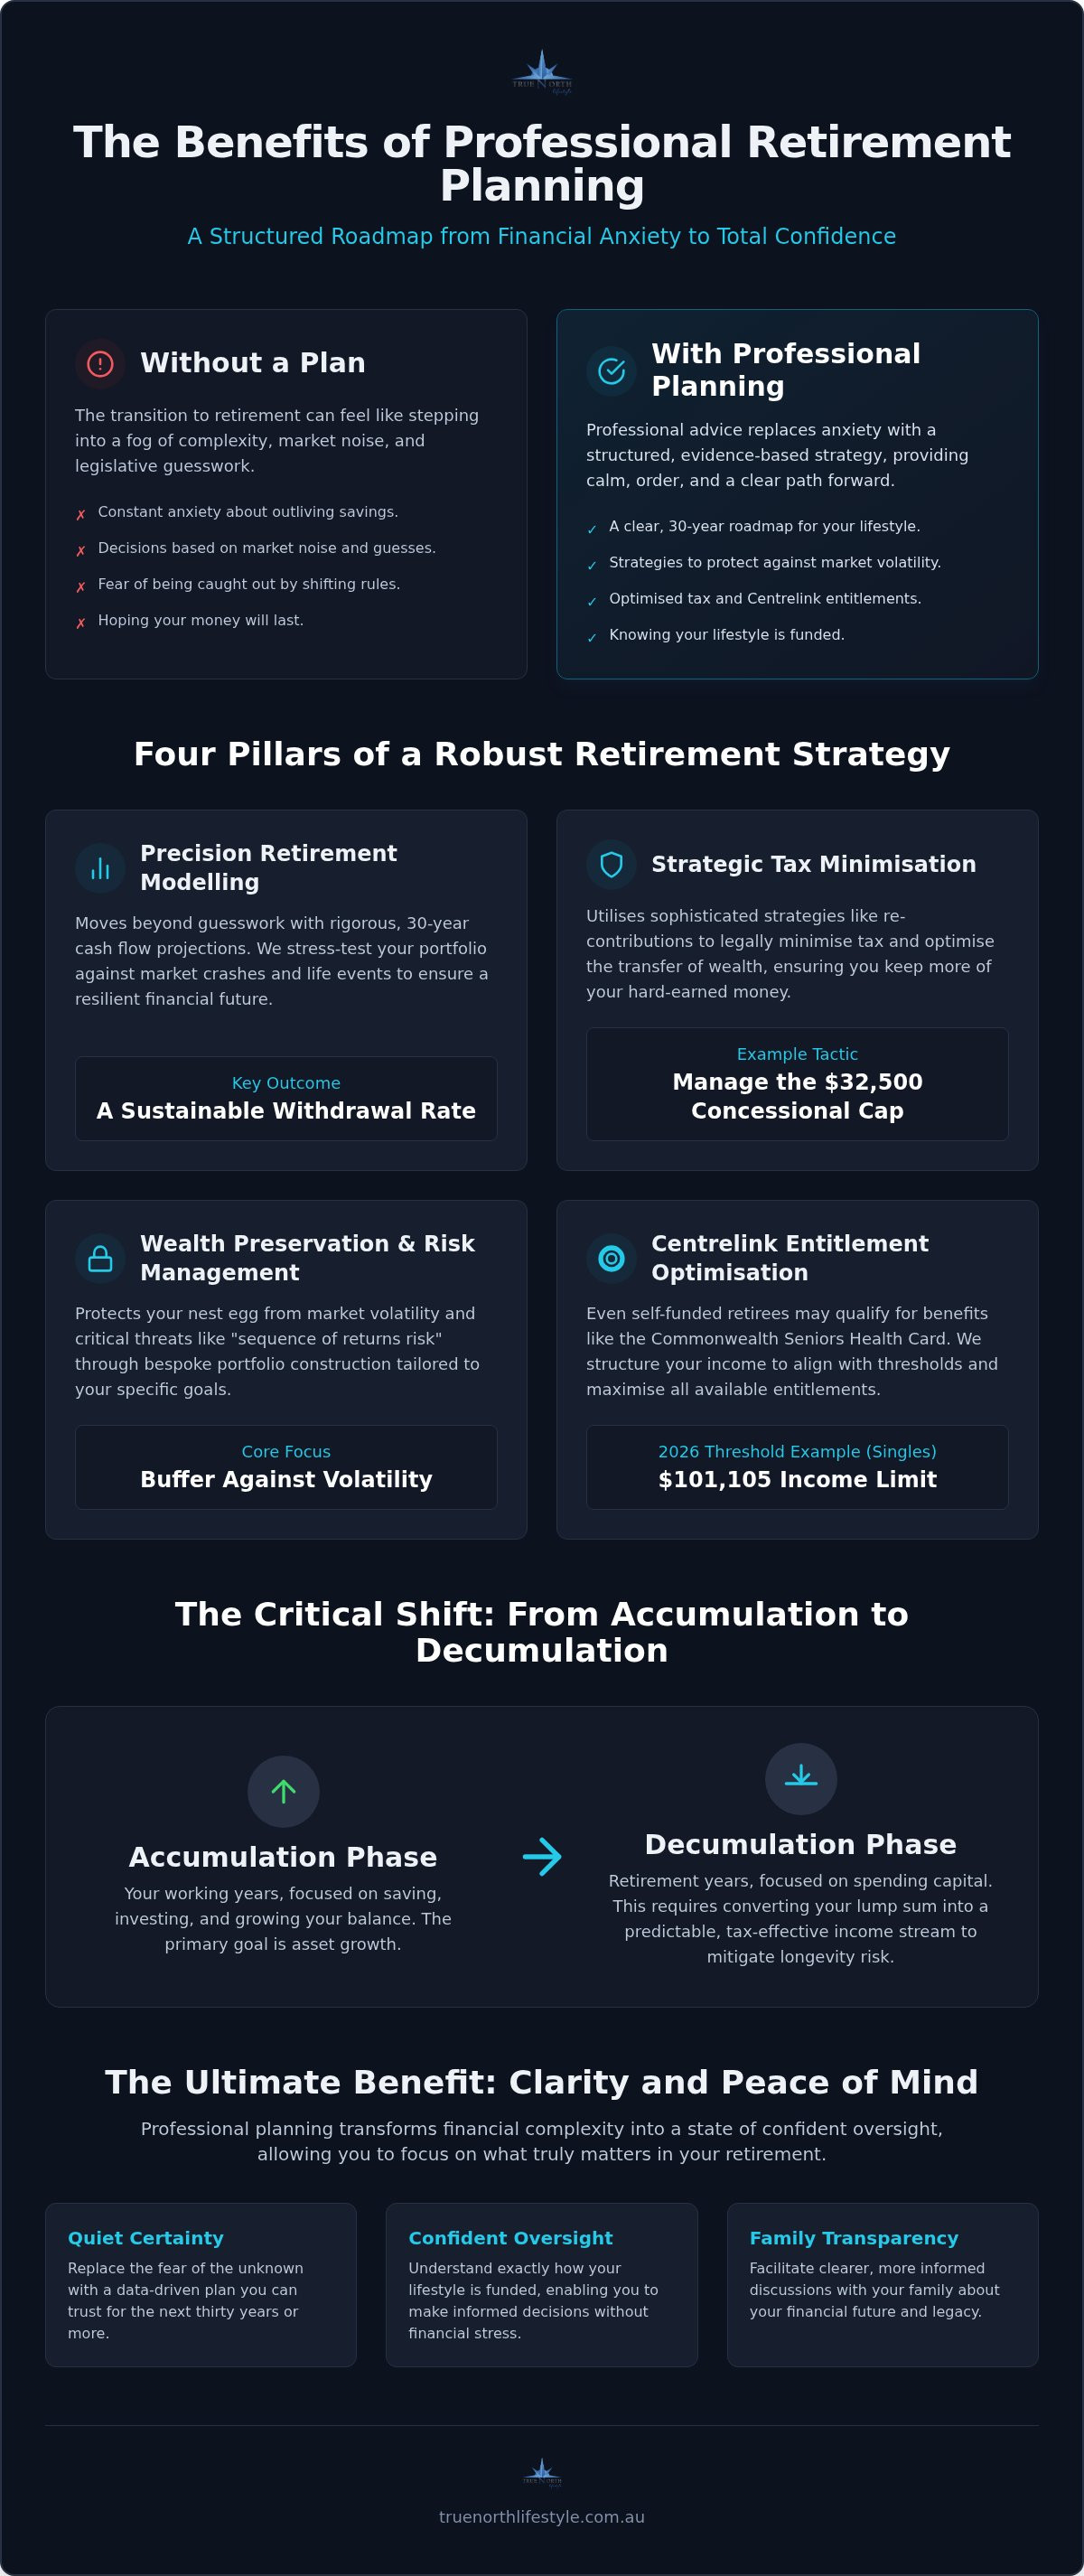
The psychology changes. For decades, you've been conditioned to save, watch the balance grow, and avoid withdrawals. Shifting into the decumulation phase, where you begin to spend that capital, often triggers significant financial anxiety. Professional planning manages this transition by converting your lump sum into a predictable, tax-effective income stream. This process is vital for mitigating longevity risk, which is the very real possibility of outliving your capital in an era where life expectancy for Australians continues to rise. By modelling various spending scenarios, we replace the fear of the unknown with a sense of confident oversight, ensuring your lifestyle remains sustainable for thirty years or more.
Managing the Australian Regulatory Landscape
Legislation never stands still. The framework surrounding Superannuation in Australia is subject to frequent adjustments, from shifting contribution caps to complex transfer balance limits. One of the core benefits of professional retirement planning is the ability to stay ahead of these shifts rather than reacting to them after the fact. Tax minimisation is not a one-off event but a continuous pillar of a professional plan. This involves sophisticated strategies like the re-contribution rule or seeking superannuation advice Sutherland Shire residents can rely on to optimise their tax position.
We also look beyond super to include the strategic integration of Centrelink entitlements. Even self-funded retirees may qualify for the Commonwealth Seniors Health Card if their income is structured correctly, providing substantial relief on healthcare costs. By aligning your portfolio with the current 2026 thresholds, such as the $101,105 income limit for singles, we ensure no opportunity for optimisation is missed. This methodical approach transforms a confusing array of rules into a well-defined path toward financial stability.
The Technical Benefit: Precision Retirement Modelling
Accuracy replaces hope. One of the most significant benefits of professional retirement planning is the transition from broad estimation to rigorous, research-driven calculation. While generic tools often provide a static snapshot, professional modelling employs sophisticated software to forecast thirty-year horizons based on real-world probability. This technical depth is a cornerstone of retirement planning Sydney professionals rely on to determine exactly how their assets will behave under different conditions. It moves the conversation from "I think we have enough" to "we know we have enough."
Scenario Planning for Life's Uncertainties
Markets are volatile. Life is unpredictable. Professional modelling doesn't just project a straight line of growth; it stress-tests your portfolio against historical market crashes and potential health crises. By simulating these "what-if" scenarios, we can identify your portfolio's breaking points before they occur. This allows for the construction of a sustainable withdrawal rate that accounts for inflation and sequence of returns risk. Ensuring your strategy remains resilient through shifting economic cycles is the primary goal of the Steady Navigator. It provides a protective layer of logic around your nest egg, allowing you to focus on your lifestyle rather than the daily movements of the ASX.
Visualising Your Financial Future
Seeing the path. There is a profound emotional relief in viewing a projected "wealth curve" that maps out your financial longevity. For many couples, this visualisation serves as a vital tool for alignment, helping both partners agree on future spending priorities and legacy goals. It removes the ambiguity of "how much is enough" by providing a data-backed answer tailored to your specific cost of living. By getting professional financial advice, you gain the clarity required to make informed decisions without the typical anxiety associated with large-scale financial change. This methodical approach ensures your roadmap is not just a plan, but a reliable navigation system.
If you are ready to see your own wealth curve, you can learn more about our bespoke retirement modelling services.
Strategic Superannuation and Tax Minimisation
Efficiency is paramount. One of the most impactful benefits of professional retirement planning is the ability to synchronise your superannuation structure with your broader tax obligations. For many, super is simply a bucket of money. For the strategist, it's a sophisticated vehicle that requires constant calibration. As we move through 2026, with the Superannuation Guarantee now at 12%, ensuring your contributions are working effectively is more critical than ever. Seeking superannuation advice Sutherland Shire residents trust allows for the implementation of bespoke portfolio construction that prioritises tax efficiency without sacrificing growth potential.
Optimising Your Superannuation Structure
Your choice of fund matters. Whether you utilise a Self-Managed Super Fund (SMSF), an industry fund, or a retail platform, the structure must align with your specific strategic needs. Regular reviews are essential to ensure your fund remains competitive and compliant with the latest legislative changes. For business owners, managing the 12% SG rate while balancing personal concessional contributions, now capped at $32,500, requires a methodical approach. According to the Australian government's Moneysmart website, professional advice helps you navigate these options to find the most cost-effective solution for your long-term goals. We provide the technical grounding to ensure your superannuation choice supports your retirement timeline rather than hindering it.
Minimising Tax on Retirement Income
Keep more of what you've earned. Effective tax planning for retirement Australia involves more than just filing a return; it's about structural optimisation. Once you reach age 60, most superannuation withdrawals become tax-free, but the strategy doesn't end there. We often employ a re-contribution strategy, which involves withdrawing funds and re-contributing them as non-concessional amounts. This effectively reduces the taxable component of your super, potentially saving your beneficiaries significant sums in future "death benefits tax". It's a quiet, powerful way to preserve wealth for the next generation.
Transition-to-retirement (TTR) strategies also offer a powerful way to bolster your savings while you're still working. By drawing a pension while simultaneously making concessional contributions, you can often lower your overall tax bill while maintaining your current lifestyle. Additionally, we look to reduce Capital Gains Tax (CGT) through strategic asset sales timed to coincide with your lower-income years in retirement. This level of technical depth ensures that every dollar is positioned for maximum longevity and preservation, turning a complex tax code into a strategic advantage.
Wealth Preservation and Risk Management
Wealth is fragile. Without a rigorous defensive framework, even a substantial nest egg can be eroded by economic forces beyond your control. One of the most critical benefits of professional retirement planning is the mitigation of risks that generic investment strategies often ignore. While accumulation was about growth, retirement is about stability and the disciplined preservation of what you've built. We act as your Steady Navigator, identifying potential threats to your capital before they manifest as financial setbacks.
Sequence of returns risk is perhaps the most significant technical threat you face. This describes the danger of a market downturn occurring in the very first years of your retirement, just as you begin to draw an income. Unlike the accumulation phase, where time allows for recovery, early losses during the decumulation phase can permanently shorten the lifespan of your savings. We address this by implementing sophisticated wealth preservation strategies that insulate your immediate income needs from short-term market volatility.
Purchasing power also requires constant protection. Inflation is a quiet thief that can diminish your standard of living over a thirty-year horizon if your portfolio is too defensive. A professional plan ensures your income keeps pace with the rising costs of healthcare, energy, and travel, ensuring your 2026 lifestyle remains sustainable well into the future. This balance between growth and protection is the hallmark of a well-constructed financial roadmap.
Bespoke Portfolio Construction
Off-the-shelf solutions don't work for retirees. A standard "balanced" fund often lacks the nuance required to manage specific tax positions or family legacy goals. Our in-house Investment Committee provides institutional-grade oversight, prioritising bespoke portfolio construction that focuses on low-volatility and income-focused assets. By tailoring the asset mix to your precise risk tolerance, we move away from speculative growth toward a more predictable, income-generating engine that supports your daily life.
Longevity and Sustainability Modelling
Longevity is the ultimate goal. We use rigorous modelling to ensure your capital lasts as long as you do, regardless of how the economic environment shifts. This involves balancing growth assets with defensive "cash buckets" to provide immediate liquidity during market shocks. By partitioning your wealth, we ensure you're never a forced seller of assets when prices are low. This methodical approach provides the quiet certainty you need to enjoy your retirement without the constant anxiety of market fluctuations.
If you are concerned about how market volatility might impact your transition, you can protect your retirement assets with a professional review today.
The Intangible Benefit: Clarity and Peace of Mind
Order replaces chaos. One of the most profound benefits of professional retirement planning is the psychological shift from persistent financial anxiety to a state of confident oversight. While the technical modelling provides the necessary logic, the true value is the emotional relief that comes from knowing your lifestyle is structurally protected. It allows you to stop worrying about the "what-ifs" of market cycles and start focusing on the experiences you've worked decades to afford. This sense of quiet certainty is the ultimate outcome of a well-navigated financial journey.
Family dynamics often change when money is no longer a source of ambiguity. Professional advice facilitates better discussions with adult children and spouses because the decisions are based on objective data rather than guesswork. When you can show your family a projected wealth curve, it removes the tension often associated with inheritance and future care needs. Having a local Miranda-based partner provides an additional layer of comfort; you have a Steady Navigator nearby who understands the Sutherland Shire lifestyle and is available for face-to-face support as your circumstances evolve.
Estate Planning and Legacy Management
Wealth requires protection even after you've finished using it. The intersection of retirement planning and sophisticated wealth transfer strategies Australia ensures that your assets are distributed according to your wishes, not the tax office's default rules. This involves more than just a simple will. We look at the role of testamentary trusts and how they can protect beneficiaries from unnecessary tax burdens or external risks. By organising your estate strategy now, you ensure your legacy is preserved and your family is provided for with minimal administrative friction.
Your Next Steps Toward a Calm Retirement
Timing is everything. We generally recommend starting the formal planning process at least five to ten years before your intended retirement date. This window allows for the implementation of multi-year strategies, such as catch-up concessional contributions or structural asset realignments, which simply aren't possible in the final months of work. When you meet with a Sydney financial adviser for an initial consultation, you should expect a deep dive into your personal values and a rigorous assessment of your current trajectory.
Clarity is within reach. By engaging in professional modelling today, you replace uncertainty with a structured roadmap for the next thirty years. We invite you to step into a role of informed oversight, where every financial decision is a deliberate move toward a sustainable and fulfilling future. The path to a calm retirement begins with a single, evidence-based plan.
Secure Your Financial Longevity Today
The journey toward a sustainable retirement is defined by the quality of your roadmap. By moving beyond generic calculators and embracing specialist retirement modelling expertise, you replace financial ambiguity with a structured, 30-year projection. One of the primary benefits of professional retirement planning is the ability to synchronise bespoke investment portfolio construction with rigorous tax-minimisation strategies, ensuring your capital is protected from market volatility and legislative shifts. Whether you are navigating the 2026 superannuation guarantee rate or managing sequence of returns risk, professional oversight provides the quiet certainty you deserve.
With offices located in Miranda and the Sydney CBD, our team acts as your Steady Navigator through every stage of the decumulation phase. We invite you to achieve clarity and confidence in your future—book a consultation with True North Lifestyle today. Your next chapter should be defined by lifestyle outcomes rather than financial anxiety. You've done the hard work; now it's time to ensure your legacy remains secure and your lifestyle remains sustainable for decades to come.
Frequently Asked Questions
Is it worth paying for a retirement plan if I only have a modest super balance?
Understanding the benefits of professional retirement planning is often more critical for modest balances because there's less room for error. Strategic advice helps you stretch your funds further by optimising tax and ensuring you qualify for the maximum possible government support. It's about efficiency rather than just the total sum. We focus on making every dollar work harder through disciplined modelling, helping you avoid common pitfalls that erode smaller nest eggs.
How often should I review my retirement strategy with a professional?
You should generally review your retirement strategy annually to ensure it remains aligned with your goals. However, significant life events or legislative shifts, like the 2026 superannuation guarantee increase to 12%, may require an immediate consultation. Regular oversight allows us to adjust your bespoke portfolio based on real-world market performance. This proactive approach ensures your navigation system remains accurate, preventing small deviations from becoming major financial shortfalls over a thirty-year horizon.
Can a financial adviser help me maximise my Centrelink Age Pension?
Yes, a financial adviser can assist with Centrelink structuring to help you qualify for the Age Pension or the Commonwealth Seniors Health Card. By organising your assets and income streams effectively, we can often improve your eligibility under the current 2026 thresholds. This is a key part of the benefits of professional retirement planning, ensuring you receive the full range of entitlements you've earned throughout your working life in Australia.
What is the difference between a generic retirement calculator and professional modelling?
Generic calculators provide a static, linear projection that often ignores market volatility and complex Australian tax laws. In contrast, professional modelling uses research-driven data to stress-test your portfolio against thousands of potential market scenarios. We look at your specific costs, family trusts, and legacy goals to create a dynamic roadmap. This technical rigour provides a level of clarity and certainty that a simple online tool, which lacks bespoke data, cannot offer.
How does professional planning help with the rising cost of living in Sydney?
Professional planning addresses the high cost of living in Sydney by building inflation protection directly into your wealth preservation strategy. We model your future spending power against rising local costs for healthcare, energy, and council rates. By maintaining a balance between growth assets and defensive cash buckets, we ensure your income remains sustainable. This structured approach provides peace of mind for residents in Miranda and the Sydney CBD, knowing their lifestyle is protected.
Do I need a different strategy if I am a business owner in the Sutherland Shire?
Business owners in the Sutherland Shire require a specialised approach that accounts for the sale of business assets and complex CGT concessions. You must also manage your obligations regarding the 12% Superannuation Guarantee for your staff while optimising your own contributions. We help you transition from business equity to a diversified retirement income stream. This involves bespoke portfolio construction that considers your unique tax position, ensuring the value you've built is preserved.
What is 'longevity risk' and why should I be worried about it?
Longevity risk is the high probability that you will outlive your financial resources. It's a significant concern in Australia, where life expectancies continue to climb. Professional planning mitigates this by using conservative withdrawal rates and sustainable modelling to ensure your capital lasts thirty years or more. We focus on wealth preservation and low-volatility strategies to protect your purchasing power. Understanding this risk is vital for maintaining a confident oversight of your future.
How does bespoke portfolio construction differ from a standard industry fund?
Bespoke portfolio construction offers a tailored investment mix designed for your specific risk tolerance and tax requirements. Unlike a standard industry fund, which uses a "one size fits all" approach for millions of members, a bespoke portfolio is managed by an in-house Investment Committee. This allows for precise control over asset allocation and income generation. It's a more sophisticated way to manage volatility, ensuring your investments are directly aligned with your personal retirement roadmap.


