

What if your retirement fund was no longer a black box of generic industry performance, but a transparent vehicle that moves in sync with your specific lifestyle? For many residents, seeking professional SMSF advice Sutherland Shire is the decisive moment they stop being passive spectators of their financial future. It's understandable to feel a sense of disconnect when your hard-earned wealth is managed in a fund that doesn't reflect your personal values or investment preferences.
You likely recognise that the 2026 regulatory landscape, including the new Division 296 tax on balances over A$3 million, demands a more sophisticated approach to compliance. We promise to show you how to establish a Self-Managed Super Fund with absolute clarity, ensuring your retirement strategy is as bespoke as your life in the Shire. This guide explores the essential steps of SMSF establishment, moving from initial retirement modelling to the long-term wealth preservation strategies managed right here in Miranda. By the end, you'll understand how to secure total control over your investment choices while maintaining a rigorous, compliant structure that protects your legacy.
Key Takeaways
- Understand why Sutherland Shire investors are moving away from generic industry funds in favour of the bespoke control offered by a private, ATO-regulated SMSF.
- Clarify your dual responsibilities as both a member and a trustee, ensuring your fund’s Trust Deed serves as a robust rule book for long-term compliance.
- Learn how to craft a compliant written investment strategy that meets 2026 ATO standards through professional SMSF advice Sutherland Shire.
- Follow a structured roadmap from your initial Miranda-based consultation through to the technical activation of your individual or corporate trust.
- Discover the value of local expertise in navigating complex regulatory shifts, such as Division 296, while maintaining a focus on wealth preservation.
Understanding the Shift: Why Sutherland Shire Investors Are Choosing SMSFs
Control defines the shift. For many residents, the traditional Australian superannuation system feels like a distant mechanism, operating with little regard for individual aspirations or local market opportunities. An SMSF is a private super fund regulated by the Australian Taxation Office (ATO) where the members also act as the trustees. This structure fundamentally changes the relationship between you and your wealth. Instead of accepting the one-size-fits-all portfolio of a retail fund, you step into a role of active oversight. Choosing to seek professional SMSF advice Sutherland Shire is often the first step toward aligning your financial structures with your specific lifestyle goals.
The driver is rarely just about the numbers; it's about transparency. Investors are moving away from the "black box" nature of industry funds to gain a clearer view of where their money is held and how it's being utilised. This transition replaces the inherent anxiety of fluctuating markets with a sense of order. By taking the lead, you ensure that your retirement strategy isn't just a generic projection, but a bespoke plan that accounts for your family's unique requirements and long-term wealth preservation.
The Allure of Control: SMSF vs Industry Funds
Specific assets matter. While industry funds offer limited "member choice" menus, an SMSF allows for the inclusion of direct residential or commercial property, unlisted assets, and bespoke share portfolios. This flexibility is particularly valuable for Shire business owners who may wish to hold their commercial premises within their fund. The transparency extends to your protection; you have the ability to tailor insurance policies within the fund to suit your actual needs rather than accepting group-life defaults. It's about precision and the elimination of wasted costs. Throughout this process, the Sole Purpose Test remains the foundational rule, requiring that all fund activities are conducted for the singular purpose of providing retirement benefits to members.
Is Your Balance Ready? The Cost-Effectiveness Threshold in 2026
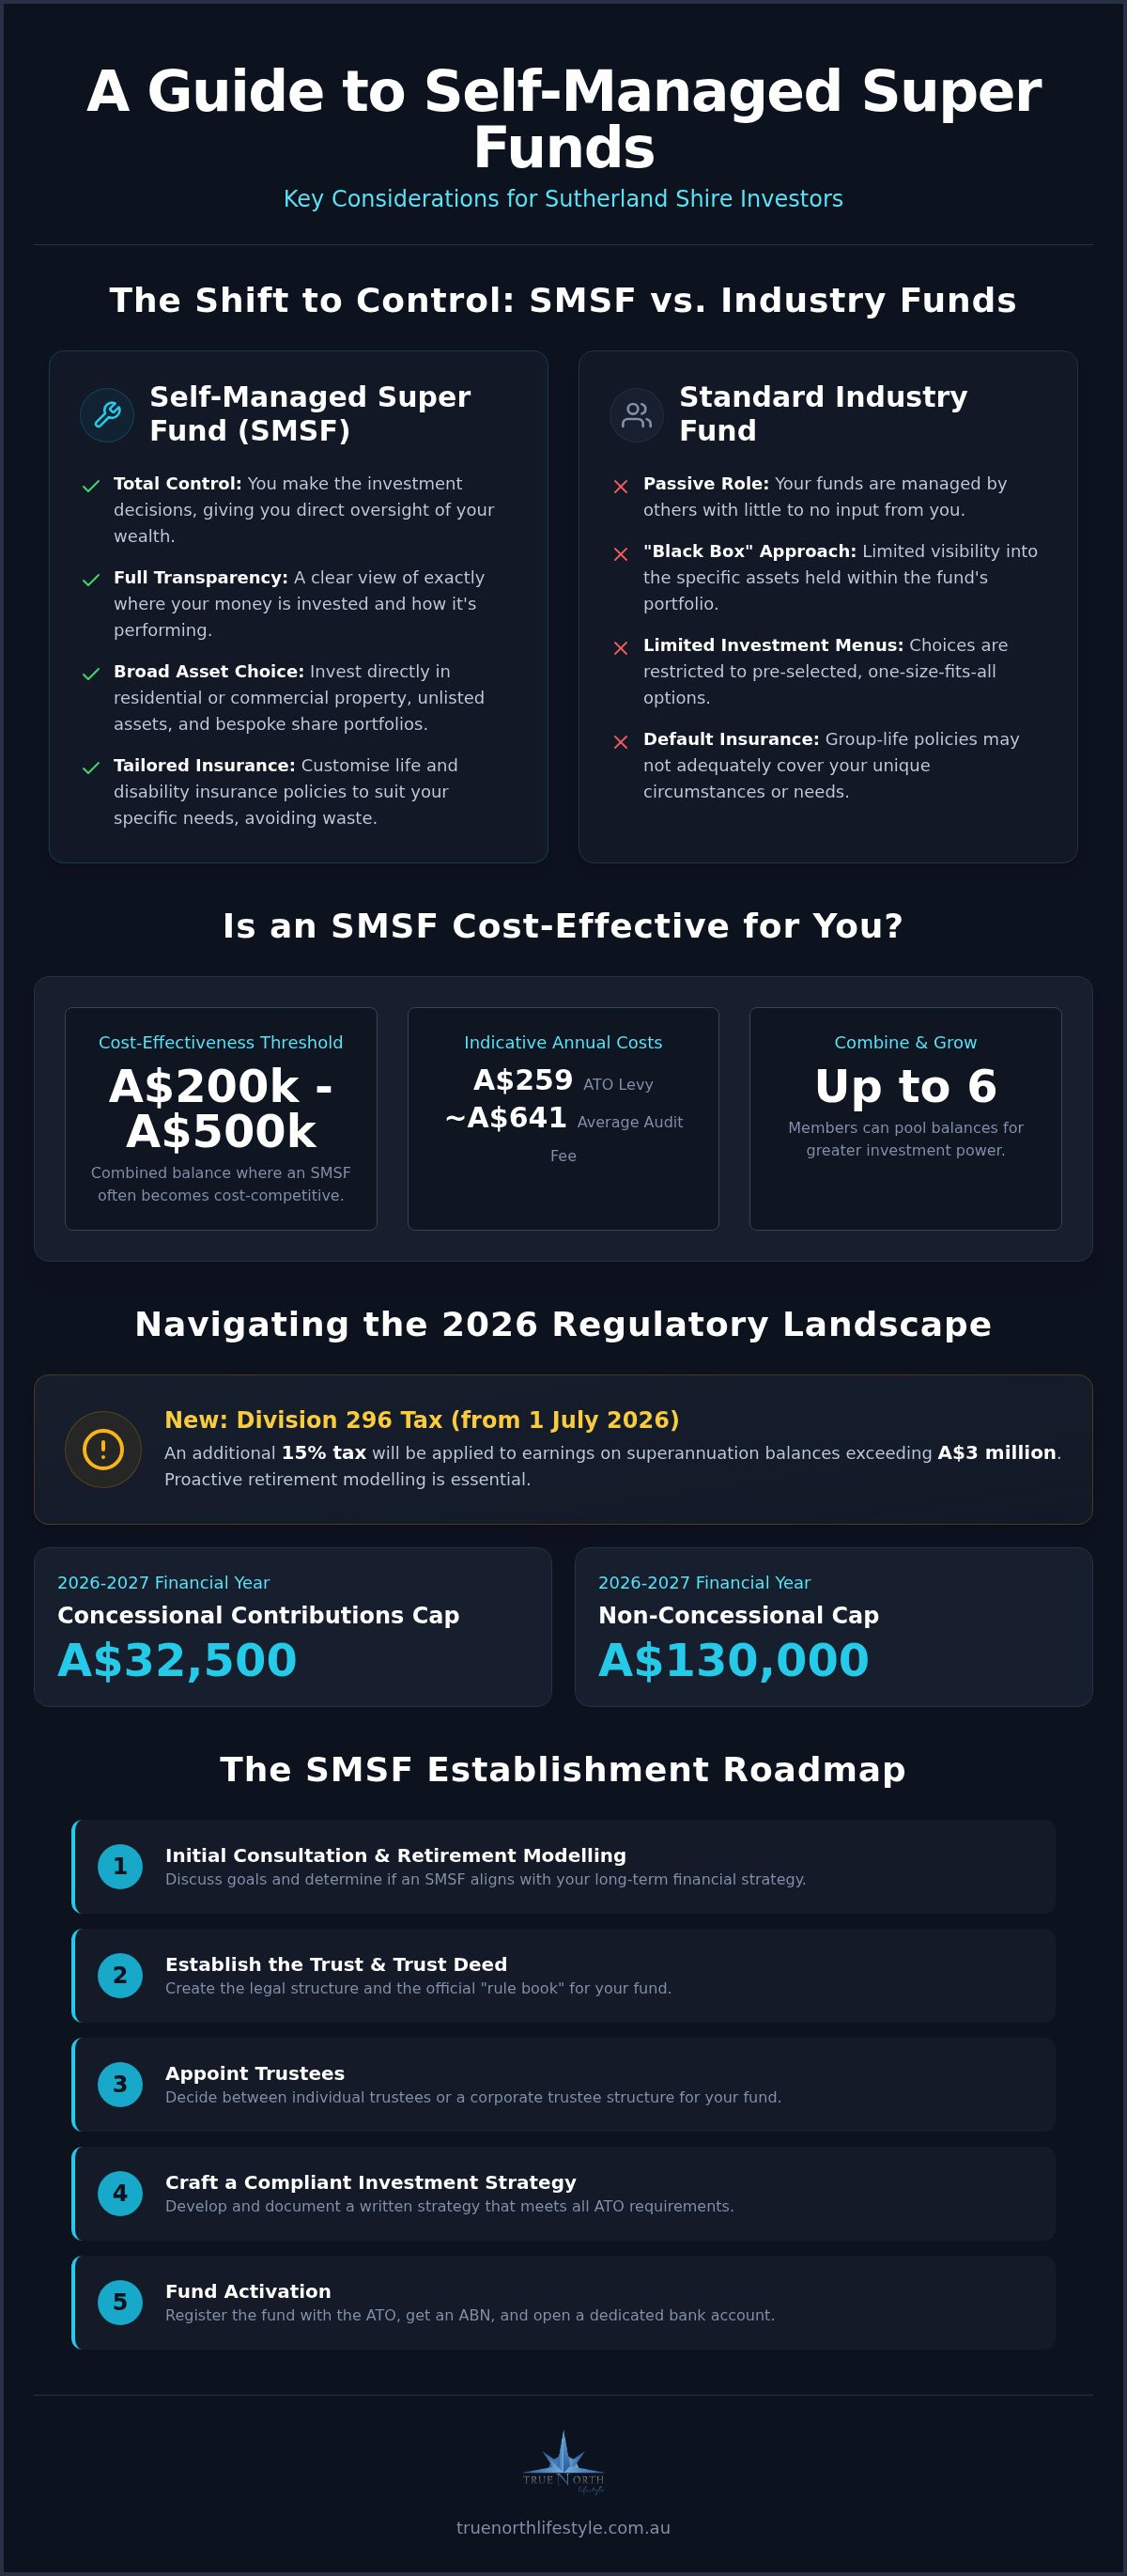
Scale creates value. Operating an SMSF involves fixed costs that must be weighed against the potential benefits of control. These include the annual ATO supervisory levy of A$259 and independent audit fees, which recently averaged approximately A$641 across the industry. To justify these expenses, a combined balance between A$200,000 and A$500,000 is often cited by experts as the threshold where the fund becomes cost-competitive with high-end industry alternatives.
For Miranda families, combining the balances of up to six members often makes an SMSF a viable strategic choice. This pooling of resources allows for more sophisticated retirement modelling and provides the capital necessary for direct property investment. It's a move toward efficiency. When you reach this tipping point, the shift from a passive member to an active trustee allows for a more rigorous approach to risk management and portfolio sustainability. Professional SMSF advice Sutherland Shire ensures that this transition is handled with the technical depth required to maintain compliance while seeking to optimise your long-term outcomes.
The Legal Framework: Essential Compliance for Your Sutherland Shire SMSF
Compliance provides the framework for freedom. While the primary driver for an SMSF is often investment control, that control is governed by a rigorous set of legal obligations that require disciplined attention. As a member, you enjoy the benefits of the fund; as a trustee, you are personally liable for its adherence to the law. Understanding the key responsibilities of an SMSF trustee is critical because the ATO does not distinguish between an honest mistake and a deliberate breach. Professional SMSF advice Sutherland Shire ensures that your fund remains a vehicle for growth rather than a source of regulatory anxiety.
The 2026 regulatory environment has introduced specific shifts that demand updated strategies. For the 2026-2027 financial year, the concessional contributions cap has increased to A$32,500, while the non-concessional cap has risen to A$130,000. Furthermore, the commencement of the Division 296 tax on July 1, 2026, which applies an additional 15% tax on earnings for balances exceeding A$3 million, makes precise retirement modelling more essential than ever. Maintaining a complying status requires a Trust Deed that serves as a robust rule book, clearly outlining how the fund operates, pays benefits, and handles member transitions.
Appointment of Trustees and the Trust Deed
Stability through structure. When establishing your fund, the choice between individual trustees and a corporate trustee structure is a pivotal decision for long-term wealth preservation. Individual trustee arrangements require each member to be a trustee, which can lead to administrative complexity if a member joins or leaves the fund. In contrast, a corporate trustee structure involves a dedicated company acting as the trustee. This is often preferred for its permanence; it simplifies estate planning and ensures that the fund's assets remain clearly separated from personal holdings. A professionally drafted Trust Deed should be bespoke, allowing for the specific types of Shire-centric investments, such as local commercial property, that a generic template might restrict.
ATO Obligations and the SMSF Audit Process
Rigorous verification. The annual audit is not a mere formality; it is a critical safeguard for your fund's complying status. Every fund must appoint an approved SMSF auditor at least 45 days before the annual return is due. For self-lodgers, the annual return is typically due by February 28 following the end of the financial year. The auditor's role is to verify both the financial statements and the fund's compliance with superannuation laws, including the Sole Purpose Test and in-house asset rules. To simplify this process, many Miranda families utilise digital document vaults provided by their advisers. These portals allow for the seamless collection of bank statements, property valuations, and minutes of meetings throughout the year, ensuring that the audit process is orderly and efficient.
Strategy First: Crafting a Bespoke Investment Strategy for 2026
Design dictates outcome. In the eyes of the regulator, an investment strategy is not a static document to be filed and forgotten, but a living blueprint that must be reviewed at least annually. The Australian Taxation Office requires every trustee to formulate a written strategy that specifically addresses risk, return, diversification, and liquidity. Seeking professional SMSF advice Sutherland Shire allows you to move beyond basic compliance and into the realm of bespoke investment advice Sydney, where your portfolio is constructed to mirror your specific lifestyle requirements. This process ensures that every asset held within the fund serves a logical purpose in your broader retirement journey.
Liquidity remains a critical, often overlooked component of fund management. As you approach the pension phase, your fund must maintain sufficient cash flow to pay member benefits and meet ongoing expenses without being forced to sell illiquid assets at an inopportune time. A well-constructed strategy balances the desire for growth with the absolute necessity of meeting these obligations. By focusing on wealth preservation, especially for those in the pre-retirement phase, we replace the anxiety of market volatility with a structured, research-driven path toward financial longevity. Adhering to the SMSF investment rules is the baseline; the goal is to build a portfolio that thrives within those boundaries.
Diversification Beyond Residential Property
Concentration creates vulnerability. Many investors in the Sutherland Shire naturally gravitate toward residential property, yet being "property heavy" in a single geographic market carries significant risks. If the local market softens, your entire retirement nest egg may be impacted simultaneously. To counter this, we prioritise the construction of low-volatility portfolios that include a mix of income-focused assets and global equities. True North Lifestyle utilises sophisticated modelling to test portfolio sustainability against various economic scenarios. This evidence-based approach allows you to understand how your fund might perform during periods of stress, ensuring your strategy remains robust regardless of local property cycles.
Integrating Longevity and Sequence of Returns Risk
Timing is everything. Sequence of returns risk refers to the danger of receiving low or negative returns just as you begin withdrawing funds in retirement. When you're in this "retirement red zone," a significant market downturn can disproportionately deplete your capital, as you're forced to sell assets while prices are low. A bespoke strategy seeks to mitigate this by implementing specific wealth preservation strategies designed to protect your core capital. By building "buckets" of liquidity and defensive assets, we ensure that your lifestyle remains funded even when markets are fluctuating. This methodical approach provides the quiet certainty needed to transition from the workforce with confidence, knowing your financial future is anchored by a disciplined, risk-aware framework.
The Setup Roadmap: From Miranda Consultation to Fund Activation
Clarity brings confidence. The journey from a retail fund to a self-managed structure requires a methodical progression through several technical milestones. By following a structured roadmap, you replace the inherent complexity of establishment with a clear, sequential path. When you partner with us for SMSF advice Sutherland Shire, we handle the heavy lifting of the administration, allowing you to step into a role of informed oversight without feeling overwhelmed. This process ensures that your fund is built on a compliant foundation from day one.
The establishment process follows five critical stages:
- Initial Consultation: We begin at our Miranda office with a comprehensive superannuation review and retirement modelling session to confirm that an SMSF aligns with your lifestyle aspirations.
- Trust Establishment: This involves the formal drafting of your Trust Deed and the appointment of either individual or corporate trustees to govern the fund.
- Registration: We manage the application for your fund’s Australian Business Number (ABN) and Tax File Number (TFN) through the Australian Business Register.
- Structural Foundations: This stage includes opening a dedicated fund bank account and setting up an Electronic Service Address (ESA) for SuperStream compliance.
- Fund Activation: The final step involves rolling over your existing super benefits from your industry or retail funds into your new SMSF.
Rolling Over Existing Super Benefits
Wealth migration requires care. The process of initiating a rollover via the ATO’s SuperTick system is highly regulated to ensure the security of your retirement savings. A critical consideration during this phase is the potential loss of existing insurance cover; closing an old fund without first securing equivalent or superior cover within your SMSF can leave your family's financial future vulnerable. We manage this transition meticulously to avoid unnecessary tax triggers and ensure your wealth preservation strategy remains uninterrupted during the move. To begin your journey with a structured, compliant setup, schedule your initial retirement modelling session with our Miranda-based team.
Setting Up Bank Accounts and ESA Details
Separation is mandatory. Your SMSF bank account must be entirely distinct from your personal or business finances to satisfy the ATO’s strict "arm's length" requirements. Furthermore, an Electronic Service Address (ESA) is essential for receiving employer contributions and digital data under the SuperStream system. Local Miranda professionals ensure these technical components are integrated with sophisticated reporting software from the outset. This digital integration provides real-time visibility over your fund's cash flow, making the annual audit process significantly more efficient and transparent for all trustees.
Navigating the Future: Why Local Sutherland Shire Expertise Matters
Precision requires proximity. While digital platforms offer transactional efficiency, they often lack the emotional depth and strategic nuance required for complex wealth preservation. Choosing local SMSF advice Sutherland Shire means having a Steady Navigator who understands the specific economic pulse of the Shire and how it interacts with your personal journey. This face-to-face superannuation advice Sutherland Shire replaces the cold, corporate distance of national providers with a partnership grounded in trust and local accountability. It's about moving from a state of constant financial noise to a place of quiet certainty.
Our Miranda-based team provides the logical grounding needed to manage the complexities of the 2026 regulatory environment. We don't just set up a fund; we architect a lifestyle vehicle. By combining technical authority with a supportive, empathetic stance, we ensure that you remain empowered to make informed choices. This synergy between local knowledge and sophisticated investment research creates a stabilizing force for your retirement, allowing you to focus on the human outcomes of your financial success rather than just the numbers.
True North Lifestyle’s Bespoke Portfolio Construction
Institutional-grade research meets local design. Through our collaboration with Resonant Asset Management, we provide our clients with access to research-driven portfolios that were once the exclusive domain of large institutional investors. This partnership allows for the construction of portfolios that are specifically tailored to the income needs and risk tolerances of Shire retirees. We adopt a no-nonsense approach to value. Every asset is selected based on its ability to provide stability and long-term growth, with a clear focus on low volatility. This transparency ensures you understand exactly what you own and why you own it, eliminating the ambiguity often found in generic retail fund portfolios.
Ongoing Management and Strategic Re-modelling
Setup is just the beginning. The strength of an SMSF lies in its ability to adapt as your life evolves. Annual strategic reviews are essential to ensure your fund remains aligned with shifting tax laws and your personal goals. As you transition into the pension phase, your retirement planning Sydney must become more granular, focusing on sustainable income streams and tax-minimisation. We integrate estate planning directly into your SMSF structure, ensuring that wealth transfer to the next generation is seamless and protected. This disciplined, ongoing oversight provides the structural integrity needed to protect your legacy, ensuring your fund remains a reliable anchor in a fluctuating financial environment.
Securing Your Financial Legacy in the Sutherland Shire
Control is the ultimate outcome of a well-structured SMSF. By moving from a passive spectator to an active trustee, you ensure your superannuation reflects your specific lifestyle and wealth preservation goals. This guide has outlined the transition from initial retirement modelling in Miranda to the technical activation of your fund. You now understand that a compliant setup depends on a robust Trust Deed and a research-driven investment strategy constructed with institutional-grade oversight. Our collaboration with Resonant Asset Management ensures your portfolio is built on evidence rather than speculation, providing the stability required for long-term success.
Establishing your fund is a significant evolution toward active lifestyle design. You don't have to manage the complexities of 2026 regulatory shifts alone. If you're ready to align your superannuation with your personal aspirations, the next step is a professional review of your current position. We invite you to Book a Strategic SMSF Consultation in Miranda to explore how professional SMSF advice Sutherland Shire can anchor your financial future. You've done the hard work of building your wealth; it's time to ensure it's managed with the precision and quiet certainty you deserve.
Frequently Asked Questions
How much does it cost to set up an SMSF in the Sutherland Shire?
Setup costs typically include ATO registration fees and professional advisory charges. In 2026, the ATO supervisory levy is A$259, while independent audit fees often average around A$641. For residents in Miranda, these fixed costs should be weighed against the benefits of bespoke portfolio construction. It's essential to understand that while there are initial establishment fees, the long-term value lies in the strategic control you gain over your retirement outcomes.
Can I use my SMSF to buy a residential investment property in Cronulla?
Yes, you can purchase residential property in Cronulla, provided the transaction satisfies the Sole Purpose Test and the arm's length rule. This means neither you nor any related party can live in the property or rent it. The investment must be maintained strictly to provide retirement benefits for members. Professional SMSF advice Sutherland Shire ensures that your property acquisition is structured correctly to avoid severe ATO penalties while diversifying your fund's asset base.
Is an SMSF better than an industry super fund for retirement?
The choice depends entirely on your desire for oversight and the complexity of your retirement modelling. Industry funds offer simplicity and lower administrative effort, but they lack the bespoke investment flexibility of an SMSF. A self-managed fund allows you to invest in direct property and unlisted assets, which many Shire investors prefer for transparency. If you value total control over your investment choices and wealth preservation strategies, an SMSF often provides a superior, tailored alternative.
What are the minimum balance requirements for an SMSF in 2026?
There is no legal minimum balance, but cost-effectiveness is a critical consideration for Miranda families. Industry consensus in 2026 suggests that a combined balance of at least A$200,000 to A$500,000 is generally required to justify the annual audit and accounting expenses. Below this threshold, the fixed costs may erode your returns more than a high-performing industry fund. We recommend comprehensive retirement modelling to determine if your specific balance supports a sustainable fund structure.
How much time do I need to spend managing my SMSF each week?
The time commitment varies based on your investment strategy and the level of professional support you engage. While you are legally responsible for all decisions as a trustee, local advisers in Miranda handle the heavy lifting of compliance and reporting. Most trustees spend a few hours each month reviewing performance and meeting with their investment committee. Utilising integrated reporting software significantly reduces the administrative burden, allowing you to focus on high-level oversight rather than manual data entry.
Can I include my partner or children in my Sutherland Shire SMSF?
You can include up to six members in your fund, which often makes it a powerful vehicle for family wealth preservation. Including partners or adult children allows you to pool balances, potentially reaching the cost-effectiveness threshold sooner and enabling larger investments like commercial property. This multi-member structure requires a professionally drafted Trust Deed to ensure clear estate planning and benefit distribution. It's a strategic way for Shire families to manage intergenerational wealth within a single, compliant entity.
What happens if my SMSF is found to be non-compliant by the ATO?
Non-compliance can lead to severe financial consequences, including the fund being taxed at the highest marginal rate. The ATO also has the power to issue administrative penalties; as of July 2026, a single penalty unit is A$330. In the 2023-24 period, over 22,000 auditor contravention reports were lodged, highlighting the regulator's increased scrutiny. Seeking ongoing SMSF advice Sutherland Shire is the most effective way to navigate these risks and maintain your fund's complying status.
Do I need a financial adviser to set up an SMSF in Miranda?
While you aren't legally required to use an adviser, the complexity of 2026 regulations makes professional guidance a prudent choice. An expert provides the technical depth needed for establishment, from drafting the Trust Deed to initial retirement modelling. In Miranda, our role is to act as your Steady Navigator, ensuring your fund is not just a tax structure but a bespoke investment vehicle. This partnership replaces the anxiety of self-management with the quiet certainty of a compliant, research-driven strategy.


