

Could a three-year gap in your retirement dates be the silent anchor dragging down your shared lifestyle in the Sutherland Shire? While you have spent decades building individual careers and superannuation balances, the transition into retirement requires a fundamental shift from "mine" to "ours." It is natural to feel a sense of unease when faced with the complexity of managing separate accounts for a joint lifestyle. You likely worry about whether your combined resources can sustain your current standard of living in Miranda once the regular paycheques stop.
Effective retirement planning for couples Miranda focuses on more than just the balance sheet; it's about synchronising two distinct financial trajectories into a single, stress-tested model. Discover how to align your superannuation, tax strategies, and lifestyle goals to create a seamless retirement transition. We will examine the specific modelling and wealth preservation strategies used to optimise your joint position, ensuring your financial future is as unified as your retirement dreams.
Key Takeaways
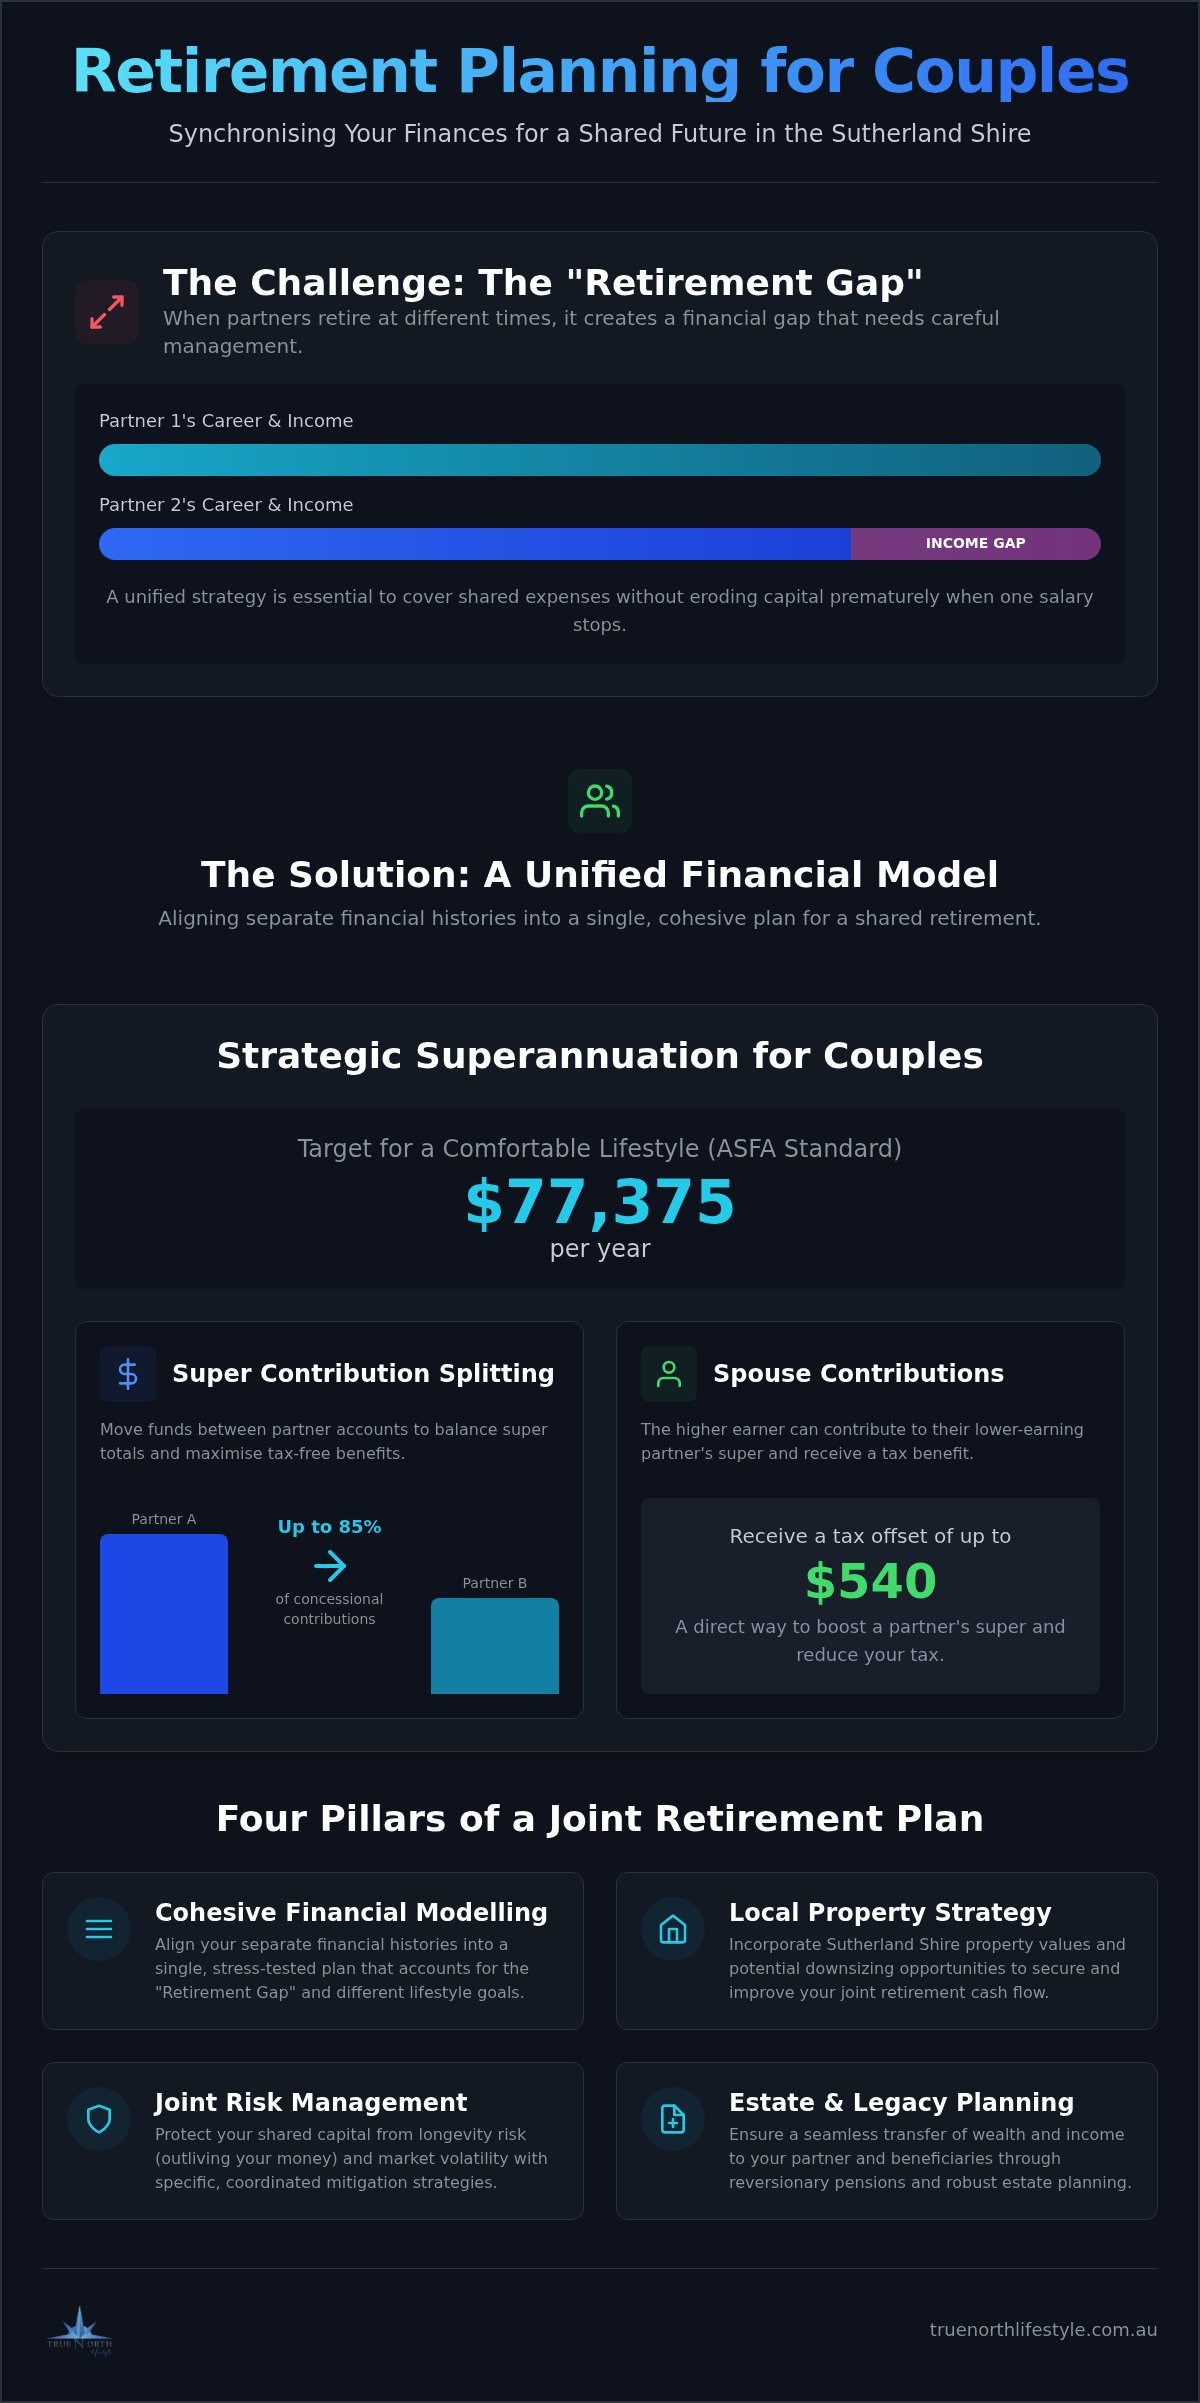
- Align your separate financial histories into a single, cohesive model that manages the "retirement gap" when partners finish work at different times.
- Optimise your combined tax-free thresholds by using superannuation contribution splitting to balance account sizes and maximise long-term income.
- Discover how retirement planning for couples Miranda incorporates local property values and downsizing opportunities to secure your joint cash flow.
- Protect your shared capital from longevity risk and market volatility by implementing specific risk-mitigation strategies in the early years of your transition.
- Ensure a seamless transfer of wealth and income through the strategic use of reversionary pensions and robust estate planning structures.
The Unique Challenges of Retirement Planning for Couples
Shared lives often hide separate ledgers. For many residents in the Sutherland Shire, Retirement planning has historically been an individual pursuit, focused on personal superannuation balances and specific career trajectories. However, successful retirement planning for couples Miranda requires a fundamental shift in perspective. It is the deliberate alignment of two distinct financial histories into a single, cohesive future. This process moves beyond simple arithmetic; it involves reconciling different risk appetites, varying retirement dates, and potentially conflicting visions for life after work.
The "Retirement Gap" is a frequent hurdle. When one partner stops working years before the other, the household dynamic shifts instantly. This transition period demands precise cash flow modelling to ensure the remaining income covers shared expenses without prematurely eroding the retiring partner's capital. In Miranda, where lifestyle expectations often include enjoying the local coastal amenities or maintaining a substantial family home, these costs remain constant even as one salary disappears. Balancing this gap requires a strategy that views the household's total capital as a unified resource rather than two isolated pools of money.
Synchronising Retirement Dates and Lifestyle Expectations
Communication precedes calculation. We often see couples where one partner dreams of becoming a "Grey Nomad" while the other prefers the stability and community of their Shire home. Resolving these lifestyle conflicts early is essential for financial accuracy. Staggered retirement also introduces complex Centrelink implications that can catch families off guard. For instance, the superannuation of a partner under the Age Pension age is generally not counted in the other partner's assets test if it remains in the accumulation phase. This creates strategic opportunities for income optimisation that only a unified, research-driven approach can capture.
The Individual Nature of Australian Superannuation
Superannuation remains an individual asset. Despite decades of partnership, you cannot hold a joint super account in Australia. This legal separation often leads to "portfolio drift," where a couple's total exposure to market risk becomes unbalanced because their individual accounts aren't coordinated. Coordination is vital to ensure that tax-minimisation strategies, such as contribution splitting or spouse offsets, are utilised to their full potential before the transition occurs. A joint strategy approach ensures that while accounts remain legally separate, their investment objectives and withdrawal sequences are engineered to function as a single, optimised financial engine. Effective retirement planning for couples Miranda treats these individual accounts as complementary components of a larger, bespoke wealth preservation plan designed to last as long as you both do.
Strategic Superannuation for Shire Couples
Superannuation is inherently individual, yet its outcomes are shared. For those navigating retirement planning for couples Miranda, the objective is to move beyond mere accumulation toward the strategic balancing of two separate accounts. By synchronising your contributions, you can effectively double your household's access to tax-free retirement phase limits. According to the ASFA Retirement Standard, couples require approximately $77,375 per year for a comfortable lifestyle; achieving this sustainably often hinges on how well you leverage joint tax thresholds and contribution caps.
Super Splitting and Spouse Contributions
Balance is power. Super contribution splitting allows you to transfer up to 85% of your concessional contributions from the previous financial year to your partner's account. This is particularly effective if one partner has a significantly higher balance or is closer to the $2.1 million Transfer Balance Cap. Additionally, for partners earning lower incomes, the higher earner may benefit from a tax offset of up to $540 by making a non-concessional spouse contribution. These mechanisms don't just reduce your immediate tax liability; they ensure both partners have robust, tax-effective income streams as they transition away from the workforce. It's a methodical way to optimise the lower-balance account, ensuring that the total household wealth remains protected within the tax-free environment of the pension phase.
The Re-contribution Strategy: A Tax Legacy Tool
Estate planning in the Sutherland Shire often involves high-value primary residences and substantial super balances. The Re-contribution Strategy serves as a sophisticated tool to protect these assets for the next generation. By withdrawing a portion of your super and re-contributing it as a non-concessional payment, you can convert "taxable" components into "tax-free" components. This is a vital consideration for retirement planning for couples Miranda because adult children often face a 15% tax plus Medicare levy on the taxable portion of a super death benefit. This strategy minimises the tax burden on your beneficiaries while maintaining the integrity of your joint fund. If you are considering whether a Self-Managed Super Fund (SMSF) provides the necessary flexibility for these bespoke manoeuvres, reviewing your current superannuation structure is a logical first step toward long-term clarity.
Modelling the Miranda Lifestyle and Cash Flow
Equity is the engine. For many residents in the Sutherland Shire, the family home represents the largest single component of their net wealth. When approaching retirement planning for couples Miranda, it is essential to look beyond the balance sheet and consider the "Miranda Factor." This involves assessing how local property values and potential downsizing opportunities can be harnessed to fund a decades-long lifestyle. The Australian Taxation Office provides various avenues for integrating property proceeds into your retirement strategy, ensuring your primary asset contributes to your long-term liquidity.
Clarity replaces confusion. We move from broad estimates to precise projections by mapping out your joint cost of living. This includes everything from the routine expenses of Shire life—such as local dining and coastal recreation—to the costs of maintaining your connection to the CBD. By factoring in local healthcare preferences and potential aged care requirements early, we ensure that your cash flow model remains realistic and resilient. This level of detail is what allows a couple to transition from the accumulation phase to the spending phase with absolute confidence.
The Downsizing Decision in the Sutherland Shire
Emotional ties run deep. Moving from a long-term family home in Miranda or Cronulla is rarely just a financial transaction; it is a significant life event. However, the "Downsizer Contribution" rule allows eligible individuals aged 55 or older to contribute up to $300,000 from the sale of their home into their superannuation. For a couple, this provides a potential $600,000 injection into a tax-effective environment. This strategy effectively converts illiquid home equity into a sustainable income stream, helping to bridge the gap between your current lifestyle and your future needs without compromising your financial longevity.
Long-term Projections and Stress Testing
Numbers provide certainty. We utilise research-driven Retirement Modelling Sydney to simulate various economic conditions, including market downturns and shifting inflation rates. This "Steady Navigator" approach ensures your portfolio can withstand a sequence of returns risk, where a market crash early in retirement could otherwise derail your shared plans. By projecting your joint cash flow through multiple scenarios, we create a bespoke roadmap that accounts for every variable. This methodical stress testing replaces the anxiety of the unknown with a structured, evidence-based path toward a stable and prosperous future.
Managing Joint Risks: Longevity and Sequence of Returns
Joint retirement planning introduces a unique set of variables that individual planning often overlooks. When we discuss retirement planning for couples Miranda, we are essentially planning for the longest possible life expectancy between two people. This creates a "longevity gap" that must be bridged with certainty. While a couple needs an estimated $77,375 per year for a comfortable lifestyle according to late 2025 standards, the financial burden does not halve when one partner passes away. Fixed costs like Shire rates, utilities, and home maintenance remain constant, making it vital to structure income streams that remain robust for the surviving partner.
Longevity risk management for a dual-income household is the strategic engineering of capital to ensure income persists until the final survivor's needs are met. Statistically, there's a significant probability that at least one member of a couple will reach age 95 or beyond. Planning for a thirty-year horizon requires more than just a healthy super balance; it requires a portfolio that can withstand the "hidden" costs of aging, including private healthcare and potential aged care transitions. Factoring in these costs early ensures that your capital isn't depleted just as your need for support increases.
The Danger of the First Five Years
Sequence of returns risk is perhaps the most overlooked threat to a joint retirement. If the market experiences a significant downturn in the first five years of your retirement, the impact on your combined capital can be permanent because you're withdrawing funds while asset prices are depressed. We address this by constructing portfolios that prioritise wealth preservation and low volatility. Our in-house Investment Committee focuses on bespoke portfolio construction, ensuring your assets aren't just diversified, but specifically insulated against early-stage market shocks that could otherwise derail your shared lifestyle goals.
Investment Strategies for Stability
Achieving stability requires a move away from generic, "off-the-shelf" investment models. By seeking Bespoke Investment Advice Sydney, couples can access portfolios engineered for the specific economic climate of 2026. These strategies focus on inflation protection, which is critical as cost-of-living pressures continue to affect the Shire. Protecting your joint capital is about more than just avoiding losses; it's about maintaining purchasing power over three decades. To ensure your current strategy is resilient enough to handle these dual risks, you should review your joint risk profile with a professional navigator who understands the local landscape.
Securing Your Legacy: Estate Planning in Miranda
Legacy is built on more than just wealth; it is built on the clarity of your intentions. For retirement planning for couples Miranda, the objective of estate planning is to ensure that your joint financial structure remains a source of stability even when one partner is no longer there. This requires a deliberate shift from asset accumulation to strategic distribution. By coordinating your wills, superannuation nominations, and trust structures, you protect your surviving spouse from administrative burdens while securing the financial future of the next generation.
Intergenerational wealth management in the Sutherland Shire often involves high-value property and substantial investment portfolios. Protecting these assets requires a "no-nonsense" approach to tax efficiency and legal robustness. We focus on minimising the "taxable component" of your superannuation, which can otherwise trigger a significant tax bill for adult children who inherit your fund. This methodical structuring ensures that the wealth you have spent a lifetime building remains intact as it passes to your beneficiaries.
Reversionary Pensions vs. New Nominations
Administrative ease provides emotional space. A reversionary pension is often the preferred choice for couples because it allows an income stream to continue automatically to the surviving spouse without the need for immediate legal intervention. This "calmer" path ensures that lifestyle continuity is maintained during a period of grief. From a technical perspective, a reversionary pension also offers a 12-month grace period before the value of the pension counts toward the survivor’s Transfer Balance Cap. This provides essential time to reorganise financial affairs without breaching the $2.1 million limit. While a Binding Death Benefit Nomination (BDBN) is a vital legal instruction for many, the reversionary pension offers a level of seamlessness that is difficult to replicate through other nominations.
The Intergenerational Transfer of Wealth
Your legacy has a "True North." Effectively managing Wealth Transfer Strategies Australia requires a proactive approach to protecting the family home and investment portfolios. For many Miranda families, this involves more than just drafting documents; it involves communication. We often recommend organising a formal family meeting to discuss your intentions and the logic behind your bespoke wealth preservation strategy. This transparency reduces the risk of future conflict and ensures that your heirs are prepared to step into their roles as stewards of the family legacy. By aligning your estate plan with your retirement goals, you create a protected environment where your family's financial future is secured across multiple generations.
Synchronising Your Shared Path Forward
Retirement is not merely a destination; it is a shared transition that requires both technical precision and emotional empathy. By aligning your individual superannuation histories and leveraging bespoke modelling, you can transform a complex financial puzzle into a clear, unified roadmap. This process involves more than just balancing accounts. It requires the strategic construction of a lifestyle that protects both partners, regardless of how the economic landscape shifts in the coming decades.
Successful retirement planning for couples Miranda relies on an authoritative approach to risk management and wealth preservation. Our research-driven Investment Committee and expertise in complex couple strategies provide the stabilizing force needed to navigate this transition with quiet certainty. Whether you are exploring downsizing opportunities in the Shire or refining your legacy through reversionary pensions, the goal is total clarity. We invite you to Book a Retirement Clarity Consultation in Miranda to begin your structured modelling journey. Stepping into your future with a proven plan allows you to focus on what truly matters: enjoying the life you have built together.
Frequently Asked Questions
Can we have a joint superannuation account in Australia?
No, you cannot have a joint superannuation account in Australia. Superannuation is legally structured as an individual asset, meaning each partner must maintain their own separate account. However, retirement planning for couples Miranda focuses on coordinating these individual accounts as a single, unified strategy. This allows you to manage investment risk across both portfolios while utilising spouse contributions to balance your combined household wealth more effectively.
How much do we need to retire as a couple in Sydney?
A couple requires approximately $77,375 per year for a comfortable retirement lifestyle, according to the ASFA Retirement Standard. In high-value areas like Sydney and the Sutherland Shire, your specific modelling should account for local lifestyle expectations and property maintenance costs. We use bespoke projections to determine the exact capital required to sustain your desired standard of living without the risk of outliving your joint savings.
What is the best way to split super contributions with my spouse?
The most effective method is through concessional contribution splitting, which allows you to transfer up to 85% of your taxed contributions to your partner's account. This is a vital tool for balancing account sizes, especially if one partner is approaching the $2.1 million Transfer Balance Cap. It ensures that both partners can maximise their tax-free pension phase limits, creating a more resilient and tax-effective income stream for the household.
How does the downsizing contribution work for couples in Miranda?
If you are aged 55 or older, you can each contribute up to $300,000 into your superannuation from the proceeds of selling your primary residence in Miranda. This Downsizer Contribution does not count toward your standard non-concessional contribution caps. For a couple, this represents a potential $600,000 injection of capital into a tax-effective environment, helping to convert home equity into a sustainable and liquid retirement income stream.
What happens to our retirement income if one of us passes away?
Your retirement income can continue seamlessly if you have established a reversionary pension. This structure ensures that the income stream automatically transfers to the surviving partner without administrative delays or the need for a new pension application. Without this, the super balance may be paid out as a lump sum or require complex legal intervention. Effective retirement planning for couples Miranda prioritises these structures to provide immediate financial stability.
Should we use an SMSF or an industry fund for our joint retirement?
The choice depends on your need for control and the complexity of your joint strategy. An SMSF offers significant flexibility for bespoke portfolio construction and sophisticated estate planning manoeuvres like the re-contribution strategy. Industry funds provide lower administrative overhead but may lack the granular control required for complex wealth preservation. We evaluate your combined assets to determine which structure offers the best probability of achieving your specific goals.
How do we maximise our Centrelink Age Pension as a couple?
Maximising entitlements often involves strategic asset placement, such as holding wealth in the superannuation account of a partner who is under the Age Pension age. Assets in the accumulation phase for a younger spouse are generally exempt from the Centrelink assets test. This can result in a higher combined pension payment for the household. Precise Centrelink structuring is a core component of our modelling for residents across the Sutherland Shire.
What is the re-contribution strategy and why should couples use it?
The re-contribution strategy involves withdrawing super funds and re-contributing them as non-concessional payments to convert taxable components into tax-free ones. Couples use this to reduce the potential 17% tax that adult children may pay on inherited super death benefits. It is a powerful legacy tool that protects your wealth for the next generation while maintaining your own access to tax-free income throughout your joint retirement years.


