

Wealth is eroded silently. Most Australians are unintentionally donating thousands of dollars in unnecessary fees to superannuation funds they no longer use, simply because they haven't unified their financial strategy. When considering superannuation consolidation Miranda residents often focus on the administrative burden, yet the true value lies in the strategic alignment of your long-term goals. It's understandable to feel a sense of unease when faced with multiple statements, conflicting investment strategies, and a fragmented view of your retirement savings.
You deserve a sense of order. By merging your accounts, you can lower your overall fees and gain confidence that your insurance cover is both sufficient and secure. This guide explores how to strategically optimise your superannuation for 2026, protecting your wealth while simplifying your path to a calm retirement. We will examine the latest contribution caps, the risks of losing default insurance, and the methodology behind building a single, high-performing account tailored to your lifestyle in the Sutherland Shire.
Key Takeaways
- Discover how superannuation consolidation Miranda can replace financial clutter with a single, high-performance vehicle tailored to your specific retirement goals.
- Identify how to eliminate duplicate administration fees to accelerate compound interest and ensure your total balance is invested according to your risk profile.
- Learn to navigate the "insurance trap" by protecting your existing life and TPD cover before initiating any fund transfers or account closures.
- Master a clear, two-step audit process using myGov and Benefit Statements to reveal hidden costs and fragmented savings from previous career stages.
- Understand the value of bespoke retirement modelling in creating a stable, research-driven path toward a calm and secure lifestyle in the Sutherland Shire.
Understanding Superannuation Consolidation in the Sutherland Shire
Order creates confidence. For many professionals in the Sutherland Shire, superannuation has become a collection of historical accidents rather than a deliberate strategy. Each new role often results in a new fund, leaving a trail of accounts that lack a cohesive direction. Strategic superannuation consolidation Miranda is the process of aligning these fragmented accounts into a single, high-performance vehicle designed to support your specific lifestyle goals. By centralising your assets, you replace the quiet anxiety of "not knowing" with a structured financial path that is easy to monitor and manage.
Superannuation consolidation is a fundamental pillar of wealth preservation, ensuring that every dollar contributed works toward a unified retirement vision rather than being dispersed across redundant structures. In a landscape as complex as Understanding Superannuation in Australia, maintaining a clear line of sight on your total balance is essential for long-term sustainability.
The Problem with Multiple Super Accounts
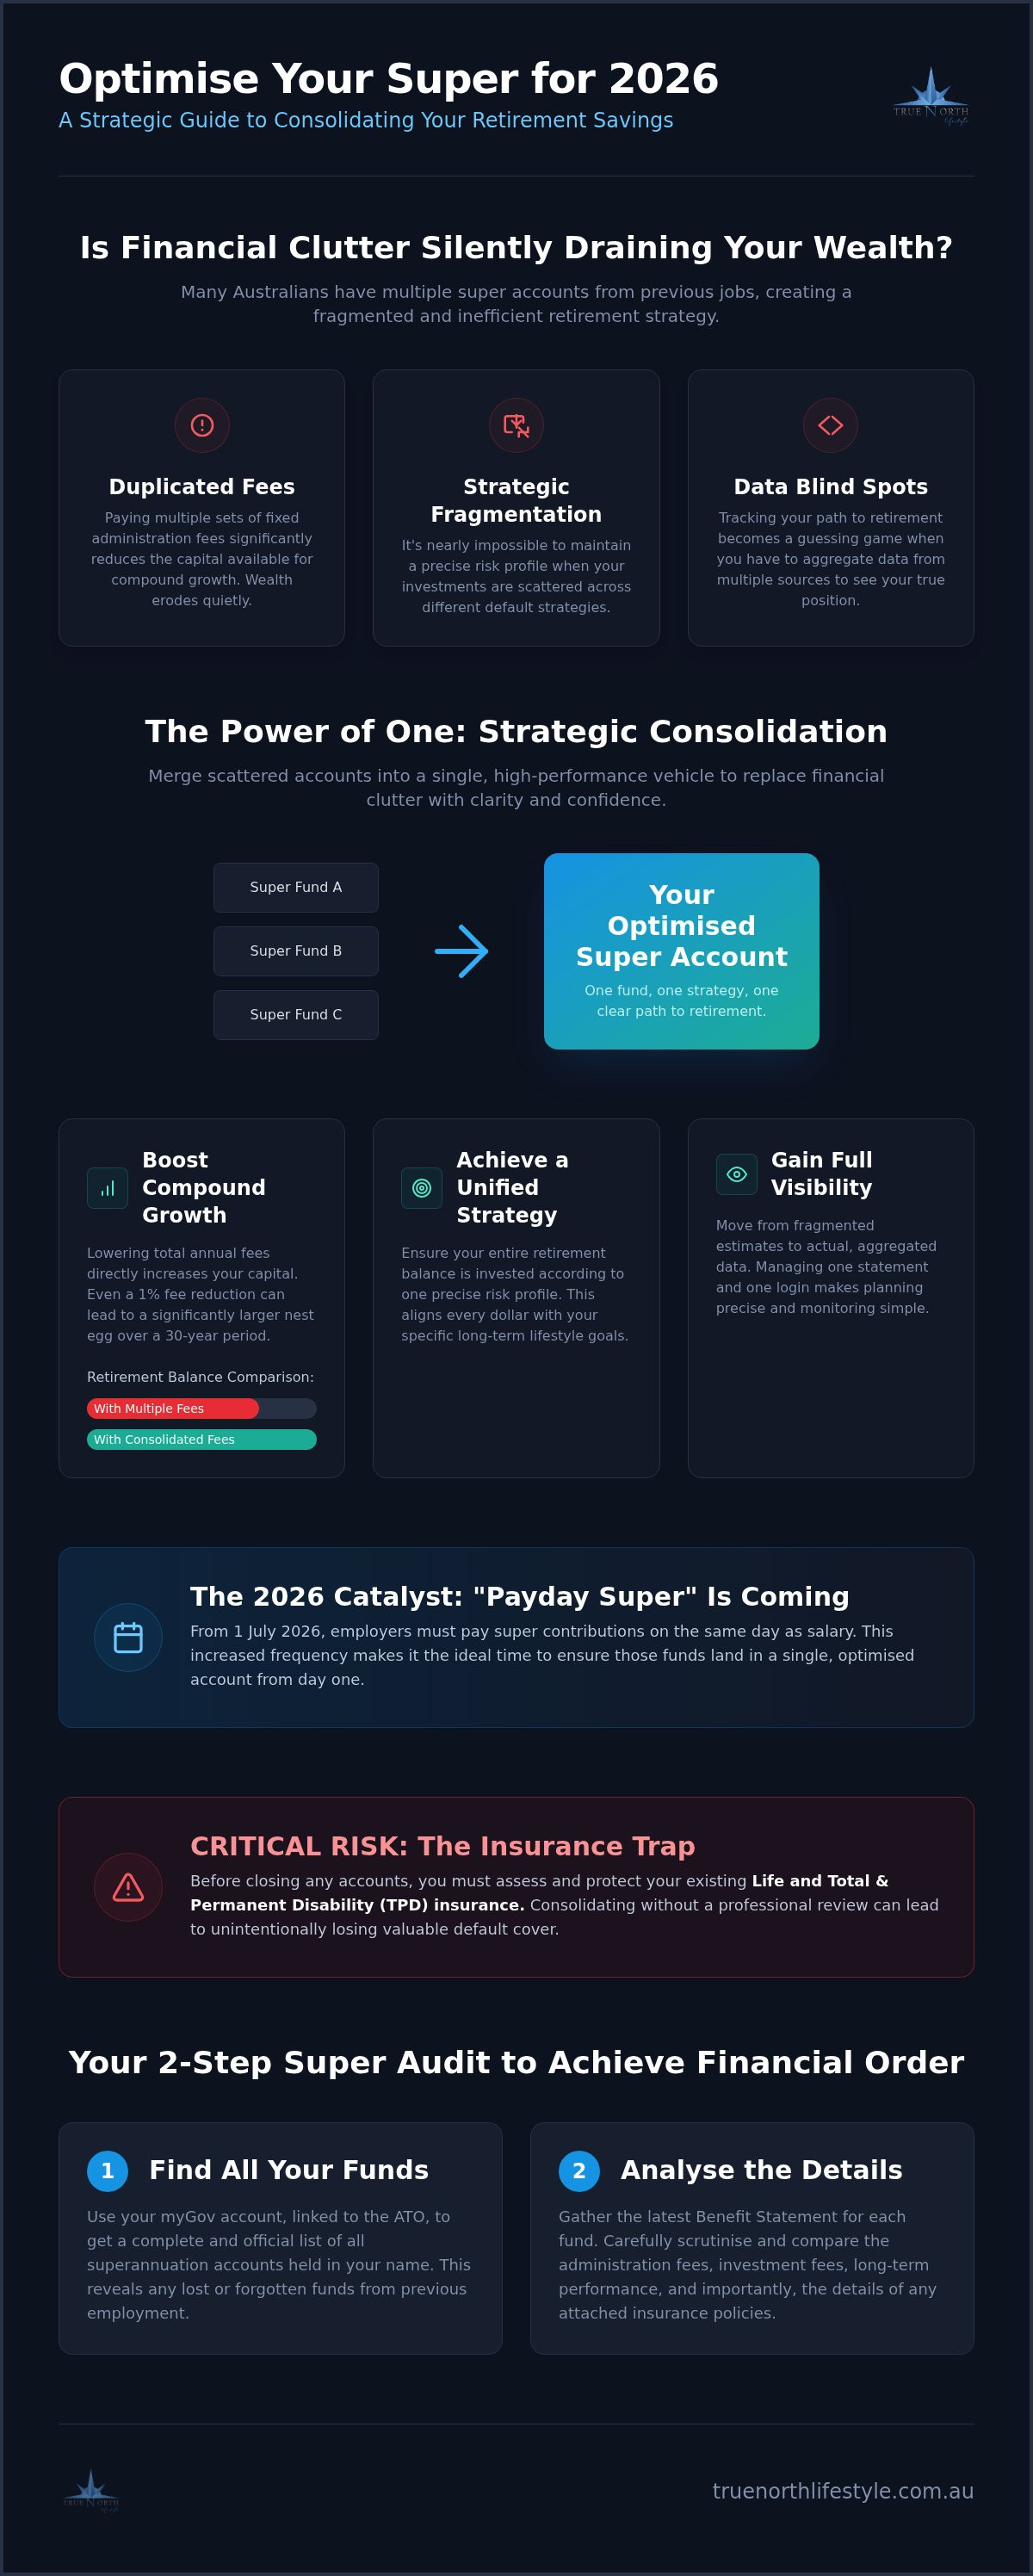
Capital erodes quietly. When your retirement savings are split across multiple platforms, you aren't just paying more; you're losing the benefit of scale. The impact of maintaining several accounts includes:
- Duplicated Fees: Most funds charge fixed administration fees. Paying these three or four times over significantly reduces the capital available for compound growth.
- Strategic Fragmentation: It is nearly impossible to maintain a precise risk profile when your investments are scattered across different default options with varying asset allocations.
- Data Blind Spots: Tracking your path to retirement becomes a guessing game when you have to aggregate data from multiple portals to see your true financial position.
Why 2026 is the Year to Organise Your Super
Precision is required now. The landscape for 2026 introduces significant shifts, including the implementation of "Payday Super" from 1 July 2026, which requires employers to pay contributions on the same day as salary and wages. This change increases the frequency of contributions, making it the ideal time to ensure those funds land in a single, optimised account. For Miranda residents, the local shift toward more sophisticated, bespoke financial oversight reflects a broader desire for clarity. Cleaning the slate now allows you to enter the next high-growth phase of your career without the drag of administrative clutter. Sutherland Shire professionals are increasingly seeking strategic reviews to ensure their superannuation consolidation Miranda is handled with the technical depth required to protect their tax positions and insurance entitlements before the new regulatory environment takes full effect.
The Strategic Benefits: Why Merging Super Matters
Clarity drives performance. When your retirement savings are unified, you move from a state of passive accumulation to one of active, strategic growth. The primary advantage of superannuation consolidation Miranda is the immediate cessation of fee leakage. Most Australians are unaware that maintaining multiple accounts often means paying multiple sets of fixed administration fees, which can quietly drain thousands of dollars from your future lifestyle. By centralising these assets, you ensure that every dollar is accounted for and working toward a singular, well-defined objective.
Beyond the immediate cost savings, merging your accounts provides a superior level of visibility. Managing one statement and one digital login allows for more precise retirement planning Sydney, ensuring that your long-term projections are based on actual, aggregated data rather than fragmented estimates. While there are specific risks of consolidating your super that must be professionally assessed, such as the potential loss of legacy insurance terms, the strategic benefits of a unified structure are substantial for those seeking financial order.
Compound Interest: The Silent Beneficiary of Lower Fees
Fees compound too. A technical analysis of retirement outcomes often reveals that even a 1% difference in total annual fees can result in a significantly smaller nest egg over a 30-year period. This "leakage" effect is particularly damaging in the early stages of wealth accumulation where every dollar of capital is required to fuel future growth. Reducing your ongoing costs through consolidation directly increases the capital longevity of your fund, allowing your savings to remain invested and productive for longer during your post-work years.
Bespoke Portfolio Construction
Avoid the default. Most large industry funds rely on "one-size-fits-all" investment models that may not align with your specific tolerance for risk or your timeline for retirement. At True North Lifestyle, we believe in moving away from these generic structures toward bespoke portfolio construction. Our methodology focuses on low volatility and research-driven asset allocation, ensuring your super is integrated with your broader wealth preservation strategies. This tailored approach allows for a more stable progression toward your goals, providing the quiet certainty that your portfolio is built to withstand market fluctuations.
If you feel your current superannuation structure lacks this level of coordination, a professional superannuation review and optimisation can provide the technical roadmap needed to restore balance to your accounts.
Critical Risks: What the Big Funds Don’t Tell You
Efficiency has a shadow. While the benefits of a unified account are clear, executing a DIY rollover without technical oversight can lead to irreversible financial loss. This is often referred to as the "Insurance Trap." When considering superannuation consolidation Miranda, you must look beyond the surface level of fee savings and scrutinise the fine print of your existing benefits. Many members mistakenly believe that their insurance cover will simply "follow" them to a new fund. In reality, closing an old account typically terminates those policies instantly, potentially leaving you and your family unprotected at a critical time.
The danger is particularly acute if you have developed health conditions since your original policies were established. Large industry funds often gloss over the fact that re-applying for cover in a new environment involves fresh underwriting. If your health status has changed, you may find yourself facing significant exclusions or higher premiums that you didn't have before. True wealth preservation requires a "Steady Navigator" approach; we ensure that your protection remains a constant, even as your investment structure evolves.
Protecting Your Insurance Cover
Tailored cover is an asset. Automatic or "default" cover in a new fund is often generic and may not reflect the specific needs of Sutherland Shire professionals. Before any funds are moved, it is essential to conduct a formal comparison of your existing Life, TPD, and Income Protection policies against the proposed new structure. Our Miranda advisers use detailed modelling to determine if a "transfer of cover" is possible. This process involves securing a formal Letter of Acceptance from the new insurer before the legacy account is closed, ensuring there is never a gap in your security.
Tax Minimisation and Personal Contributions
Timing determines your tax outcome. If you've made personal concessional contributions to your super, you must lodge a "Notice of Intent" (Section 290-170) with your current fund before initiating a rollover. If you close the account before the fund acknowledges this notice, you lose the ability to claim a tax deduction on those contributions forever. This is a common and expensive error for those attempting to manage their own consolidation.
Strategic management also involves monitoring your concessional contribution caps, which sit at $32,500 for the 2026-27 financial year. When moving between multiple funds in a single year, it's easy to lose track of the total amounts contributed by various employers. We provide the technical depth required to coordinate these movements, ensuring you remain compliant while maximising your tax position during the transition phase.
A Miranda Guide: Assessing Your Funds for 2026
Clarity requires a rigorous methodology. To execute an effective superannuation consolidation Miranda residents must move beyond surface-level comparisons and adopt a research-driven audit of their current holdings. This is not merely an administrative task; it is a strategic reconstruction of your financial foundation. By following a structured assessment process, you can transform a cluttered portfolio into a streamlined vehicle for long-term growth.
The first stage involves a comprehensive audit of all existing accounts via the myGov portal. This step is essential for identifying "lost" super or accounts from early career stages that may be quietly eroding due to duplicated fees. Once all accounts are identified, you must request formal "Benefit Statements" from each provider. These documents provide the technical depth required to identify hidden administration costs, investment management fees, and the specific premiums being deducted for insurance cover. Only with this data can you accurately compare 5 and 10-year performance averages against industry benchmarks to determine if your current funds are truly serving your interests.
Evaluating Fund Performance vs. Fees
The cheapest fund is rarely the most effective. While fee reduction is a primary driver of consolidation, the true measure of a fund's value is its net-of-fees return over a sustained period. It is a common mistake to focus solely on the lowest cost, yet a fund with slightly higher fees that consistently outperforms its peers on a net basis will provide a superior retirement outcome. We pay close attention to funds flagged by APRA's annual performance tests, ensuring your capital is moved away from chronic underperformers and toward stable, high-performance environments.
Local Expertise in the Sutherland Shire
Complexity requires a steady partner. For professionals with intricate family structures or specific legacy requirements, the value of face-to-face superannuation advice Sutherland Shire cannot be overstated. From our Miranda office, we provide the technical oversight needed to coordinate your superannuation with broader financial needs, such as Centrelink structuring and Age Pension entitlements. This local presence ensures your strategy is grounded in your real-world circumstances rather than a generic algorithm. We help you navigate the transition from accumulation to retirement with the quiet certainty that every detail has been considered.
If you are ready to replace financial clutter with a structured, professional plan, we invite you to book a superannuation review and optimisation session with our Miranda team today.
Bespoke Superannuation Strategies with True North Lifestyle
Clarity replaces chaos. While the technical process of superannuation consolidation Miranda is an essential first step, the true value of your retirement strategy is found in how those unified assets are managed over the long term. At True North Lifestyle, we act as your Steady Navigator. We move beyond the "intra-fund" advice typically offered by large industry funds, which is often limited to their own products. Instead, we provide a holistic view of your financial life, ensuring your super is perfectly synchronised with your broader goals and tax planning for retirement Australia.
Professional oversight provides a sense of quiet certainty. Our methodology is built on a foundation of rigorous testing and evidence-based logic. We don't rely on guesswork or flashy innovation; we rely on proven outcomes. By centralising your accounts through a strategic superannuation consolidation Miranda process, you allow us to apply a disciplined, research-driven approach to every dollar you've worked for. This ensures your portfolio is not just a collection of assets, but a carefully constructed engine for your future lifestyle.
Retirement Modelling and Projections
Numbers tell a story. We utilise sophisticated modelling software to move beyond vague estimates and provide you with concrete projections. This technology allows us to show you exactly how consolidation and fee reduction affect your projected retirement date. We employ scenario-based thinking to answer the "what ifs" that often cause anxiety. Whether it's market fluctuations during your transition or changes in legislation, our models help you visualise the impact on your capital. This process allows us to build a sustainable withdrawal strategy from day one, giving you the confidence to step into retirement with a clear, well-defined path.
The True North Lifestyle Difference
Protection is our priority. Our investment philosophy focuses on bespoke, low-volatility portfolios designed to preserve your capital while seeking consistent growth. Every strategy we implement is overseen by our dedicated Investment Committee, ensuring your portfolio benefits from a high level of technical competence and oversight. We invite you to visit our Miranda office for a no-nonsense assessment of your current structure. This is an opportunity to move away from the noise of the financial industry and toward a role of confident oversight. Let us do the heavy lifting so you can enjoy the stability and order you deserve in the Sutherland Shire.
Securing Your Path to Financial Clarity
Order is achievable. By addressing the fragmentation of your retirement savings today, you eliminate the silent erosion of fees and ensure your risk profile is perfectly aligned with your long-term vision. We have explored the technical necessity of auditing your accounts and the critical importance of protecting your insurance entitlements before any move is made. A successful superannuation consolidation Miranda process is not merely a task of merging balances; it is a strategic step toward a more stable and predictable future.
Our methodology combines local Sutherland Shire expertise with sophisticated retirement modelling to replace uncertainty with a structured plan. We utilise research-driven investment strategies to build portfolios designed to protect your capital through every market cycle. You don't have to navigate these complexities alone. Taking control of your superannuation is the first step toward the calm retirement you've worked to build.
Secure your financial future with a bespoke superannuation review in Miranda
Your retirement should be a period of quiet certainty. We are here to help you navigate that journey with precision and care.
Frequently Asked Questions
How do I find all my lost superannuation accounts in 2026?
You can locate all lost or unclaimed superannuation through the Australian Taxation Office (ATO) online services via your myGov account. This portal provides a consolidated view of all accounts linked to your Tax File Number, which is the most efficient way to identify fragmented savings from previous employers. Given the 2026 shift toward "Payday Super," maintaining an accurate view of your active accounts is essential for ensuring all contributions are being received correctly.
Will I lose my life insurance if I consolidate my super accounts?
Closing a superannuation account will typically terminate any associated life, TPD, or income protection insurance immediately. To avoid this, you must apply to transfer your existing cover to your chosen fund and receive a formal "Letter of Acceptance" before initiating the superannuation consolidation Miranda process. This prevents you from being left unprotected or forced to undergo new medical underwriting with potentially higher premiums.
Is there a tax cost to moving my super from one fund to another?
There is usually no direct tax penalty for rolling over super between funds, provided the transfer is handled as a formal rollover between complying funds. However, a significant risk exists if you have made personal concessional contributions. You must lodge a "Notice of Intent" and receive an acknowledgement from your current fund before closing the account; otherwise, you will permanently lose the ability to claim a tax deduction on those contributions.
Can I consolidate my super into a Self-Managed Super Fund (SMSF)?
Yes, you can roll your existing super balances into a Self-Managed Super Fund if that structure aligns with your long-term wealth preservation goals. This move requires a high level of technical oversight to ensure the transfer is compliant and that your investment strategy remains research-driven. We often help clients determine if a bespoke portfolio within a professionally managed fund or an SMSF is the most stable path for their specific retirement projections.
How long does the superannuation consolidation process usually take?
Simple rollovers initiated through myGov often take between three and five business days to complete once approved by the transferring fund. If your consolidation involves transferring insurance or complex legacy benefits, the process can take several weeks or even months. This extended timeline is necessary to ensure that your new insurance cover is fully underwritten and active before your old policies are cancelled.
Should I seek professional advice before merging my super funds?
Seeking professional advice is highly recommended to prevent the accidental loss of valuable insurance benefits or tax deductions. A strategic review ensures that your superannuation consolidation Miranda is based on detailed modelling of your retirement date and total fee impact. This objective oversight helps you avoid "underperforming" funds and ensures your consolidated balance is invested in a way that reflects your personal risk profile.
What is the Superannuation Guarantee rate for the 2026 financial year?
The Superannuation Guarantee (SG) rate is 12% for the financial year beginning 1 July 2025 and moving through 2026. This legislated rate means a larger portion of your income is being directed into the super system. With more capital entering your fund, ensuring your account is optimised and not being drained by multiple sets of administration fees is more important than ever for your long-term capital longevity.
Does True North Lifestyle help with the paperwork for super rollovers?
True North Lifestyle provides comprehensive coordination and implementation support for superannuation rollovers as part of our review and optimisation service. We handle the technical requirements and communication with various fund providers to ensure your transition is seamless. Our team ensures that all tax notices are lodged correctly and that your insurance cover is secure, allowing you to step into a role of confident oversight without the administrative burden.


