

What if the greatest risk to your retirement isn't a market downturn, but the loss of the professional identity you've spent decades building? For many high achievers across Sydney, the transition away from a demanding career feels less like a finish line and more like a loss of direction. It's natural to feel anxious about 2026 inflation eroding your purchasing power or the persistent complexity of superannuation rules. You want to know that your hard-earned capital is secure, yet you also deserve the freedom to actually enjoy it.
Clarity brings confidence. We understand that funding your retirement lifestyle Australia requires more than just a "magic number"; it demands a marriage of purpose-driven design and rigorous mathematical stress-testing. This guide provides a clear mental blueprint for your post-work years. You'll learn how to harmonise your personal aspirations with bespoke financial modelling. We will preview how to navigate the latest A$32,500 concessional contribution caps and complex Centrelink asset tests with quiet certainty, ensuring your family legacy remains protected while giving you the genuine permission to spend.
Key Takeaways
- Discover how to bridge the "Identity Gap" by intentionally aligning your personal time and health with your financial capital for a purpose-driven transition.
- Learn why funding your retirement lifestyle Australia requires a robust financial engine that integrates strategic tax-minimisation with superannuation optimisation.
- Identify the three non-financial pillars-health, social connection, and purpose-that are essential for maintaining a sense of order and fulfilment.
- Understand how rigorous portfolio stress-testing protects your purchasing power against 2026 inflation and market volatility.
- Explore how precision modelling provides a clear mental blueprint, offering the "permission to spend" while ensuring your family legacy remains secure.
Beyond the Balance Sheet: The Psychology of Designing Your Ideal Retirement Lifestyle
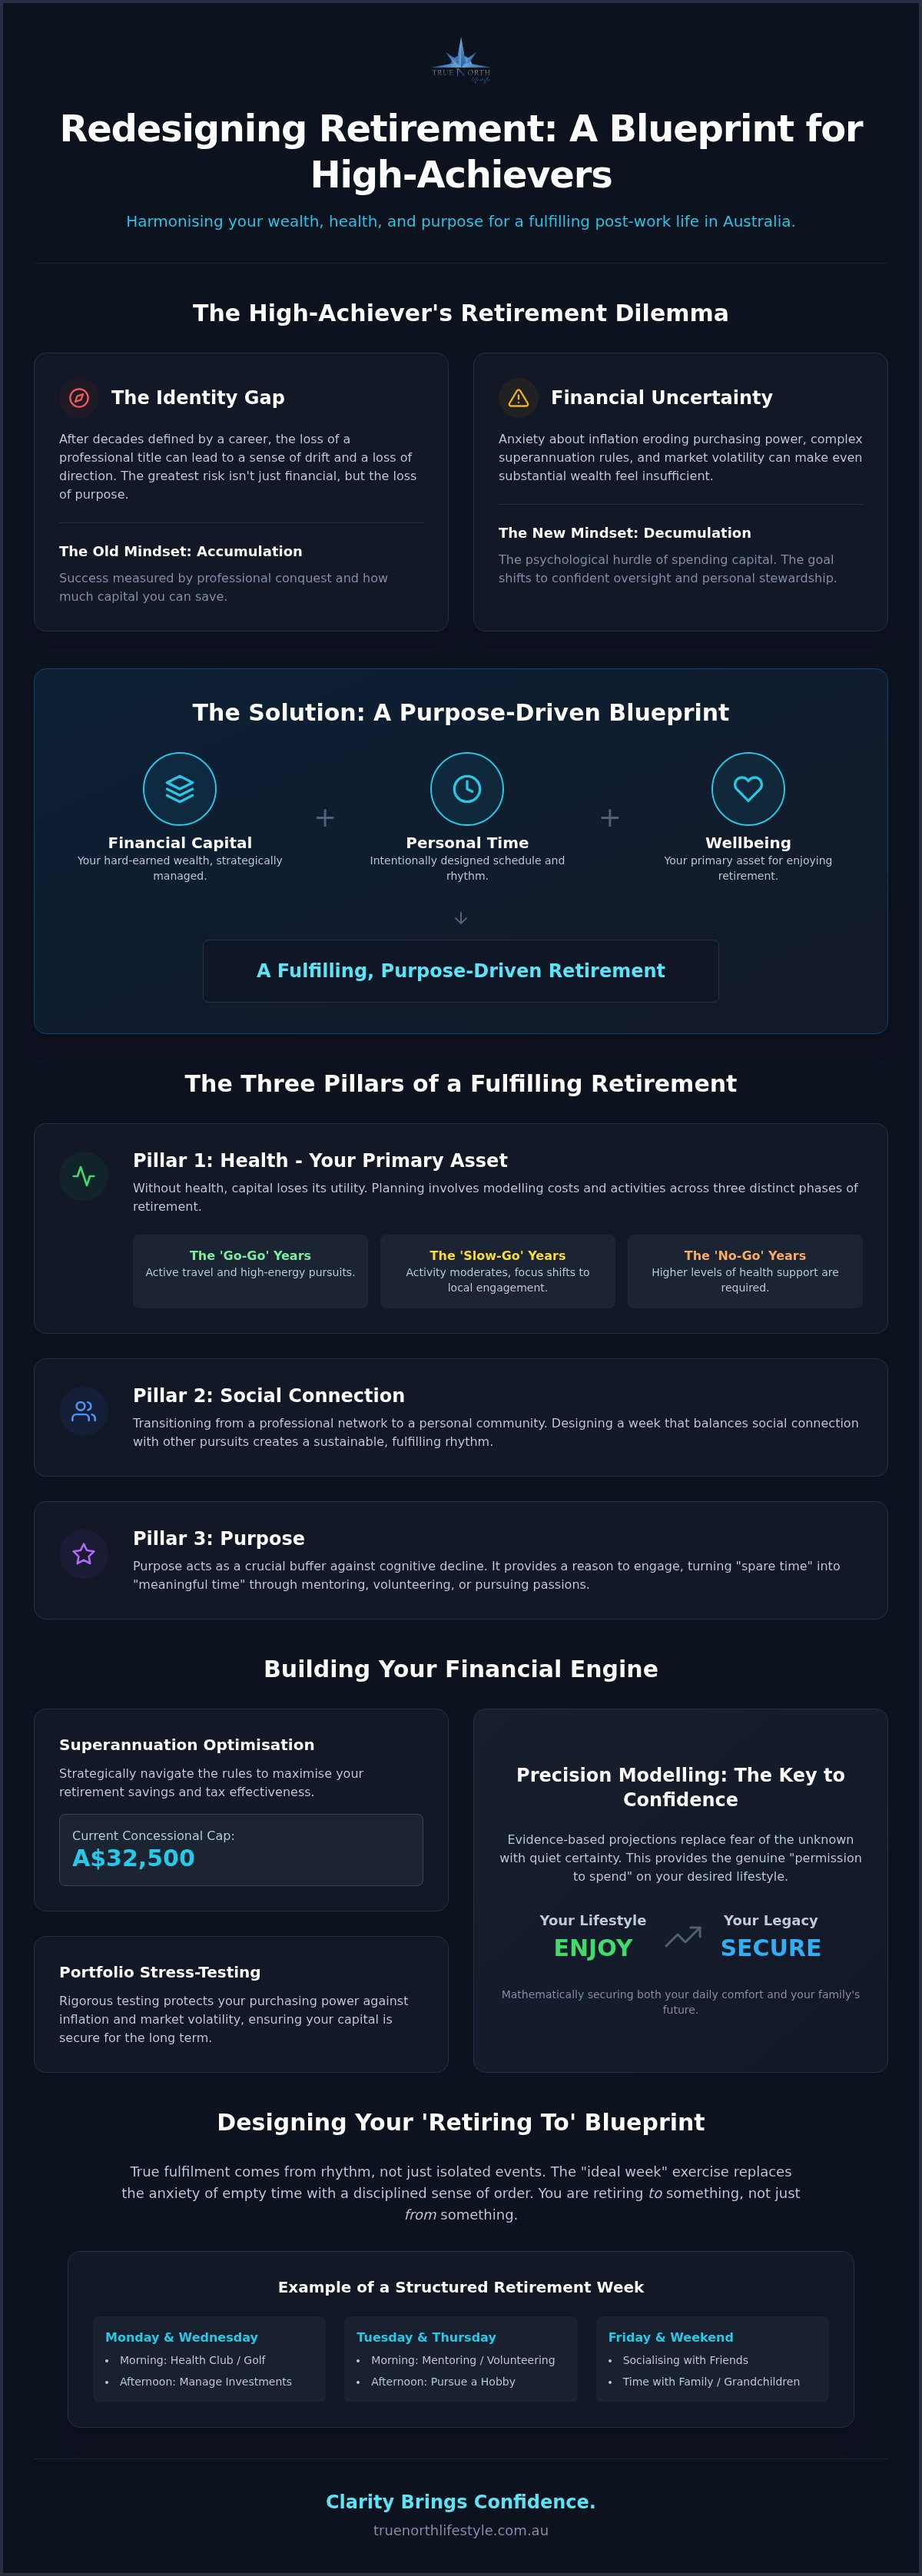
Retirement is more than a cessation of work. It is a strategic redesign of your daily existence. At its core, retirement lifestyle design is the intentional alignment of your time, your health, and your capital. While many focus solely on the financial ledger, a plan without a lifestyle vision is inherently fragile. It lacks the emotional anchor required to sustain a fulfilling post-work life. For professionals in the Sydney CBD and Miranda, the transition often triggers a profound "Identity Gap." After decades of being defined by a high-pressure career, the sudden absence of a professional title can lead to a sense of drift. Funding your retirement lifestyle Australia involves addressing this psychological shift with the same rigour you apply to your investment portfolio.
Think of yourself as the Steady Navigator. The transition requires moving from a mindset of professional conquest to one of personal stewardship. Without a structured blueprint, even the most substantial wealth can feel insufficient. To build a stable future, you must first define what that future looks like in practice. This ensures your Superannuation in Australia serves a purpose beyond mere accumulation, acting instead as the fuel for a well-defined journey.
Visualising Your 'Retiring To' Blueprint
Purpose requires structure. The common myth of retirement as a "permanent holiday" often leads to a hollow experience within the first eighteen months. True fulfilment comes from rhythm rather than just isolated events. We encourage clients to undertake the "ideal week" exercise. Instead of listing grand travel plans, focus on how you will organise your Tuesday mornings or Thursday afternoons. Will you be mentoring? Are you investing in your physical health at a local club in the Sutherland Shire? By designing a week that balances social connection, physical activity, and intellectual pursuit, you create a sustainable life that you are retiring to, rather than just from. This clarity replaces the anxiety of empty time with a disciplined sense of order.
The Shift from Accumulation to Decumulation
Old habits die hard. For forty years, your financial success was measured by how much you could save. Suddenly, the rules change. The psychological hurdle of spending your capital is significant; it can feel like you are eroding your safety net. This is where funding your retirement lifestyle Australia becomes a matter of clarity. Precision modelling replaces the fear of the unknown with a sense of quiet certainty. When you can see, through evidence-based projections, that your lifestyle is fully supported even under volatile market conditions, you gain the genuine permission to spend. You move from a state of anxious preservation to a state of confident oversight, knowing your legacy and your daily comfort are both mathematically secure.
Defining the Lifestyle Pillars: Health, Social, and Purpose
Wealth is a tool. It serves three non-financial pillars: health, social connection, and purpose. While generic industry figures suggest a "comfortable" retirement for a couple costs roughly A$78,566 per year, these benchmarks often fall short for residents in the Sutherland Shire. High-quality private health cover, premium wellness memberships, and the rising costs of specialist care in Sydney require a more sophisticated approach to funding your retirement lifestyle Australia. Purpose acts as a crucial buffer against the cognitive decline and boredom that can follow a high-pressure career. It provides a reason to engage with the world, turning "spare time" into "meaningful time" through volunteering, mentoring, or pursuing long-held passions.
Health as Your Primary Asset
Health is your foundation. Without it, your capital loses its utility. We categorise retirement into three distinct phases: the 'Go-Go' years of active travel, the 'Slow-Go' years where activity moderates, and the 'No-Go' years requiring higher levels of support. Proper Services Australia retirement planning involves more than just checking eligibility; it requires integrating preventative health costs and active lifestyle expenses into your long-term projections. By modelling these phases with precision, we ensure your portfolio remains sustainable even as medical inflation outpaces general CPI. This bespoke investment advice ensures you have the resources for the best care when you need it most, providing a sense of quiet certainty for you and your family.
Social Connection and Legacy
Isolation is a significant risk. For those moving away from a busy office environment in the CBD, the loss of daily interaction can be jarring. Maintaining social proximity to community hubs in Miranda or the CBD provides a vital sense of belonging and intellectual stimulation. Many retirees now prefer a strategy of 'Giving While Living'. This involves funding family experiences, assisting grandchildren with education, or helping with property deposits today, rather than relying on traditional estate planning that only triggers at the end of life. This shift requires a tax-effective withdrawal strategy that balances your own longevity with your desire to create a living legacy. To ensure your capital supports these pillars, consider a bespoke retirement review that looks beyond the numbers to your actual daily life.
Aligning Your Financial Engine with Your Lifestyle Vision
Transitioning from vision to reality requires a robust financial engine. Technical mechanisms provide the transport. Precision is paramount. This is why tax planning for retirement Australia is a critical focus for 2026. For high-net-worth individuals, the goal is to harmonise complex regulations with a low-volatility income stream. While industry funds offer simplicity, many Sydney professionals find that a Self-Managed Super Fund (SMSF) provides the bespoke control necessary for sophisticated portfolio construction. To manage the tension between immediate needs and long-term longevity, we often employ the "Bucket Strategy."
- Cash Bucket: Two to three years of living expenses held in liquid, low-risk accounts.
- Defensive Bucket: Medium-term funds held in fixed interest and bonds to provide stability.
- Growth Bucket: Long-term capital held in equities and property to combat inflation.
Funding your retirement lifestyle Australia is about ensuring these buckets are always replenished through disciplined rebalancing. It replaces the anxiety of market timing with a structured, logical flow of capital.
Optimising Superannuation for Income
Your superannuation must evolve. During your career, the focus was growth; now, the priority is sustainable income. For those still working in Sydney, a Transition to Retirement (TTR) strategy can be an effective way to boost your balance while reducing tax. We also look at strategic re-contribution. By withdrawing and re-contributing funds within the A$130,000 non-concessional cap, you can often reduce the future tax burden for your adult beneficiaries. It's about protecting your legacy while you enjoy your present.
Centrelink Structuring and the Age Pension
Entitlements are often overlooked. Even for those with significant assets, understanding the 2026 asset test thresholds is vital. For instance, a couple who are homeowners can have up to A$499,000 in assessable assets and still qualify for a full pension. Strategic gifting or investing in specific products can often improve your position. With deeming rates under constant review in 2026, structured modelling ensures you don't miss out on valuable concessions like the Commonwealth Seniors Health Card, which now has higher income thresholds of A$101,105 for singles.
Tax-Effective Income Streams
Downsizing offers a unique opportunity. Selling a large family home in Sydney can unlock significant capital, but it also triggers complex Capital Gains Tax (CGT) considerations. Utilising the downsizer contribution rules allows you to inject up to A$300,000 per person into super outside the usual caps. Combined with franking credits from Australian shares, this creates a highly efficient income stream. Seeking professional superannuation advice Sutherland Shire ensures these moving parts work in unison, replacing complexity with a structured path.
Stress-Testing the Dream: Managing Longevity and Inflation
Confidence requires evidence. While your vision defines the destination, stress-testing ensures you have the endurance to reach it. Market volatility is an inevitability, not an anomaly. For those funding your retirement lifestyle Australia, the dual pressures of Sydney's cost of living and 2026 inflation can feel like a silent erosion of your hard-earned capital. Longevity risk, the very real possibility of outliving your wealth by age 95, requires a shift from simple growth to sophisticated wealth preservation strategies. It is about building a portfolio that is not just robust, but resilient.
The Sequence of Returns Risk
Timing is everything. The first five years of your retirement are mathematically the most dangerous for your capital. If the market experiences a significant downturn just as you begin your withdrawal phase, the "Sequence of Returns Risk" can permanently impair your portfolio's ability to recover. Selling assets when prices are depressed forces you to liquidate more units to meet your income needs, which accelerates capital depletion. Our research-driven Investment Committee manages this by maintaining a disciplined cash buffer and using low-volatility modelling. This approach ensures you never have to sell growth assets during a market trough, protecting your long-term sustainability through quiet, logical order.
Longevity and Inflation Protection
Planning for a 30-year horizon in a high-cost city like Sydney demands precision. Static withdrawal rates are no longer sufficient in 2026. To maintain your purchasing power, your portfolio must include real assets and inflation-linked bonds that move in tandem with rising costs. We also factor in the "hidden" expenses of later life, such as the rising costs of aged care and specialist health services. By modelling these variables early, we establish a sustainable withdrawal rate that provides for your current lifestyle while securing your future care. If you want to ensure your capital is truly protected against the unknown, you can request a portfolio sustainability stress-test today.
Navigating Your Future with Precision Modelling
Clarity is the antidote to anxiety. Successful retirement planning Sydney is a sophisticated blend of art and science. It requires the creative vision to design your ideal week and the mathematical rigour to ensure that vision is sustainable. While generic online calculators offer a basic estimate, they lack the strategic depth needed for funding your retirement lifestyle Australia in a complex regulatory environment. True North Lifestyle uses bespoke long-term projections to move you from a state of hopeful estimation to one of quiet certainty. By integrating your lifestyle goals with rigorous data, funding your retirement lifestyle Australia becomes a structured process rather than a guessing game.
The True North Modelling Process
Precision brings order. We transform your personal aspirations into a 30-year cash-flow simulation. This process begins with your "ideal week" exercise, which we then stress-test against various economic scenarios. In 2026, legislative changes, such as the scheduled 12% Superannuation Guarantee rate and shifting Centrelink thresholds, mean that a static plan is no longer sufficient. Regular reviews are essential to adjust your strategy as the landscape evolves. This methodical approach allows you to move from "I think I can retire" to "I know I can retire," providing the emotional reassurance that your capital is optimised for longevity.
Taking the First Step in Miranda
Your journey towards a structured future begins with a bespoke retirement strategy consultation. As an independent, fee-for-service financial adviser in Miranda, we prioritise transparency and objective advice. Our Miranda-based team possesses a deep understanding of the local Sutherland Shire market, from property trends to the lifestyle expectations of our community. During our consultation, we do the heavy lifting of technical analysis so you can step into a role of confident oversight. It is time to replace uncertainty with a well-defined path. Seek the quiet certainty of a professional guide and ensure your legacy is as secure as your daily comfort.
Step Into Your Future with Quiet Certainty
True confidence in retirement isn't found in a spreadsheet alone. It's found in the harmony between your personal vision and the technical mechanisms that support it. By addressing the identity gap and stress-testing your portfolio against 2026 inflation, you ensure that your wealth preservation is as disciplined as your career was. Funding your retirement lifestyle Australia is a journey that requires an authoritative guide who understands both the numbers and the human outcome.
Our team provides research-driven Investment Committee oversight and no-nonsense, evidence-based financial advice. As specialists in Sutherland Shire and Sydney CBD retirement strategies, we move beyond generic calculators to provide a bespoke roadmap tailored to your specific aspirations. You've spent decades doing the heavy lifting of accumulation. Now, it's time to step into a role of confident oversight. To secure your legacy and gain the genuine permission to spend, book a bespoke retirement modelling session with our Miranda team today. Your new chapter deserves a well-defined path and a steady navigator.
Frequently Asked Questions
What is the most important factor in funding a retirement lifestyle?
The most important factor is the precise integration of your personal lifestyle vision with rigorous financial modelling. Without this alignment, you risk either outliving your capital or, conversely, living with unnecessary frugality because you lack the "permission to spend." True confidence comes from knowing your daily rhythm is supported by a stable, stress-tested mathematical foundation.
How much superannuation do I need for a comfortable lifestyle in Sydney in 2026?
A "comfortable" lifestyle in Sydney typically requires a higher balance than national benchmarks. While industry figures often suggest roughly A$78,566 per year for a couple, Sydney's property costs and medical inflation mean your target should be bespoke. Funding your retirement lifestyle Australia in a high-cost city requires a plan that accounts for local cost-of-living pressures and 2026 inflation rates.
What is the sequence of returns risk and why does it matter for new retirees?
Sequence of returns risk is the danger that a market downturn occurs in the first five years of your retirement. This matters because withdrawing income from a declining portfolio accelerates capital depletion, making it difficult for your balance to recover. Protecting against this requires a structured cash buffer and a low-volatility investment approach to avoid selling growth assets at the bottom of a market cycle.
Can I still get the Age Pension if I have a self-managed super fund (SMSF)?
You can definitely receive the Age Pension while managing an SMSF. Eligibility is determined by the Services Australia income and assets tests, not by the specific structure of your superannuation. For 2026, a couple who are homeowners can have up to A$499,000 in assessable assets to qualify for a full pension, regardless of whether those assets are held in an industry fund or an SMSF.
How often should I update my retirement lifestyle model?
You should update your retirement model at least once a year to ensure it remains accurate. Regular reviews allow you to adjust for 2026 legislative shifts, such as the increase in the Superannuation Guarantee to 12% or changes to the Commonwealth Seniors Health Card income thresholds. This disciplined oversight replaces the anxiety of the unknown with a sense of quiet certainty.
What are the most common mistakes when funding a retirement in Australia?
The most common mistakes include neglecting the psychological "Identity Gap" and failing to plan for the "Slow-Go" and "No-Go" years. Many retirees also focus too heavily on accumulation and struggle with the transition to spending their capital. This lack of a decumulation strategy can lead to missed opportunities for creating a living legacy or enjoying the travel experiences you've worked decades to afford.
How does inflation impact my retirement withdrawal strategy in 2026?
Inflation in 2026 erodes your purchasing power, meaning your withdrawal strategy must be dynamic rather than static. To protect your real income, your portfolio should include assets that hedge against rising costs, such as Australian shares with franking credits or inflation-linked bonds. This ensures funding your retirement lifestyle Australia remains sustainable even if the cost of specialist healthcare or local services increases over a 30-year horizon.
Is it better to pay off my mortgage or contribute more to super before I retire?
Deciding between mortgage reduction and superannuation contributions depends on your individual tax bracket and the current interest rate environment. Often, the tax benefits of concessional contributions, up to the A$32,500 cap, provide a higher net benefit than debt repayment. However, entering retirement debt-free offers a significant psychological advantage and a sense of order that many Sydney professionals value above marginal gains.


