

Retiring in Sydney is no longer a matter of simply reaching a savings milestone; it is an exercise in managing a high-velocity economic environment that demands absolute precision. For those seeking professional financial advice for retirees Sydney presents a unique set of challenges, from the persistent pressure of living costs to the intricate shifts in superannuation laws as we move through 2026. You have worked hard to build your nest egg, yet it's natural to feel a sense of unease when faced with market volatility or the complex sequence of returns risk that can impact your early retirement years.
True stability is found in clarity. We understand that you want more than just a spreadsheet; you want the confidence that your lifestyle is secure and your legacy is protected. This article explores how bespoke financial modelling and strategic planning can transform your wealth into a reliable, tax-optimised income stream. We will provide an overview of the tools used to create a visual roadmap of your financial future, ensuring your estate remains a pillar of strength for the next generation.
Key Takeaways
- Understand why Sydney’s unique property market and high cost of living necessitate a bespoke financial strategy rather than a generic industry fund approach.
- Discover how dynamic retirement modelling replaces static spreadsheets to provide a clear, visual roadmap of your capital and cash flow throughout your later years.
- Learn to navigate the 2026 Superannuation Guarantee changes and implement tax-optimisation strategies while seeking professional financial advice for retirees Sydney residents can trust.
- Identify the critical risks of sequence of returns and longevity, ensuring your portfolio is structured to withstand market volatility and outlast your retirement.
- Gain a step-by-step understanding of the consultation process that moves you from financial uncertainty toward a disciplined, research-backed path for your estate.
Why Retirement Planning in Sydney Requires a Bespoke Approach
Sydney is unique. The economic rhythm of this city operates at a different frequency than the rest of the country. For those seeking financial advice for retirees Sydney presents a specific set of variables that national averages simply cannot capture. High property values and an elevated cost of living create a landscape where traditional rules of thumb often fall short. We frequently see residents in the Sutherland Shire who are asset rich but cash poor, holding significant equity in a family home while facing constraints on their daily liquid cash flow.
Localised insight matters. Whether you are consulting with us in Miranda or our CBD office, your strategy must reflect the reality of your postcodes. Generic national calculators fail because they are built for a median that doesn't exist in Sydney. They don't account for the specific lifestyle expectations of a Shire local or the higher price of services in the city. A bespoke approach moves beyond these generalities to provide a disciplined, research-driven model tailored to your actual environment.
The Property Factor: Downsizing and Rightsizing in Sydney
Property remains central. For many, the decision to sell a long-held family home in the Shire is both emotional and financial. Rightsizing offers a path to unlock equity, but the timing and execution are critical. You must navigate the specific tax implications of downsizer contributions within the framework of superannuation in Australia. These strategies allow you to shift wealth into a more tax-effective environment, yet they must be balanced against the need for accessible capital. Evaluating the financial impact of a sale requires a comprehensive model that considers your long-term liquidity alongside your desire for a comfortable home.
Cost of Lifestyle: Maintaining Standard in a High-Inflation Environment
Living costs vary. Sydney-specific healthcare, leisure, and maintenance expenses are consistently higher than the national average. In 2026, the necessity for inflation-adjusted projections has never been more apparent. A standard budget is a risk to your longevity if it doesn't account for these local premiums. By using bespoke financial advice for retirees Sydney residents can ensure their capital is managed with a focus on low volatility and sustainable income, protecting their lifestyle for the decades ahead. We focus on the human outcome, ensuring your wealth preservation strategy is as robust as the city you call home.
The Science of Retirement Modelling: Mapping Your Financial Future
Retirement is not a static destination. It is a dynamic, multi-decade journey that requires more than a simple spreadsheet or a basic online calculator. For many, the transition from accumulating wealth to drawing an income triggers a deep sense of unease. Logic replaces fear when you move toward a research-driven approach. Professional modelling serves as a sophisticated simulation of your financial life; it allows us to project how your capital will behave under a vast array of different conditions. This is the "Steady Navigator" philosophy in practice. We aim to replace the inherent anxiety of the unknown with the quiet certainty of a structured plan.
Clarity provides freedom. One of the most significant benefits of high-level modelling is that it grants you the "permission to spend." When you can see a visual representation of your financial longevity, you no longer have to live in a state of perpetual frugality out of fear. You can enjoy your lifestyle in the CBD or the Shire, knowing exactly how each holiday or renovation impacts your long-term position. This is the standard of financial advice for retirees Sydney residents should expect, moving beyond vague promises toward evidence-based outcomes.
Cash Flow Modelling vs. Simple Projections
Simple projections often assume a linear rate of return, which rarely occurs in the real world. True cash flow modelling is far more granular. It examines the complex interaction between your various assets, tax-optimised income streams, and shifting expenditure patterns over time. We use these tools to visualise "what-if" scenarios, such as the impact of a significant market downturn or an unexpected health event. This level of retirement planning Sydney locals utilise creates a robust roadmap for longevity. When you are Choosing a financial adviser, it is essential to ensure they employ these dynamic simulations rather than static guesses.
Stress Testing Your Portfolio for 2026 and Beyond
Stability is built on rigour. We identify vulnerabilities in your current investment structure by looking at how it would have performed during past economic crises. Stress testing is a rigorous check against historical market volatility to ensure your plan can withstand real-world shocks without compromising your lifestyle. Our in-house Investment Committee uses this data to construct resilient, bespoke portfolios that focus on low volatility. By engaging with professional retirement modelling, you ensure that your strategy is not just a hope for the best, but a disciplined construction designed for the long haul. This methodical process is the cornerstone of providing effective financial advice for retirees Sydney families can rely on for generations.
Optimising Superannuation and Tax Strategies for NSW Retirees
Efficiency is paramount. Your superannuation is the engine of your retirement, yet many Sydney professionals reach the finish line with a structure that isn't firing on all cylinders. While industry funds serve a purpose during the accumulation phase, they often lack the tactical flexibility required for a sophisticated draw-down strategy. Moving toward a bespoke portfolio allows for a more granular level of control, particularly as we navigate the 2026-27 financial year where the Superannuation Guarantee rate has reached 12%. This increase highlights the growing importance of professional financial advice for retirees Sydney wide to ensure every dollar is working toward your long-term longevity.
Tax is not a fixed cost. It is a variable that can be managed with the right structural logic. One powerful tool in our arsenal is the re-contribution strategy. By withdrawing and then re-contributing funds into your super, we can effectively convert taxable components into tax-free components. This doesn't just benefit you today; it serves as a critical shield for your beneficiaries, significantly reducing the tax burden your adult children might otherwise face on their inheritance. It’s a disciplined approach to wealth preservation that ensures your legacy remains intact. With concessional contribution caps now at $32,500 and non-concessional caps at $130,000, the opportunity to refine your position has never been more significant.
Superannuation Review and Optimisation
Performance matters. We begin by evaluating the fee structures and investment performance of your current funds to identify where value is being lost. For local professionals, seeking superannuation advice Sutherland Shire is essential to align your portfolio with the high-cost reality of Sydney living. If you are still active in the CBD, we may look at Transition to Retirement (TTR) strategies. These allow you to access a portion of your super while still working, providing a tax-effective way to bolster your income or further reduce your debt before you fully step away from the workforce.
Centrelink Structuring and Entitlements
Logic replaces confusion. Navigating Centrelink can feel overwhelming, but strategic asset structuring can often improve your eligibility for the Age Pension. As of July 2026, the asset test threshold for a single homeowner is $333,000, while the couple homeowner threshold sits at $499,000. We look at gifting rules, which allow for $10,000 per year or $30,000 over five years, to ensure you don't inadvertently trigger a penalty. By aligning your assets with the 2026 income and asset tests, we help you secure the entitlements you've earned, providing an additional layer of stability within the broader framework of financial advice for retirees Sydney families rely on.
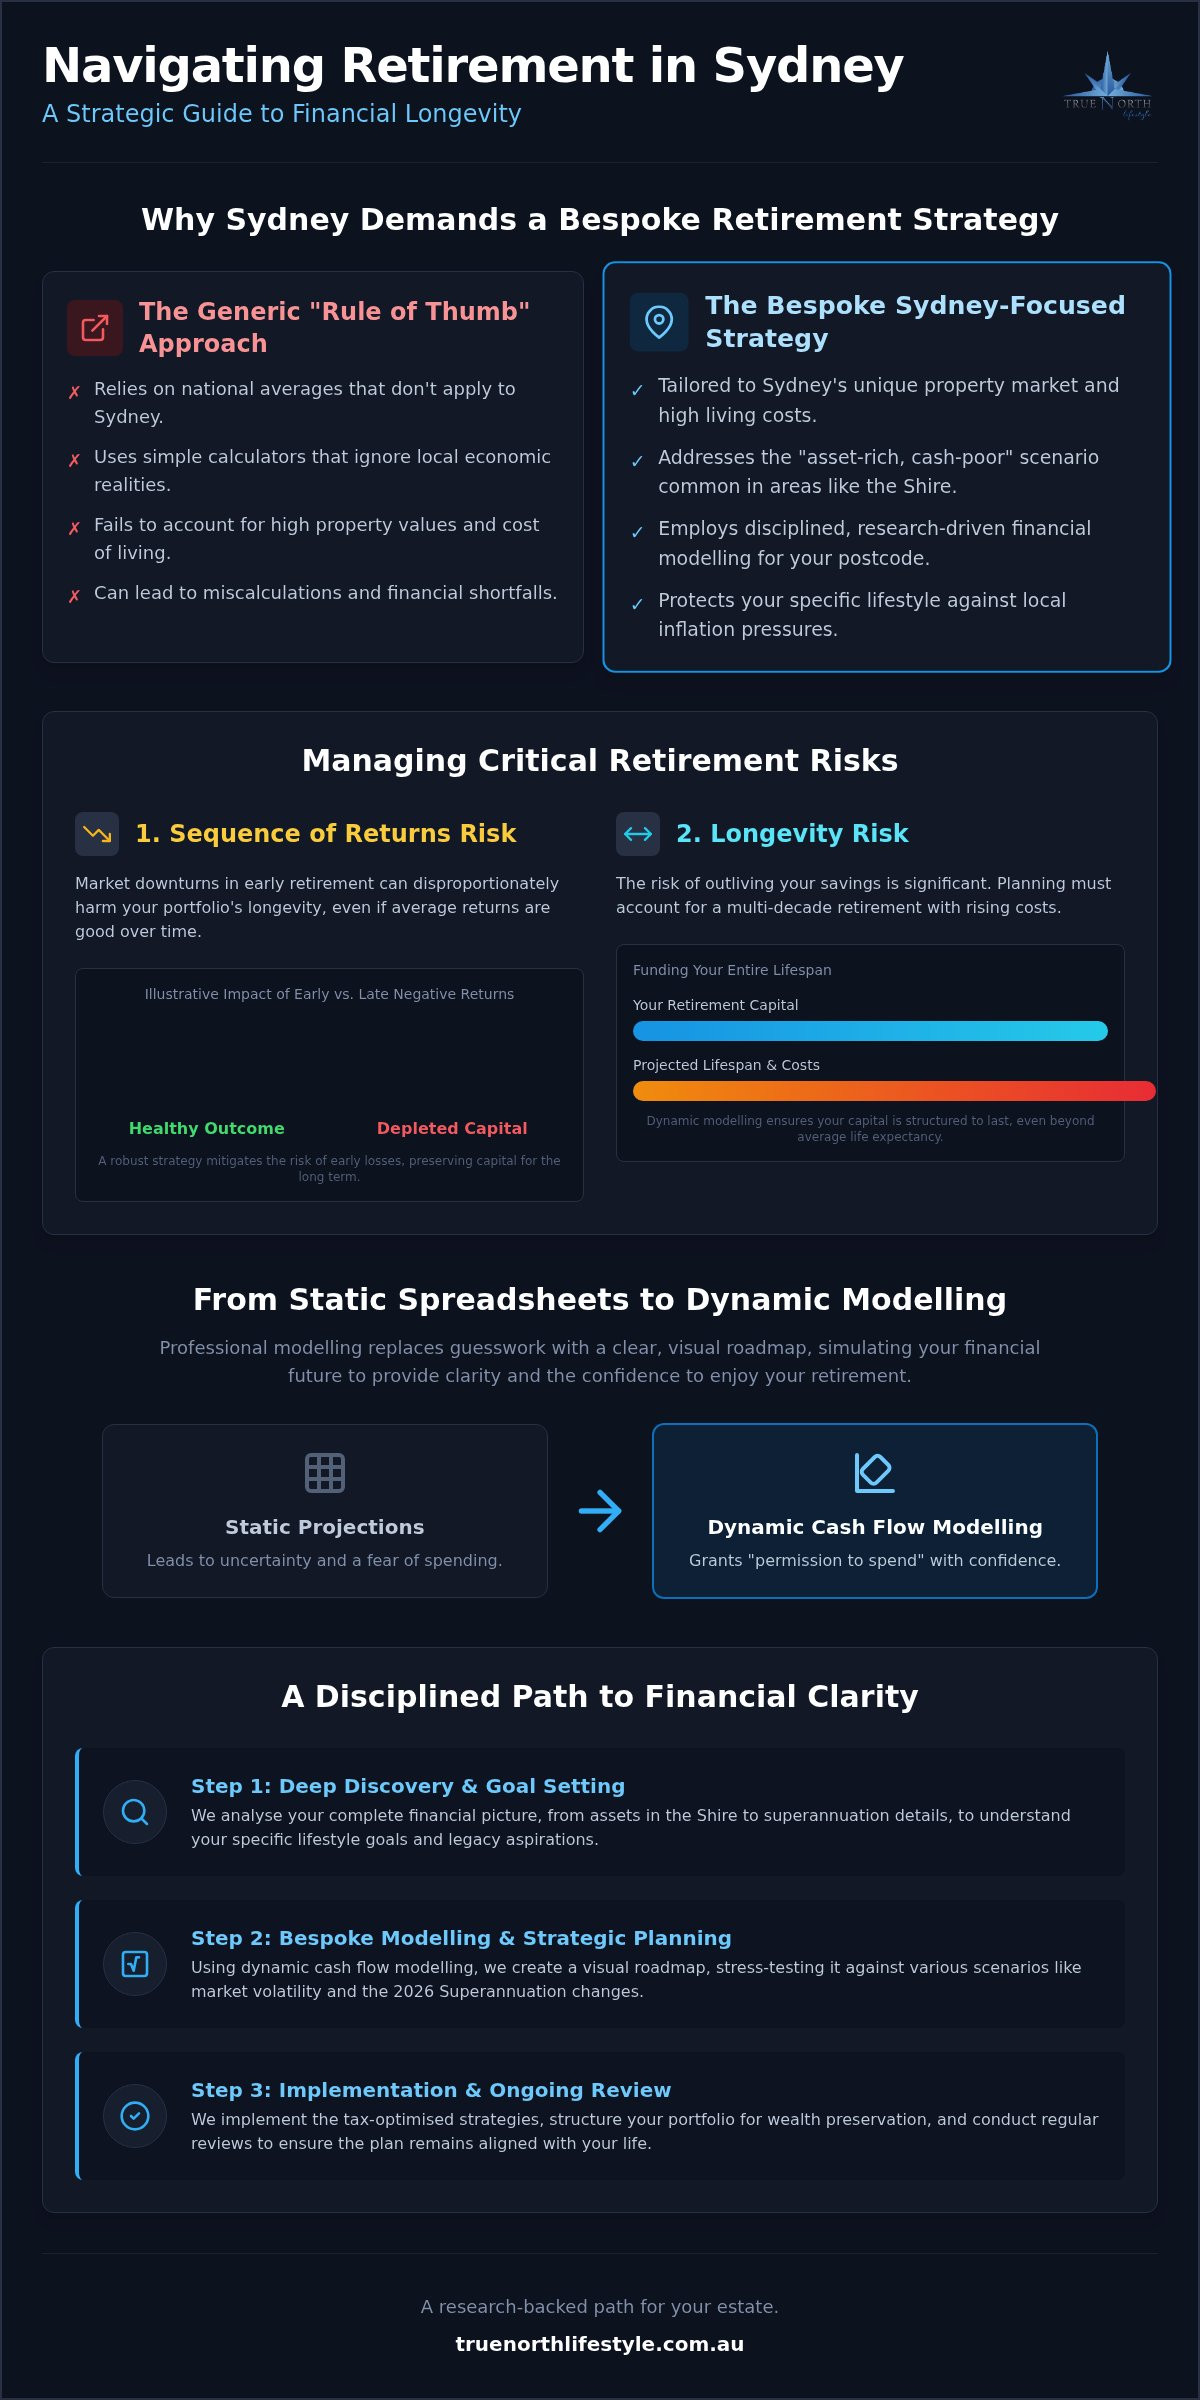
Wealth Preservation: Managing Sequence of Returns and Longevity Risk
Preservation is the priority. Once you transition into retirement, the focus shifts from the aggressive pursuit of growth to the disciplined protection of your capital. For those seeking financial advice for retirees Sydney residents must account for the specific risk that the timing of their retirement poses to their long-term wealth. This is known as sequence of returns risk. It is the danger that a market downturn occurs exactly when you begin drawing from your portfolio, potentially depleting your assets faster than they can recover. Strategic wealth preservation strategies act as an anchor in these fluctuating markets, ensuring your lifestyle isn't compromised by short-term volatility.
Longevity is the other side of the coin. With Australians living longer, your capital must often sustain a retirement lasting thirty years or more. In a high-cost environment like Sydney, the fear of outliving your money is a significant source of anxiety. We address this through low-volatility, income-focused investment strategies that prioritises sustainable cash flow over speculative gains. By building a plan grounded in real-world probability, we replace uncertainty with a sense of quiet order, allowing you to move forward with confidence.
The "Critical Zone": Protecting the Start of Your Retirement
Timing is everything. The first five years of your retirement are often referred to as the "Critical Zone" because your portfolio is at its most vulnerable to market shocks. For example, sequence of returns risk means that a 20% market decline in your first year of retirement, coupled with a standard 5% pension withdrawal, requires a subsequent 33% gain just to return to your starting balance. To mitigate this, we implement structures that prevent you from being a forced seller of assets during a market correction. This often involves maintaining a dedicated cash or liquid buffer, allowing your growth assets the time they need to recover without interrupting your lifestyle income.
Bespoke Portfolio Construction for Income
Structure dictates outcome. As you move away from the workforce, your asset allocation must reflect a shift from growth-focused to income-focused objectives. This is why bespoke investment advice Sydney is vital for capital stability. Our in-house Investment Committee manages these portfolios with a high degree of oversight, allowing for a rapid response to market shifts that generic industry funds simply cannot match. This research-driven methodology ensures your portfolio is constructed to produce reliable yields while minimising unnecessary risk. To see how a tailored approach can protect your capital, you can request a portfolio sustainability review with our team.
Partnering with a Sydney Financial Adviser: The Path to Clarity
Clarity is the ultimate outcome. By consolidating your various financial threads into a single, cohesive strategy, you replace the weight of constant decision-making with a sense of quiet oversight. When seeking professional financial advice for retirees Sydney residents often find that the transition from uncertainty to structure begins with a thorough, evidence-based consultation. This process isn't merely about numbers; it's a disciplined exploration of your lifestyle goals, family obligations, and the legacy you wish to leave behind. We move beyond the surface to understand what stability truly means for you, whether you are based in our Miranda office in the Sutherland Shire or our Sydney CBD location.
Retirement is a journey, not a destination. A "set and forget" approach is a significant risk in an environment as dynamic as Sydney's 2026 economic landscape. Ongoing advisory services ensure that your strategy remains aligned with shifting market conditions, legislative updates, and changes in your personal circumstances. We act as your steady navigator, doing the heavy lifting of research and portfolio construction so you can step into a role of confident oversight. This partnership provides the peace of mind that your wealth preservation is being managed with the same rigour and precision that you applied to building your career.
Estate Planning and Legacy Management
Legacy requires a plan. Integrating estate planning into your broader financial strategy ensures that your hard-earned assets are distributed exactly as you intended, without unnecessary tax leakage. For many Sydney families, implementing sophisticated wealth transfer strategies Australia is the key to protecting the next generation. We work to ensure your estate is structured tax-effectively, minimizing the burden on your beneficiaries while maximizing the impact of your life's work. It's about more than just a will; it's about creating a structured path for your family's future financial strength.
Your Next Steps to Retirement Confidence
Confidence begins with action. Identifying the gaps in your current arrangements is the first step toward securing your future. Whether you're concerned about sequence of returns risk or the complexity of current superannuation laws, early engagement with a specialist allows for a more robust and flexible plan. Don't leave your lifestyle to chance in a fluctuating market. You can secure your financial future and gain the clarity you deserve by requesting a comprehensive retirement strategy from True North Lifestyle. Our team is ready to help you map out a well-defined path toward a stable and fulfilling retirement in the city you love.
Your Path to a Structured Financial Future
Retirement should be a period of quiet certainty. By moving away from generic projections and embracing bespoke retirement modelling, you gain a clear, visual roadmap of your financial future. We have explored how strategic superannuation reviews and tax-optimised income streams can protect your capital from the high cost of living and the complexities of 2026 regulations. True stability is not found in luck; it is constructed through the disciplined, research-driven methodology of our in-house Investment Committee.
Whether you are visiting our Miranda office or our Sydney CBD centre, you deserve a plan that treats your lifestyle as a non-negotiable priority. For those seeking expert financial advice for retirees Sydney offers many choices, but few provide the rigorous stress testing and longevity planning required for true peace of mind. Your legacy and your comfort are far too important to leave to chance.
Take the first step toward a well-defined path today. We invite you to Book a consultation with our Sydney retirement specialists to discover how our tailored strategies can secure your lifestyle. Step into your retirement with the confidence that you are well protected and understood.
Frequently Asked Questions
When is the best time to seek financial advice for retirement in Sydney?
Seeking advice five to ten years before your planned retirement is the ideal window. This timeframe allows for structural changes that simply aren't possible once you have stopped working. By engaging with our team early, we can implement tax-effective strategies and debt reduction plans that provide a much smoother transition. It gives you the necessary runway to refine your superannuation and align your assets with your future goals.
How much do I need to retire comfortably in Sydney in 2026?
Your retirement "number" is entirely dependent on your desired lifestyle in a high-cost environment like Sydney. While industry benchmarks provide a basic starting point, the city's property and leisure costs usually demand a more substantial capital base. We use dynamic modelling to calculate a specific target that ensures your capital outlives your retirement. This research-driven approach replaces generic guesses with a structured, visual roadmap of your financial future.
What is the difference between a generic super fund and a bespoke investment portfolio?
Generic industry funds use a "one-size-fits-all" approach that lacks tactical precision. In contrast, a bespoke portfolio is managed by our in-house Investment Committee to focus on low volatility and tax minimisation. This tailored construction provides the flexibility needed to protect your wealth in fluctuating environments. It moves beyond simple accumulation to provide a disciplined, income-focused strategy that is specifically designed for your unique lifestyle and legacy requirements.
Can a financial adviser help me maximise my Centrelink Age Pension?
Strategic asset structuring can often improve your eligibility for the Age Pension. Professional financial advice for retirees Sydney residents ensures your assets are aligned with the 2026 income and asset tests. We help you navigate gifting rules and valuation shifts to secure the entitlements you have earned over your working life. It's about replacing confusion with a sense of quiet order, ensuring your government support is optimised within your broader plan.
What are the main risks to my retirement savings in the current economic climate?
Sequence of returns risk and longevity risk are the most significant threats to your stability in 2026. A poorly timed market downturn in your early retirement years can have a devastating impact on your long-term capital. We mitigate these risks through rigorous stress testing and resilient portfolio construction that focuses on capital preservation. This methodical approach ensures your wealth can withstand market shocks while continuing to provide a reliable, tax-effective income stream.
How does retirement modelling differ from a standard financial plan?
A standard financial plan is often a static document; retirement modelling is a dynamic simulation. Modelling allows us to project your financial life across thousands of scenarios, including market crashes or health events. This provides a visual roadmap that gives you the "permission to spend" with absolute confidence. It replaces the inherent anxiety of the unknown with structured logic, allowing you to see exactly how your capital will behave over several decades.
Is the re-contribution strategy suitable for Sydney couples with high super balances?
This strategy is particularly effective for Sydney couples looking to protect their legacy. By converting taxable components of your super into tax-free ones, you can significantly reduce the future tax burden on your adult beneficiaries. It is a sophisticated wealth preservation tool that ensures your hard-earned assets are transferred to the next generation as efficiently as possible. We examine your specific balances to ensure this approach aligns with your overall estate planning strategy.
Why should I choose a financial planner in Miranda or Sydney CBD?
Localised insight is essential for effective retirement planning. Our Miranda office understands the unique property market and lifestyle dynamics of the Sutherland Shire, while our CBD location serves the city's professional community. We provide a steady, authoritative presence in the communities where our clients live and work. Choosing a local specialist means you have a partner who understands the specific economic rhythm of Sydney and is readily available for face-to-face consultations.


