

Your superannuation is not a static savings account; it is a sophisticated structural tool that requires active, strategic modelling to sustain a thirty-year retirement. It's completely understandable if the legislated changes for 2026, including the updated $32,500 concessional cap and the new Division 296 tax thresholds, have left you feeling more uncertain than empowered. You likely want the quiet certainty that your hard-earned wealth is protected from eroding fees and market turbulence. While consolidating superannuation funds Australia is an essential first step to streamline your finances, the real transformation happens when you apply research-driven oversight to your entire portfolio.
This guide provides a clear, professional roadmap to help you move from passive saving to active wealth preservation. We'll explore how to minimise your tax burden, navigate the latest regulatory shifts, and build a bespoke portfolio that matches your specific risk profile and lifestyle aspirations. By moving beyond a "set and forget" mentality, you can transform your fund into a high-performance engine that provides the stability you deserve in your later years.
Key Takeaways
- Master the 2026 contribution landscape by leveraging the updated $32,500 concessional cap and strategic non-concessional limits to accelerate your wealth building.
- Identify the most efficient pathway for consolidating superannuation funds Australia to eliminate unnecessary fee leakage and ensure your insurance cover remains cost-effective.
- Align your asset allocation with sophisticated retirement modelling to protect your balance from market volatility while maintaining long-term portfolio sustainability.
- Evaluate the structural merits of SMSF, industry, and retail funds using a clear framework focused on your specific balance and desired level of administrative control.
- Integrate advanced Transition to Retirement (TTR) and estate planning strategies to create a seamless, tax-optimised bridge between your working life and a confident retirement.
Why Professional Superannuation Advice is Critical in 2026
Managing wealth in 2026 requires a level of precision that default fund structures simply cannot provide. The Australian retirement system has matured into a complex ecosystem, with total assets exceeding A$4.7 trillion. While Superannuation in Australia was once a "set and forget" safety net, it's now a primary vehicle for sophisticated wealth preservation. For high-net-worth individuals, the standard "Balanced" investment option often fails to account for specific tax positions or long-term longevity risks. It's a blunt instrument in an environment that demands a scalpel. Professional advice ensures your fund isn't just growing, but is also structurally sound and protected from legislative erosion.
Many individuals begin their journey by consolidating superannuation funds Australia to reduce unnecessary fee duplication and administrative clutter. This is a logical starting point, yet consolidation alone isn't a strategy. True optimisation involves aligning your fund with your broader financial architecture. Without a bespoke approach, you risk eroding your balance through inefficient tax structures or investment allocations that don't reflect your actual risk tolerance. Professional guidance transforms these fragmented accounts into a cohesive, high-performance engine designed for your specific future.
Navigating the 2026 Regulatory Environment
Compliance is non-negotiable. As of July 2026, the Superannuation Guarantee rate has reached its legislated 12% peak. This increase, combined with the new "Payday Super" requirements, changes the rhythm of contribution modelling for Sydney professionals. You must also account for the Division 296 tax, which applies an additional 15% to earnings on balances exceeding A$3 million. Staying ahead of these ATO updates is essential to avoid punitive measures and ensure your estate planning strategy Australia remains effective and tax-minimised.
The "Steady Navigator" Approach to Retirement
Order replaces anxiety. At True North Lifestyle, we act as your steady navigator through these shifting tides. We prioritise human outcomes over raw performance percentages because a high return is meaningless if it doesn't support your desired lifestyle. For residents in Miranda and the Sutherland Shire, having local expertise means your strategy is built on a deep understanding of the Sydney cost-of-living landscape. We replace the noise of market volatility with the quiet certainty of a structured, evidence-based plan. This professional oversight allows you to step back from the technical burden and focus on the retirement you've earned.
The Three Pillars of Strategic Superannuation Optimisation
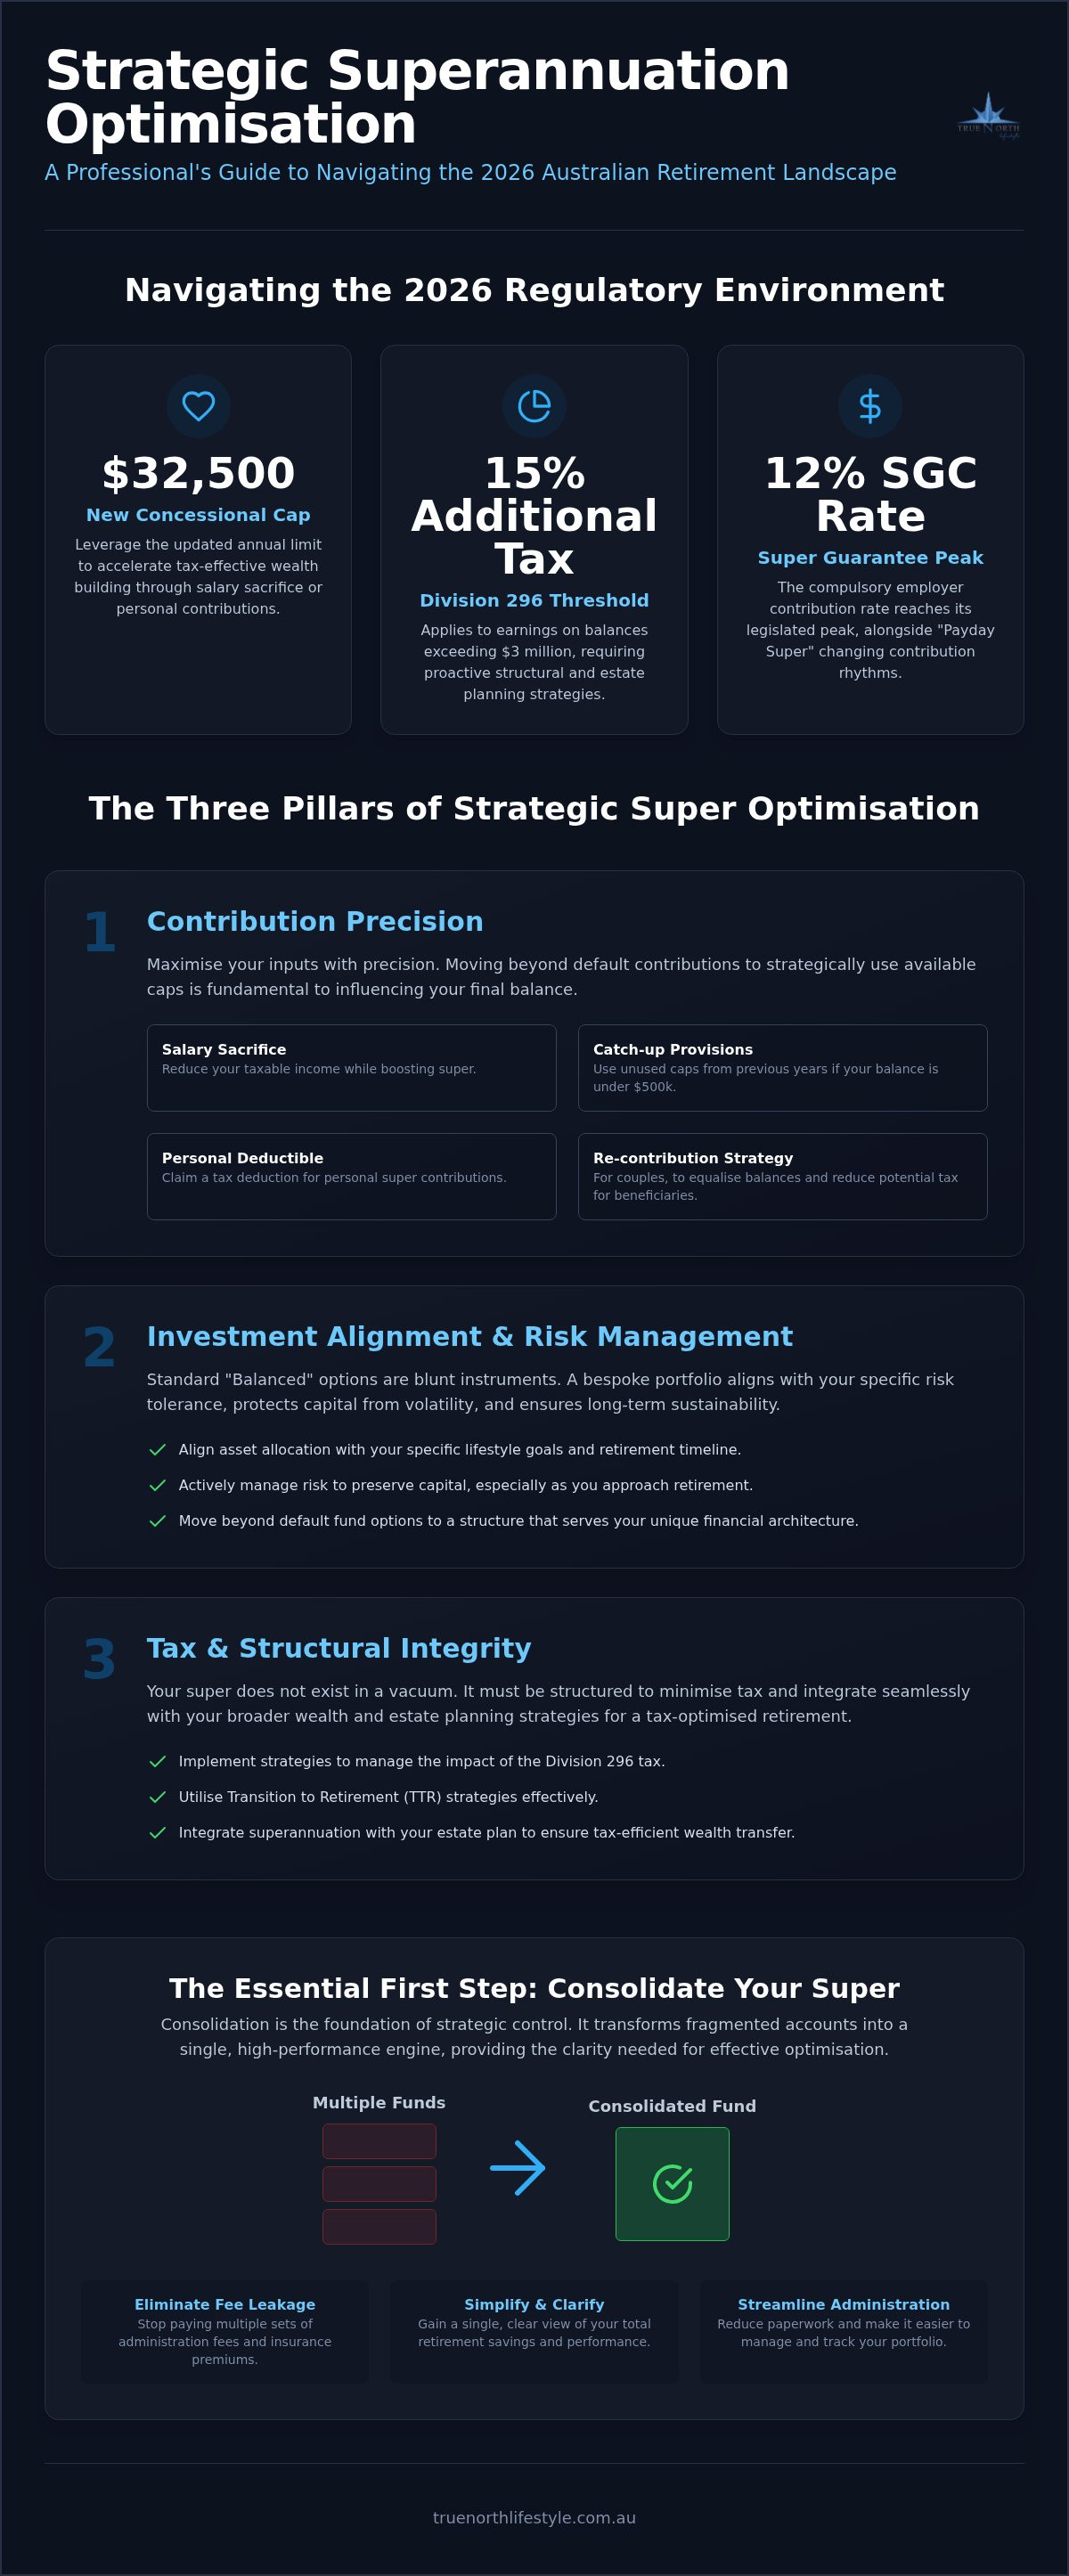
True optimisation rests on three critical pillars: contribution precision, investment alignment, and tax structural integrity. Your super shouldn't exist in a vacuum. It must work in harmony with your external investment portfolios to ensure your total wealth is utilised efficiently. The process of consolidating superannuation funds Australia serves as the structural foundation, but the true value lies in the strategic architecture built upon that base. By consolidating your super, you eliminate the friction of multiple fees and gain a clear view of your starting point. Strategy provides order. Without a clear framework, your retirement savings are left to the whims of market volatility and legislative shifts.
Maximising Contributions for Long-Term Growth
Influencing your final balance starts with contribution precision. For the 2026 financial year, the concessional contribution cap is A$32,500. You might choose to use salary sacrifice or personal deductible contributions to reach this limit, depending on your specific tax position. If your total super balance was below A$500,000 on 30 June of the previous year, you could also utilise catch-up provisions to boost your savings during your peak earning years. For couples, a re-contribution strategy can be particularly effective. This involves withdrawing funds and re-contributing them as non-concessional amounts, which helps equalise balances and can significantly reduce the potential "death tax" paid by non-dependant beneficiaries in the future.
Portfolio Construction and Risk Management
Preservation becomes paramount as you approach your retirement date. While consolidating superannuation funds Australia helps with fee reduction, it is your asset allocation that manages longevity. High-volatility assets that served you well in your 40s may introduce unacceptable risk in your 60s. This transition requires bespoke investment advice Sydney to ensure your portfolio matches your risk profile. Our in-house Investment Committee focuses on managing downside risk, prioritising stability over speculative gains. We lean toward income-focused assets that provide reliable cash flow, ensuring your portfolio remains sustainable for decades. Considering how these pillars fit into your personal journey is the first step toward a structured retirement plan that offers quiet certainty.
Comparing Super Structures: SMSF vs Industry vs Retail Funds
Choosing the right vehicle is as critical as the fuel you put in it. While consolidating superannuation funds Australia provides an immediate reduction in administrative clutter, the long-term sustainability of your retirement depends on selecting a structure that matches your specific balance and complexity requirements. Comparing Super Structures reveals that there's no universal "best" fund; rather, there's a "right" fund for your current life stage. Industry funds often serve as an excellent, low-cost baseline for many, yet they may lack the granular control required for high-net-worth individuals seeking deep tax-minimisation or custom asset allocation.
The decision to move beyond a default fund shouldn't be driven by hype, but by a methodical assessment of your needs. For those with significant balances, the administrative fees of a more complex structure are often outweighed by the strategic value of bespoke portfolio construction. It's about finding the point where the cost of the structure is justified by the increased probability of achieving your specific human outcomes.
Is an SMSF Right for Your Lifestyle?
Self-management offers the ultimate level of control. For local business owners in Miranda and the Sutherland Shire, a Self-Managed Super Fund (SMSF) provides the unique ability to hold direct business real property or unlisted assets that generic funds cannot accommodate. However, this control comes with a significant compliance burden. In 2026, the administrative and audit requirements are more rigorous than ever. You must weigh the cost-to-benefit ratio carefully. If your balance doesn't justify the fixed costs of an SMSF, or if the burden of being a trustee creates more anxiety than order, alternative structures may offer a more stabilising path.
The Wrap Account Advantage for Bespoke Portfolios
Retail wrap platforms bridge the gap between industry funds and SMSFs. These platforms function as a sophisticated administrative hub, allowing for precise asset modelling and transparent reporting that default options simply can't match. Professional advisers use wraps to construct truly bespoke portfolios, integrating specific shares, managed funds, and term deposits into a single, cohesive view. While administrative fees on these platforms may be higher than a standard industry fund, the strategic value lies in the customisation. It allows for a research-driven methodology where every asset is chosen for its specific role in your wealth preservation journey. This level of oversight provides the quiet certainty that your portfolio is being managed with the discipline of a professional investment committee, without the heavy lifting required by a self-managed structure.
How to Conduct a Comprehensive Superannuation Review
Clarity brings confidence. A truly comprehensive review moves beyond the annual statement. It begins with consolidating superannuation funds Australia to stop the silent erosion caused by multiple administration fees and redundant account-keeping charges. Once consolidated, you must assess your insurance cover with a critical eye. Many Australians are over-insured or, conversely, hold policies that have become inappropriately expensive as they age. By aligning your cover with your actual debt levels and family needs, you ensure premiums don't eat into your compound growth.
Benchmarking performance requires a sophisticated lens. Raw returns are a vanity metric; you need net-of-fee research to understand what actually remains in your account after all costs are deducted. We then move to stress-testing the portfolio. We model sequence-of-returns risk to ensure a market downturn in the years immediately preceding your retirement doesn't force a delay in your plans. This level of technical depth provides the quiet certainty that your strategy is built on evidence rather than optimism.
The Hidden Costs of Inaction
Legacy retail funds often harbour "fee creep," where small percentage increases or tiered fee structures quietly diminish your balance over time. By consolidating superannuation funds Australia, you simplify the audit process and make these hidden costs easier to identify. These expenses, combined with inappropriate insurance premiums, can lead to a shortfall of hundreds of thousands of dollars by the time you reach preservation age. Seeking superannuation advice Sutherland Shire ensures your review is conducted with local precision. We identify structural inefficiencies before they become catastrophic, allowing you to regain control over your financial trajectory.
Modelling Your Future Lifestyle
Balance tracking is a passive exercise that fails to account for future needs. Strategic retirement requires advanced cash flow modelling that translates a lump sum into a sustainable annual income. This process accounts for the unique pressures of living in Sydney, where inflation and the cost of maintaining a lifestyle in areas like the CBD or the Sutherland Shire are higher than national averages. Through professional retirement planning Sydney projections, we define your "enough" number. This definition provides the order and structure needed to transition from work to leisure without the fear of outliving your capital or compromising your standard of living.
If you're ready to move from uncertainty to a structured path, you can book a comprehensive superannuation review with our team today.
Bespoke Super Strategies: The True North Difference
A high-performance retirement engine requires more than just low fees; it demands a comprehensive integration of your entire financial life. While consolidating superannuation funds Australia provides the necessary structural clarity, the True North Lifestyle difference lies in how we weave that fund into your broader estate planning strategy Australia. This ensures your wealth isn't just accumulated, but is also effectively protected and eventually distributed according to your precise wishes. We move beyond the transactional nature of fund management to provide a stabilising influence on your family's long-term prosperity.
Our methodology includes sophisticated Centrelink structuring, which is often overlooked by generic providers. By carefully managing how your superannuation assets are assessed, we can often maximise your Age Pension entitlements, providing an additional layer of income security. This level of detail is particularly relevant for Sydney families navigating high cost-of-living environments, where every strategic advantage contributes to a more resilient retirement outcome. It's about creating order from complexity.
Transition to Retirement (TTR) Mastery
For those over the age of 60 in New South Wales, a Transition to Retirement strategy offers a powerful mechanism to boost savings without reducing take-home pay. By accessing a portion of your super as a pension while you continue to work, you can salary sacrifice more of your income into the low-tax super environment. This effectively reduces your personal income tax while accelerating your fund's growth in the final five years of your career. It's a delicate balance that must be integrated with broader wealth preservation strategies to ensure current lifestyle needs don't compromise your portfolio's longevity.
Securing Your Legacy
Crafting a legacy is about more than just the final balance. It's about certainty. Binding Death Benefit Nominations (BDBN) are essential tools to ensure your superannuation is paid directly to your intended beneficiaries, bypassing the potential delays of estate probate. For families with complex needs, we often explore the role of testamentary trusts to protect inherited wealth from excessive taxation or external claims. This bespoke modelling builds intergenerational stability, allowing you to pass on your hard-earned success with the confidence that it will be managed with the same discipline you applied during your working life. We act as your steady navigator, ensuring your wealth reaches the next generation intact and protected.
Securing Your Financial Future Through Strategic Action
Success in retirement is rarely the result of chance; it's the product of deliberate, research-driven decisions. We've explored how moving beyond a default fund and consolidating superannuation funds Australia can provide the structural clarity needed to withstand market volatility. By aligning your contributions with 2026 regulatory shifts and integrating bespoke portfolio construction, you transform a passive account into a high-performance engine. This methodical approach replaces the noise of financial uncertainty with the quiet certainty of a well-defined path.
Our team provides the local Sutherland Shire expertise and in-house Investment Committee oversight required to navigate these complexities. Through bespoke retirement modelling and detailed projections, we ensure your strategy is built on real-world probability rather than generic assumptions. You don't have to navigate this landscape alone. We invite you to book a strategic superannuation review with our Miranda team today. Take the first step toward a retirement defined by stability, order, and the freedom to enjoy the lifestyle you've worked so hard to build.
Frequently Asked Questions
How much superannuation advice do I actually need in 2026?
Advice needs vary based on your total balance and lifestyle goals. In 2026, the introduction of the Division 296 tax and the shift to Payday Super have added layers of technical complexity. You need enough advice to ensure your fund is structurally sound and compliant. Often, this begins with consolidating superannuation funds Australia to create a clear, single view of your retirement architecture before applying more advanced strategies.
Can a financial adviser help me choose between an industry fund and an SMSF?
A strategic adviser provides a methodical framework to evaluate which structure suits your specific needs. While industry funds offer a low-cost, simplified baseline, an SMSF provides unparalleled control over assets like direct business property in Miranda. We help you weigh the administrative compliance burden of an SMSF against the strategic benefits. This ensures you don't choose a structure that creates more stress than it solves.
What are the concessional contribution limits for the 2026 financial year?
For the 2026 financial year, the concessional contribution cap is set at A$32,500. This limit includes your employer's Superannuation Guarantee payments, which have now reached the legislated 12% rate. Understanding these caps is essential for high-income earners in Sydney who wish to maximise their tax-deductible contributions without triggering excess contribution penalties. It is about precision in your annual cash flow modelling to ensure long-term sustainability.
Is it worth consolidating my super if I have multiple small accounts?
Consolidating your super is almost always beneficial for reducing administrative friction. By consolidating superannuation funds Australia, you eliminate multiple sets of fees that quietly erode your compound growth over decades. It also simplifies your insurance audit, ensuring you aren't paying for redundant life or TPD policies across different accounts. This single-view approach brings immediate order to your retirement architecture and ensures your wealth preservation remains the primary focus.
How does professional superannuation advice impact my tax minimisation?
Strategic advice identifies tax-saving opportunities that generic funds often overlook. This includes implementing re-contribution strategies to reduce future tax for beneficiaries or using Transition to Retirement (TTR) pensions to lower your current taxable income. We focus on bespoke modelling to ensure your superannuation works in harmony with your broader wealth preservation goals. This approach provides the quiet certainty that your tax is legally minimised through research-driven methodology.
What happens to my superannuation if I retire in Sydney vs regionally?
The primary difference lies in the cash flow modelling required for different cost-of-living environments. Retiring in Sydney, particularly in areas like Miranda or the CBD, requires a more robust sustainable income stream compared to regional New South Wales. We use advanced projections to ensure your "enough" number accounts for Sydney's higher property costs and lifestyle expenses. Your strategy must be tailored to your specific geographic reality to remain viable.
Can I use my superannuation to help pay off my mortgage before I retire?
You generally cannot access superannuation to pay off a mortgage before reaching your preservation age, which is currently 60. However, a Transition to Retirement (TTR) strategy can be used to boost your cash flow while you're still working. This additional income can help settle debts more quickly as you approach your final retirement date. It's a sophisticated balancing act that requires careful risk management and portfolio sustainability modelling to execute correctly.
What is the "death tax" on super and how can I avoid it for my kids?
The "death tax" refers to the 15% tax plus Medicare levy paid on the taxable component of super when it's inherited by non-dependants, such as adult children. You can often avoid this through a re-contribution strategy, which involves withdrawing and re-contributing funds to increase the tax-free component. This proactive approach ensures more of your legacy reaches your family rather than the ATO, providing intergenerational stability for your loved ones.


