

What if the greatest threat to your financial freedom isn't a market downturn, but the silent "funding gap" waiting between your final day of work and your 60th birthday? For many successful professionals, early retirement planning Sydney often feels more like a source of persistent anxiety than a celebrated milestone. You likely recognise that Sydney's unique cost of living requires a more sophisticated approach than a standard savings plan. The fear that your capital might not sustain your lifestyle through decades of inflation is a heavy burden to carry alone.
We understand the weight of these decisions. This guide provides a research-driven framework to help you navigate the complexities of bridge funding, shifting superannuation laws, and long-term capital sustainability. You'll learn how to model a precise exit strategy that protects your lifestyle while minimising tax liabilities during your transition. We will explore how bespoke portfolio construction and rigorous cash flow projections can replace uncertainty with a sense of quiet, structured control. Your path to freedom deserves a map built on evidence, not guesswork.
Key Takeaways
- Understand the strategic hierarchy of spending needed to fund the "gap" between leaving work and accessing your superannuation.
- Discover how advanced superannuation optimisation and re-contribution strategies can protect your capital and minimise future tax for beneficiaries.
- Learn to mitigate "silent killers" like sequence of returns risk to ensure your lifestyle remains sustainable regardless of market volatility.
- Explore how research-driven early retirement planning Sydney replaces uncertainty with a clear, modelled path to long-term financial freedom.
- See how bespoke portfolio construction, guided by an in-house Investment Committee, provides the professional oversight required for a complex exit strategy.
The Sydney Early Retirement Challenge: Why 55 is the New 65
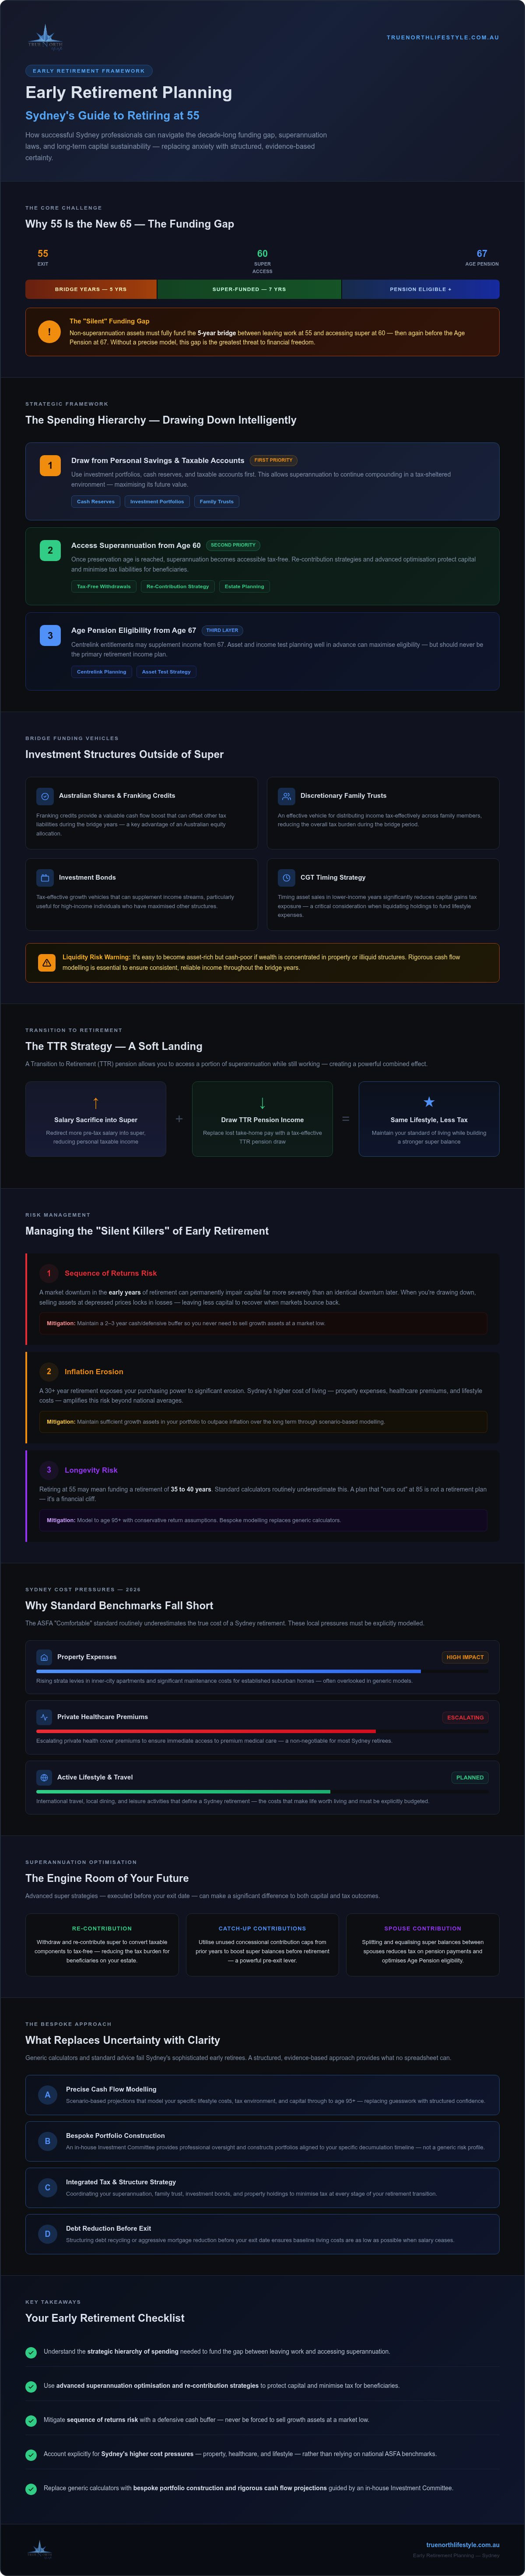
Retiring early in Australia means stepping away before the Age Pension at 67 or accessing superannuation at 60. For many Sydney professionals, the target is often age 55. This creates a decade-long gap that requires a unique set of strategic manoeuvres. Standard financial advice often overlooks the specific pressures of this transition.
Transitioning is difficult. For decades, your focus has been on accumulation, watching balances grow through disciplined saving and market growth. Shifting to decumulation, where you begin to draw down on that capital, requires a profound psychological adjustment. Without a clear, modelled path, the fear of "running out" can prevent you from enjoying the freedom you've earned. Early retirement planning Sydney is about replacing that anxiety with a sense of quiet certainty.
Generic plans fail here. Most retirement calculators use national averages that don't reflect the reality of life in the Harbour City. A bespoke approach is essential to account for higher property costs, lifestyle expectations, and the specific tax environment of New South Wales.
Defining the 'Bridge Years' in Your Strategy
The "bridge" refers to the critical period between stopping work and reaching your superannuation preservation age. For those born after 1964, this is age 60. During these years, your non-superannuation assets, such as investment portfolios, family trusts, or cash reserves, become your primary lifeline. A secondary gap often exists before any potential Centrelink entitlements become relevant at age 67. Successfully managing these years is not about luck; it's about strategic liquidity and tax-effective structuring of your accessible wealth.
Sydney Cost of Living Benchmarks for 2026
Maintaining a high standard of living in Sydney requires more than the standard ASFA "Comfortable" benchmark, which often underestimates the costs of our city. By 2026, retirees must account for specific local factors that impact capital longevity:
- Property Expenses: Rising strata levies in inner-city apartments and significant maintenance costs for established suburban homes.
- Healthcare: Escalating private health cover premiums to ensure immediate access to premium medical care.
- Active Lifestyle: Budgeting for international travel, local dining, and the leisure activities that define a Sydney retirement.
Your strategy must ensure that these costs don't outpace your income, protecting your lifestyle against the persistent pressure of inflation through rigorous, scenario-based modelling.
Navigating the 'Bridge': Funding Life Before Superannuation
Funding the years between your last day of work and your 60th birthday is a delicate balancing act. This period, often called "the bridge," requires a sophisticated hierarchy of spending to ensure your capital remains sustainable. Generally, we look to draw from personal savings and taxable investment accounts first. By doing so, your superannuation continues to compound in a tax-sheltered environment, maximising its growth potential for your later years. It's also vital to address liabilities early. Structuring debt recycling or aggressive mortgage reduction before your exit date ensures your baseline living costs are as low as possible when you stop earning a salary.
Investment Structures Outside of Super
Strategic early retirement planning Sydney necessitates looking beyond the superannuation environment. Discretionary family trusts and investment bonds serve as effective vehicles for tax-effective income. When selling assets to fund your lifestyle, you must be mindful of capital gains tax. Timing these sales during years of lower taxable income can significantly preserve your capital. Australian shares remain a cornerstone of this strategy; franking credits provide a valuable boost to cash flow that can offset other tax liabilities. Above all, maintain liquidity. It's easy to become asset rich but cash poor in Miranda if your wealth is tied up in property or illiquid structures. Clear retirement modelling is the only way to ensure your cash flow remains consistent and reliable.
The TTR Strategy: A Soft Landing
The Transition to Retirement (TTR) strategy is a sophisticated mechanism designed to bridge the gap between full-time employment and total retirement. If you've reached preservation age but aren't ready to stop work entirely, a TTR pension allows you to access a portion of your super. This creates a unique opportunity to salary sacrifice more of your income into super while replacing that lost take-home pay with a pension stream. The result is often a lower overall tax bill and a final boost to your retirement nest egg. This "soft landing" allows you to scale back your working hours in Sydney without compromising your standard of living. It provides the financial flexibility to transition into your new life with confidence and control.
Superannuation Optimisation: The Engine Room of Your Future
Superannuation is not just a savings account; it's a powerful tax-mitigation tool. For those engaged in early retirement planning Sydney, the years leading up to age 60 represent a critical window for optimisation. You need to balance concessional and non-concessional contributions to ensure your "engine room" is fully primed before you stop work. Understanding the Transfer Balance Cap (TBC), which limits how much you can move into the tax-free pension phase, is essential for high-balance retirees looking ahead to 2026. Whether you opt for the control of a Self-Managed Super Fund (SMSF) or the simplicity of a high-performing retail fund, the focus must remain on cost-efficiency and strategic allocation.
Maximising Your Super Balance in the Final Decade
Catch-up contributions allow you to use unused concessional caps from the previous five years. This is a vital strategy for Sydney professionals whose income has fluctuated or who have recently realised capital gains. Additionally, downsizer contribution rules offer a unique opportunity to inject up to $300,000 per person into super after selling a primary residence. This allows you to convert Sydney property equity into liquid, tax-effective retirement capital without it counting towards your standard contribution caps. For tailored insights on fund selection and performance, see our guide on Superannuation Advice Sutherland Shire to ensure your local portfolio is performing at its peak.
The Re-contribution Strategy Explained
Estate planning is often overlooked during the early retirement transition. A re-contribution strategy involves withdrawing a portion of your super and contributing it back as a non-concessional payment. This technical manoeuvre "washes out" the taxable component of your fund. It significantly reduces the potential tax liability for your adult children if they inherit your super, effectively minimising the impact of what is often called the "death tax." Timing is paramount. This strategy must be executed before you turn 75, and it requires careful coordination with your total super balance to avoid breaching non-concessional caps. It's a sophisticated way to protect your family's long-term wealth while you are still in the driver's seat.
For high-balance Sydney retirees, the choice between an SMSF and an industry fund often comes down to transparency. An SMSF provides the bespoke control many Sydney CBD clients prefer, especially when holding specific Australian shares or business real estate. However, the administrative discipline and compliance requirements are significant. We help you determine if the bespoke benefits of an SMSF outweigh the streamlined efficiency of a retail fund, ensuring your structure aligns with your long-term lifestyle goals.
Managing the 'Silent Killers' of Early Retirement
Successful early retirement planning Sydney involves more than just reaching a target balance; it requires a disciplined defence against the "silent killers" of financial freedom. While the accumulation phase is driven by growth, the transition to retirement is defined by risk management. The most potent threats to your lifestyle, including sequence of returns risk, inflation, and longevity, often remain hidden until they begin to erode your capital. Portfolio stress testing allows us to model "worst-case" scenarios, ensuring your strategy remains robust even in fluctuating environments.
Sequence of Returns: The Timing Trap
Sequence of returns risk is the danger that a market downturn occurs exactly when you begin drawing down on your assets. A significant dip in year one can be catastrophic, as you are forced to sell investments at depressed prices to fund your daily life. "The financial trajectory of your first five years in retirement will essentially dictate the sustainability of the next twenty." To mitigate this, we utilise a "bucket" approach to cash flow. By maintaining several years of living expenses in liquid, low-volatility accounts, you avoid selling growth assets during a market correction. This bespoke portfolio construction focuses on generating stable income without sacrificing long-term capital growth.
Longevity and Sustainability Modelling
Living longer than expected is a blessing, but it presents a unique mathematical challenge for your capital. Longevity risk is the danger of outliving your wealth, a concern that is amplified by the high cost of living in Sydney. We use sophisticated cash flow modelling to visualise your capital position through to age 95, ensuring your standard of living remains constant. This involves implementing wealth preservation strategies that account for the persistent pressure of inflation. By adopting dynamic spending rules, we can adjust your withdrawal rates based on actual market performance. This provides a clear, evidence-based path that protects your lifestyle from outpacing your income. If you want to ensure your capital is truly protected, our team can provide the portfolio sustainability modelling necessary to navigate these risks with quiet certainty.
The True North Approach: Bespoke Modelling for Sydney Retirees
Clarity replaces chaos. Our approach to early retirement planning Sydney moves far beyond the traditional "Statement of Advice" that often becomes obsolete the moment it's printed. We believe that a successful transition requires a living, breathing retirement model. This dynamic framework allows you to visualise the long-term impact of today's decisions, providing a sense of order in an often unpredictable financial environment. As your Steady Navigator, we provide the professional authority and emotional reassurance needed to transition from the workforce with absolute confidence.
Regular reviews are the cornerstone of this process. Sydney's economic landscape is rarely static, and your plan shouldn't be either. Whether it's a change in tax law or a shift in the local property market, our modelling is updated to reflect real-world conditions. This discipline ensures that your strategy remains aligned with your original objectives, allowing you to maintain oversight without feeling overwhelmed by the technical details. We do the heavy lifting so you can focus on the human outcomes of your financial freedom.
Bespoke Portfolio Construction
Generic investment solutions often fail the early retiree because they don't account for the specific timing of the "bridge years." Our in-house Investment Committee provides bespoke investment advice Sydney that is meticulously tailored to your specific retirement date and cash flow needs. We prioritise income-producing assets that generate reliable yield, significantly reducing the necessity to liquidate capital during periods of market stress. For our clients in Miranda and the Sydney CBD, this focus on stability and research-driven construction offers a protective barrier against the volatility that can derail a less structured plan.
Next Steps: Your Roadmap to Clarity
Identifying your "True North" lifestyle goals is the first step toward reclaiming your time. During an initial consultation, we move past the numbers to understand what a meaningful retirement looks like for you. To ensure your modelling session is as accurate as possible, please bring the following information:
- Asset Summary: Recent statements for superannuation, shares, and bank accounts.
- Liabilities: Current mortgage balances and any other outstanding debts.
- Lifestyle Budget: A detailed breakdown of your expected annual spending in Sydney.
- Estate Goals: A broad understanding of what you wish to leave for future generations.
This data allows us to build a precise, scenario-based projection of your financial future. You deserve a partner who values logic and proven outcomes over flashy innovation. Book a consultation with our Sydney retirement specialists to start building your bespoke roadmap to freedom.
Stepping Into Your Future with Confidence
Retiring early is a significant life transition that requires more than a healthy bank balance. It demands a rigorous framework to manage the "bridge years" before superannuation access and a disciplined defence against inflation and market volatility. By shifting your focus from simple accumulation to strategic decumulation, you can protect your Sydney lifestyle for the long term. Specialist early retirement planning Sydney replaces the persistent anxiety of the unknown with a sense of quiet, structured control. You've done the hard work of building your wealth; now it's time to ensure it works just as hard for you.
Our team provides the professional oversight needed to navigate this complex journey. Through specialist retirement modelling and bespoke portfolio construction guided by our in-house Investment Committee, we build a roadmap tailored to your unique goals. With convenient offices in Miranda and the Sydney CBD, we are positioned to act as your steady navigator in an ever-changing economic landscape. It's time to move from uncertainty toward a well-defined path to freedom. Secure your early retirement with a bespoke strategy from True North Lifestyle and step into your new life with absolute certainty.
Frequently Asked Questions
What is the best age to retire early in Sydney?
The ideal age is highly personal, but many Sydney professionals target between 55 and 60 to maximise their active years. Retiring at 55 requires five years of "bridge funding" before you reach the superannuation preservation age of 60. Our retirement modelling helps you determine if your non-super assets can sustain your lifestyle in Miranda or the CBD during this gap. Ultimately, the best age is when your modelled cash flow meets your desired standard of living.
How much super do I need for a comfortable early retirement in NSW?
A comfortable retirement in Sydney often requires significantly more than national averages due to higher property maintenance and lifestyle costs. While general benchmarks exist, we find many Sydney clients require a higher capital base to maintain their specific standard of living. Effective early retirement planning Sydney involves calculating your unique "burn rate" and ensuring your portfolio can generate sufficient income without depleting your capital prematurely, especially during a long retirement period.
Can I access my superannuation before age 60 for early retirement?
You generally cannot access your superannuation before reaching your preservation age, which is 60 for those born after June 1964. Early retirement before this age must be funded by assets held outside the super system, such as investment properties or personal share portfolios. Exceptions for severe financial hardship or permanent incapacity are rare. Strategic planning focuses on building a "bridge" of accessible wealth to carry you through until your super becomes available.
How does the 'downsizer contribution' work for Sydney homeowners?
If you are 55 or older and sell your primary Sydney residence held for over ten years, you can contribute up to $300,000 per person into your super. This doesn't count toward standard contribution caps, making it a powerful way to boost your retirement balance. It allows you to unlock equity from a large family home and move it into a tax-effective environment. This strategy is particularly effective for those looking to simplify their lifestyle.
What are the tax implications of retiring at 55 in Australia?
Retiring at 55 means you'll likely rely on non-super assets, which are subject to personal income tax and capital gains tax. You won't benefit from the tax-free status of a superannuation pension until you reach age 60 and meet a condition of release. Careful tax-minimisation strategies are essential during this five-year window. We focus on timing asset sales and utilising structures like family trusts to manage your taxable income effectively during this transition phase.
Is it better to pay off my mortgage or put more into super before retiring?
The decision depends on your interest rate, tax bracket, and expected investment returns. Paying off a mortgage provides a guaranteed "return" by eliminating interest costs and reducing your baseline living expenses in Sydney. Conversely, super contributions offer significant tax breaks that can accelerate your wealth. We use detailed cash flow projections to compare these options, often finding a balanced approach that secures your home while maximising your tax-sheltered superannuation environment.
How do I protect my retirement savings from a market crash?
Protection comes from diversification and sophisticated risk management. We implement a "bucket" strategy, keeping several years of living expenses in liquid, low-volatility assets to avoid selling during a downturn. Our in-house Investment Committee constructs bespoke portfolios that prioritise income-producing assets and sustainability. By stress-testing your plan against historical market crashes, we ensure you have the structural resilience to maintain your lifestyle in Miranda or the CBD, regardless of short-term market fluctuations.
What is the difference between an industry fund and an SMSF for early retirees?
Industry funds offer low-cost, simplified management, whereas a Self-Managed Super Fund (SMSF) provides maximum control and bespoke investment choices. For high-balance Sydney retirees, an SMSF allows for the inclusion of direct property or specific Australian shares that may align better with a complex early retirement strategy. However, SMSFs carry significant compliance responsibilities. We help you weigh the administrative burden against the strategic benefits to ensure your fund structure supports your long-term financial freedom.


