

What if the standard "safe" withdrawal rate you've been told to follow is actually the primary reason you might outlive your savings? It's natural to feel a sense of anxiety when you look at market volatility and the rising cost of living in Sydney. You've worked hard to build your nest egg. The fear of seeing it eroded by inflation or a poorly timed market dip is a weight many Australians carry. Effectively structuring retirement income streams Australia wide requires more than just following a dated rule of thumb; it demands a strategy that balances immediate lifestyle needs with long-term capital preservation.
This guide will show you how to calculate a sustainable withdrawal rate that protects your legacy while providing the confidence to spend on travel and experiences today. We will explore the latest 2026 modelling, from the A$2.1 million transfer balance cap to dynamic drawdown strategies that offer quiet certainty in an unpredictable world. By moving beyond simple percentages, you can replace confusion with a structured, well-defined path toward financial peace of mind.
Key Takeaways
- Moving beyond the 4% rule is essential for 2026, as static withdrawal rates often fail to account for modern Australian inflation and shifting market conditions.
- Proactively managing sequence of returns risk during the early years of retirement is vital to ensuring your capital remains resilient over a thirty-year horizon.
- Effectively structuring retirement income streams Australia requires a shift from rigid models to dynamic, variable strategies that respond to real-world portfolio performance.
- Stress-testing your strategy with forward-looking simulations allows you to plan for unexpected healthcare costs and aged care contingencies with professional clarity.
- Bespoke retirement modelling replaces financial anxiety with quiet certainty, giving you the confidence to enjoy travel today while protecting your family's legacy.
Beyond the 4% Rule: Why "Safe" Isn’t Always Sustainable in Australia
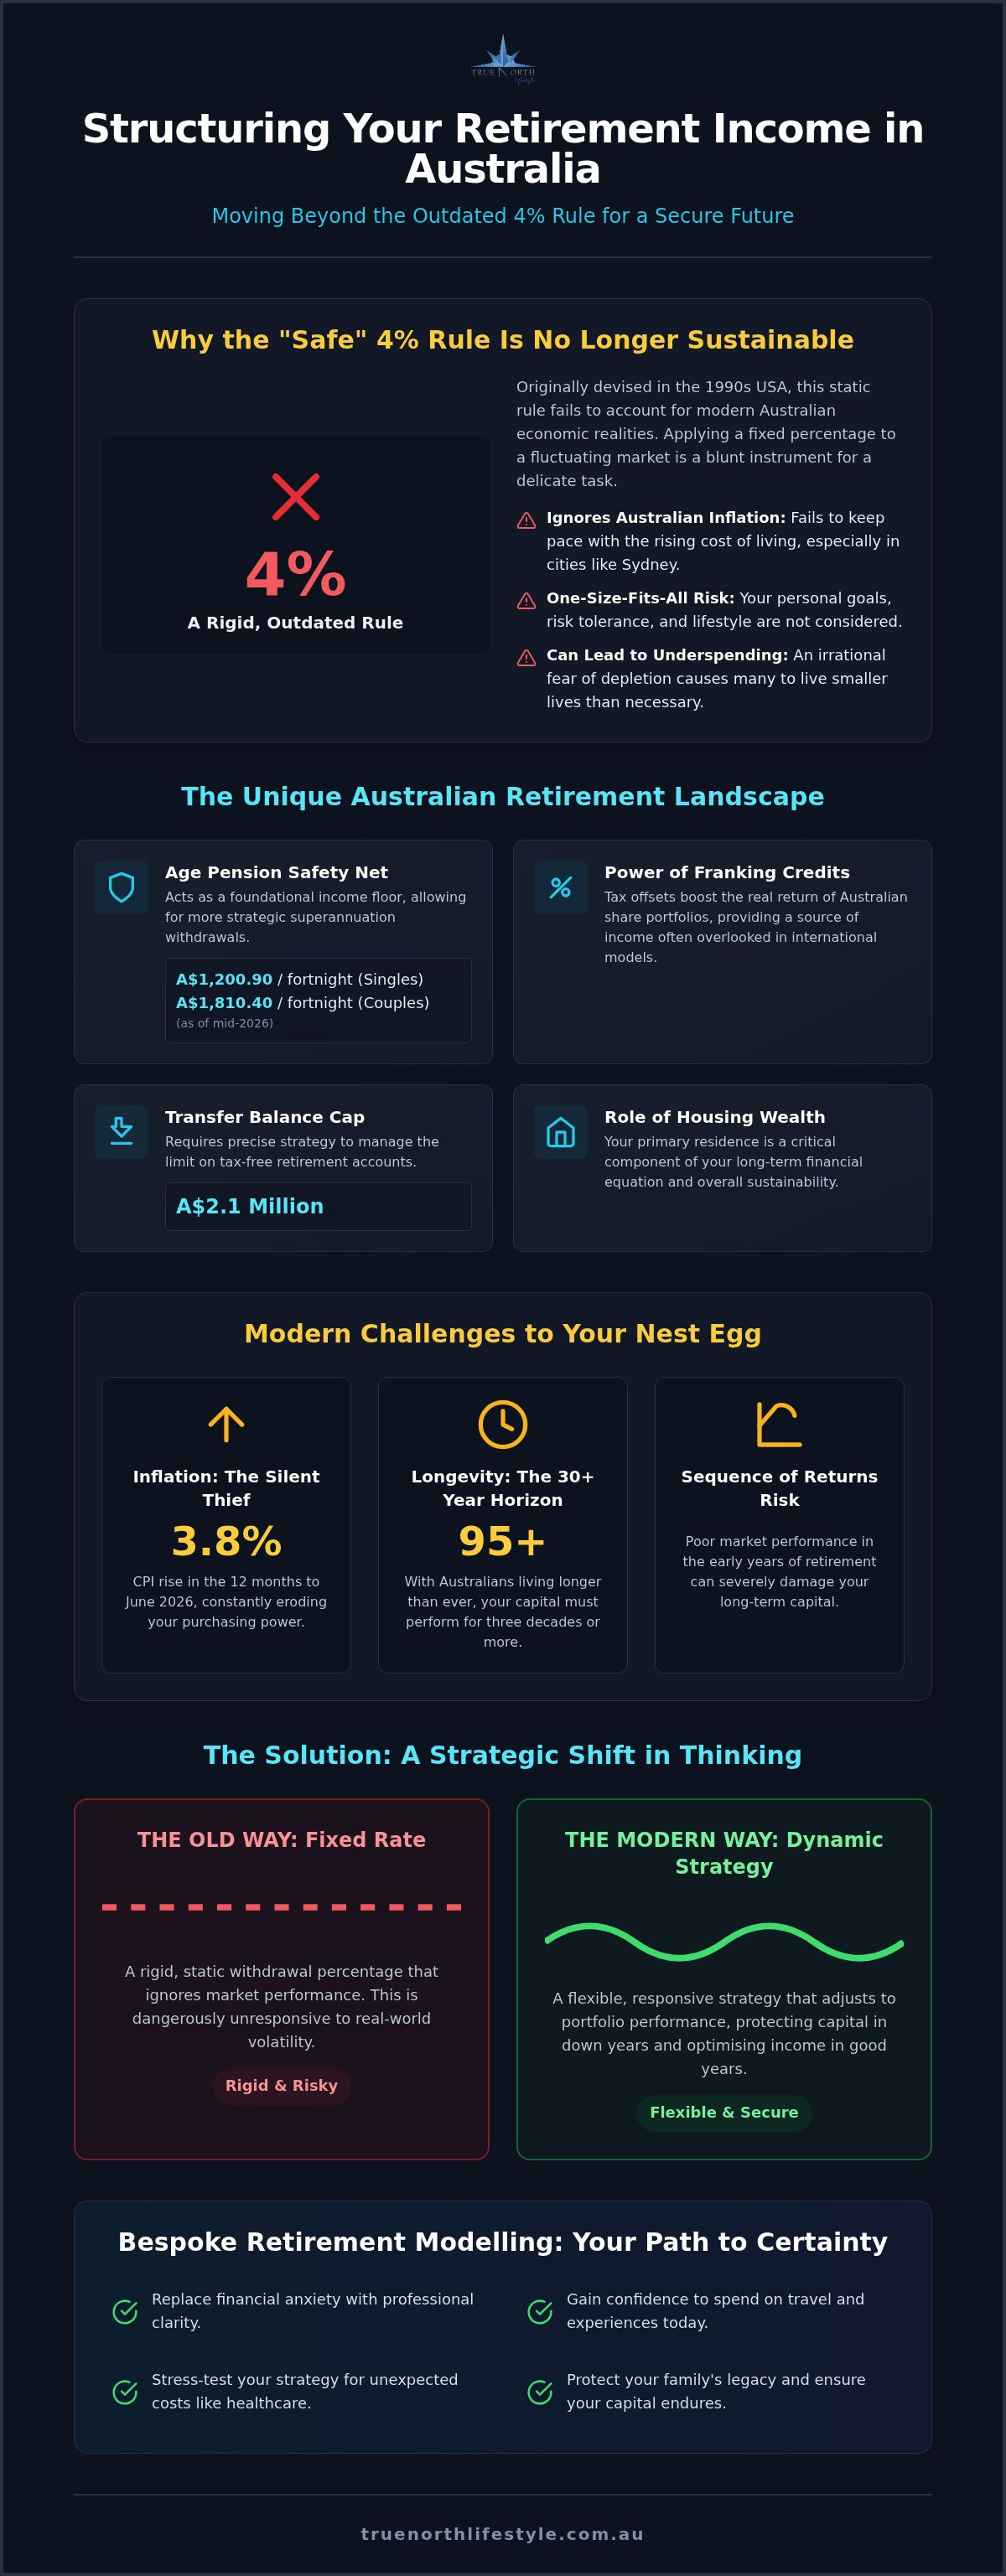
Stability requires structure. The 4% rule, once considered the gold standard of financial planning, often fails to account for the nuanced realities of 2026. Originally devised in the United States during the 1990s, this rule suggests that withdrawing 4% of your initial portfolio value, adjusted annually for inflation, should ensure your capital lasts for 30 years. However, applying a static percentage to a fluctuating market is a blunt instrument for a delicate task. For some, 4% is far too conservative, leading to a diminished lifestyle. For others, particularly those facing the high cost of living in Sydney, it may be dangerously aggressive.
A truly sustainable withdrawal rate is a dynamic calculation. It represents the maximum amount you can reliably spend while maintaining a high statistical probability that your assets will endure. When structuring retirement income streams Australia wide, we must look beyond generic benchmarks to find a balance that honours both your current lifestyle and your future security. This process involves sophisticated modelling that considers your specific asset allocation rather than relying on a one size fits all approach.
There is also a significant emotional cost to "underspending." Many retirees live smaller lives than they need to, driven by an irrational fear of capital depletion. They sacrifice travel, comfort, and generosity today, only to leave a massive unintended surplus decades later. Finding your "True North" means having the confidence to spend what you have earned, supported by the quiet certainty of professional projections.
The Problem with Rules of Thumb
Context matters deeply. A generic percentage ignores your specific Sydney lifestyle costs or the personal inflation rate you experience in areas like the Sutherland Shire. With the Consumer Price Index rising 3.8% in the 12 months to June 2026, your purchasing power is under constant pressure. Your "safe" rate is not a universal constant; it depends on your risk tolerance, your legacy goals, and your chosen retirement spend-down strategies. Relying on a rule of thumb during a volatile market is like using a paper map in a world of GPS; it provides a general direction but fails to navigate the immediate hazards.
The Australian Context: Super and the Age Pension
The Australian financial landscape is unique. Our retirement system provides levers that international models simply do not have. These factors change the withdrawal math significantly:
- The Age Pension Safety Net: With maximum fortnightly rates at A$1,200.90 for singles and A$1,810.40 for couples as of mid-2026, the pension acts as a natural floor. This safety net often allows for higher initial withdrawal rates from your private superannuation.
- Franking Credits: These tax offsets boost the real return of Australian share portfolios. They provide a source of income that is often overlooked in standard international withdrawal models.
- The Transfer Balance Cap: The A$2.1 million limit on tax-free retirement accounts requires precise strategic construction to ensure you aren't paying more tax than necessary.
- Housing Wealth: Whether your home is in Miranda or the Sydney CBD, your primary residence is a critical component of your long term sustainability equation.
By integrating these Australian-specific pillars, you can move from a place of uncertainty to a position of informed oversight. Professional modelling replaces guesswork with a structured, well-defined path forward.
The Mechanics of Longevity: Factors Influencing Your Withdrawal Rate
Longevity is a triumph of modern medicine, yet it presents a significant challenge for financial architecture. In Australia, the statistical probability of a 65-year-old living to 95 and beyond is higher than ever before. This means your capital must perform for three decades or more. Effectively structuring retirement income streams Australia wide requires accounting for this extended horizon. It's about ensuring your last dollar outlives you, not the other way around. This involves more than just a savings balance; it requires a disciplined approach to longevity risk.
Inflation remains the silent thief of purchasing power. With the CPI rising 3.8% in the 12 months to June 2026, the cost of living in New South Wales continues to climb. If your income stream doesn't keep pace, your lifestyle will inevitably shrink over time. Protecting your portfolio against this erosion is a core pillar of longevity planning, especially for those accustomed to a high standard of living in Sydney.
Managing Sequence of Returns Risk
The "Retirement Red Zone" covers the years immediately before and after you stop working. During this window, sequence of returns risk is at its peak. A market downturn in your first year of retirement can be catastrophic because you're withdrawing from a shrinking base. This prevents your portfolio from recovering when the market eventually turns. To mitigate this, we often use a "Bucket Strategy" to segregate short-term cash needs from long-term growth assets. This structure ensures you aren't forced to sell shares at a loss during a market dip. Bespoke portfolio construction offers a level of precision and "quiet certainty" that generic, off-the-shelf balanced funds simply can't match.
The Impact of Fees and Taxes
Operational costs matter. Investment management fees might seem negligible, but they compound over 30 years and can significantly reduce your sustainable withdrawal rate. Transparency is the only antidote to this drain on your wealth preservation. Beyond fees, your tax position is a critical lever. By implementing strategic tax planning for retirement Australia, you can lower the tax drag on your withdrawals. This effectively gives you a pay rise without increasing your investment risk. Professional retirement modelling can identify these hidden leakages and provide the structural integrity your lifestyle requires.
Comparing Strategies: Fixed vs. Variable Withdrawal Models
Choice defines freedom. When considering how to fund your future, the method you choose to extract capital is just as important as the investments themselves. Many Australians default to a fixed percentage model because it appears simple and predictable. However, a "set and forget" mindset is rarely compatible with long-term wealth preservation in a fluctuating market. Effectively structuring retirement income streams Australia wide requires an agile framework that responds to real-world performance rather than relying on static assumptions.
The Fixed Percentage Model involves withdrawing a consistent portion of your balance each year. While easy to calculate, it carries an inherent risk; if your portfolio value drops, your income shrinks, often at the very moment inflation is rising. Conversely, the Inflation-Adjusted Model prioritises your current lifestyle by increasing withdrawals in line with the CPI. While this maintains your purchasing power in the Sydney CBD, it can lead to rapid portfolio depletion if a market downturn occurs early in your retirement journey. Neither approach offers the sophisticated balance required for true peace of mind.
Implementing the Guardrails Approach
Precise. Proactive. Protected. The Guardrails Approach, often referred to as dynamic spending, replaces rigid rules with a responsive strategy. By setting pre-defined triggers, you can adjust your income based on how your portfolio is actually performing. This model relies on two critical boundaries:
- The Floor: This ensures your essential lifestyle needs-such as healthcare, utilities, and Sutherland Shire council rates-are always met, regardless of market volatility.
- The Ceiling: This allows you to capture excess market gains during "bonus" years, providing the capital for luxury travel, home renovations, or gifting to the next generation.
The psychological benefit of this structure is immense. It provides the quiet certainty that you have a plan for every market condition, allowing you to enjoy your wealth today without the constant shadow of future scarcity.
Case Study: Fixed vs. Dynamic in a Volatile Market
Consider a hypothetical couple in Miranda who begin their retirement during a significant bear market. If they follow a rigid fixed withdrawal model, they are forced to sell assets at depressed prices to meet their income needs, effectively locking in their losses. However, by using a dynamic model, they can choose to reduce discretionary spending slightly during the downturn. This tactical adjustment preserves their core capital, allowing the portfolio to benefit fully from the eventual market recovery. Sequence risk is the danger that the timing of poor investment returns, specifically in the early years of retirement, will permanently impair the longevity of a portfolio.
Stress-Testing Your Strategy: Preparing for the Unexpected
Confidence requires testing. Looking at how a portfolio performed in the 1980s or 90s provides limited insight into the specific economic challenges of 2026. We use forward-looking Monte Carlo simulations to model thousands of potential market paths, ensuring your plan remains robust under various conditions. Effectively structuring retirement income streams Australia wide means preparing for "grey swan" events-those unexpected but impactful moments like a sudden health crisis or a prolonged period of high inflation. Implementing comprehensive wealth preservation strategies is the foundation of this resilience, moving you from hope to a state of quiet certainty.
The Role of Cash Flow Modelling
Numbers can be numbing. High-level spreadsheets often hide the "lumpy" nature of real life. A new car, a daughter's wedding in the Sydney CBD, or essential home maintenance in Miranda don't appear as smooth annual percentages. Cash flow modelling visualises these spikes, showing you exactly how your capital reacts to major outflows. It replaces abstract data with a clear, intuitive map of your financial future. We use this bespoke modelling to provide the clarity you need to say "yes" to life's big moments without jeopardising your long-term security or your ability to cover future aged care contingencies.
Downsizing is a common pivot point. Selling a long-held family home in the Sutherland Shire can provide a significant capital injection, but it also fundamentally alters your financial architecture. We model how these transitions impact your Age Pension eligibility under the 2026 assets test and how that capital can be most effectively redeployed to support your withdrawal rate. This ensures that every move you make is backed by logical projection rather than guesswork.
Estate Planning and Legacy Goals
Wealth is a tool for connection. For many of our clients, the goal isn't just personal spending but providing a meaningful legacy for the next generation. Balancing your current lifestyle with this intent requires precise wealth transfer strategies Australia based families can rely on. This is particularly important when navigating the tax implications of "death benefits" for non-dependant beneficiaries, as the Australian system can impose significant tax on the taxable component of a superannuation death benefit. Our modelling ensures your hard-earned capital reaches your loved ones as intended. To discover how a tailored projection can anchor your plan, consider our professional retirement modelling.
Bespoke Retirement Modelling: Securing Your True North Lifestyle
Professional guidance replaces doubt with direction. While a generic calculator might offer a withdrawal figure, it cannot account for the intricate interplay between your specific goals and the Australian regulatory environment. Effectively structuring retirement income streams Australia wide requires a partner who understands that your portfolio is a vehicle for your lifestyle, not just a collection of assets. At True North Lifestyle, we act as your steady navigator, providing the research-driven oversight necessary to maintain order in a fluctuating market.
Our in-house Investment Committee ensures every portfolio is built on a foundation of rigorous testing and evidence-based methodology. We focus on bespoke portfolio construction designed to produce low-volatility income, which is essential for preserving capital during the early years of retirement. By integrating tax minimisation, superannuation optimisation, and strategic longevity planning, we create a unified architecture that protects your wealth while funding your aspirations. This is the essence of "Quiet Certainty"-the knowledge that your financial future is structured, protected, and managed with expert care.
The True North Lifestyle Advantage
Clarity is our commitment. We specialise in simplifying complex financial decisions for families across Sydney, from the Sutherland Shire to the CBD. Our process involves modelling multiple "what-if" scenarios, ensuring your plan remains robust whether the market is flourishing or facing headwinds. A retirement strategy isn't a static document; it's a living plan. Through an ongoing partnership, we help you adjust your spending guardrails as your life evolves, your travel goals change, or your family needs grow. This disciplined approach allows you to step into a role of confident oversight while we handle the heavy lifting of technical management.
Next Steps for Your Retirement
Taking control of your future begins with a conversation. We invite you to organise a consultation at our Miranda or Sydney CBD offices to begin the process of professional modelling. During your first retirement planning Sydney session, it's helpful to bring a clear summary of your current assets, superannuation statements, and an outline of your desired lifestyle expenses. We'll use this information to begin stress-testing your current trajectory and identifying opportunities for optimisation. By acting today, you ensure a calm and stable tomorrow, protected by a strategy designed specifically for your journey.
Take Control of Your Financial Longevity
Clarity replaces anxiety. The journey toward a sustainable retirement isn't about following a static percentage; it's about building a dynamic architecture that responds to the realities of 2026. By moving beyond generic rules of thumb, you can protect your capital against sequence of returns risk while maintaining the purchasing power required for a vibrant Sydney lifestyle. Effectively structuring retirement income streams Australia wide requires a sophisticated blend of technical precision and deep personal insight.
True North Lifestyle provides the professional oversight you need to move forward with quiet certainty. Our research-driven Investment Committee and expert financial advisers in Miranda and the Sydney CBD have already done the heavy lifting, testing thousands of scenarios to ensure your plan remains resilient. Through bespoke retirement modelling, we simplify the complex, allowing you to focus on the human outcomes of your success. You've worked hard to build your legacy; now it's time to ensure it works just as hard for you.
Ready to anchor your future? Book a Strategic Retirement Consultation with True North Lifestyle today and step into a role of confident oversight. Your path to a stable and rewarding tomorrow starts with a single, well-defined step.
Frequently Asked Questions
What is a safe withdrawal rate for an Australian retiree in 2026?
It typically ranges between 4% and 5% depending on your asset mix and age. For the 2026-2027 financial year, the government's minimum drawdown for those aged 65 to 74 is 5%. A truly safe rate is one that has been stress-tested against your specific longevity and risk profile. It's not a static number but a dynamic calculation that ensures your capital lasts as long as you do.
How does the Age Pension affect my sustainable withdrawal rate?
The Age Pension acts as a non-correlated safety net that can allow for a higher initial withdrawal rate from your private superannuation. Because the government provides a baseline income of up to A$1,200.90 per fortnight for singles, you may feel more confident drawing down your own capital early in retirement. This integrated approach to structuring retirement income streams Australia wide helps mitigate the inherent fear of running out of funds.
What is the difference between a safe and a sustainable withdrawal rate?
A safe rate is a historical benchmark, like the 4% rule, while a sustainable rate is a forward-looking projection tailored to your personal circumstances. Sustainability accounts for your specific tax position, investment fees, and the rising cost of living in the Sydney CBD. It moves beyond generic percentages to provide a modelled path that offers quiet certainty. It's about finding the balance between spending today and preserving wealth for tomorrow.
Can I increase my withdrawal rate if the share market performs well?
Yes, using a guardrails approach allows you to capture excess market gains for discretionary spending. When your portfolio value exceeds a pre-defined threshold, you can fund bonus lifestyle goals such as luxury travel or gifting to grandchildren in Miranda. This dynamic model ensures you benefit from market upswings while maintaining the structural integrity of your core retirement plan. It replaces rigid rules with a responsive, evidence-based strategy.
How often should I review my retirement withdrawal strategy?
You should conduct a formal review at least annually or whenever a significant life event occurs. Legislative changes, such as the indexation of the A$2.1 million transfer balance cap, or shifts in the Sydney property market can alter your optimal strategy. Regular reviews allow you to adjust your spending guardrails in real time. This ongoing partnership ensures your financial architecture remains aligned with your evolving goals and the broader economic environment.
What happens to my withdrawal rate if inflation continues to rise in Sydney?
Persistent inflation requires a withdrawal rate that is either inflation-adjusted or supported by growth-oriented assets. With the CPI rising 3.8% in the year to June 2026, maintaining your purchasing power is a critical challenge for Sydney families. If your income stream doesn't keep pace, your real lifestyle will shrink. Professional modelling helps you determine if your current rate remains sustainable or if tactical adjustments are needed to protect your longevity.
Do I need to change my investment portfolio to support my withdrawal rate?
Your portfolio architecture must be specifically designed to generate income while managing volatility. Effectively structuring retirement income streams Australia often involves moving away from generic growth funds toward bespoke construction. This might include a mix of dividend-yielding shares with franking credits and defensive cash buckets. Aligning your asset allocation with your withdrawal needs reduces the risk of being forced to sell assets during a market downturn, providing much-needed stability.
Is the 4% rule still relevant for Australians with a large super balance?
The 4% rule remains a useful starting point, but it's often too simplistic for those with significant wealth. High-net-worth retirees in the Sutherland Shire face unique challenges, such as the transfer balance cap and complex tax-minimisation needs. A static 4% withdrawal doesn't account for the Age Pension safety net or the specific legacy goals you might have. Modern modelling provides a far more accurate and efficient path than a 30-year-old rule.


