

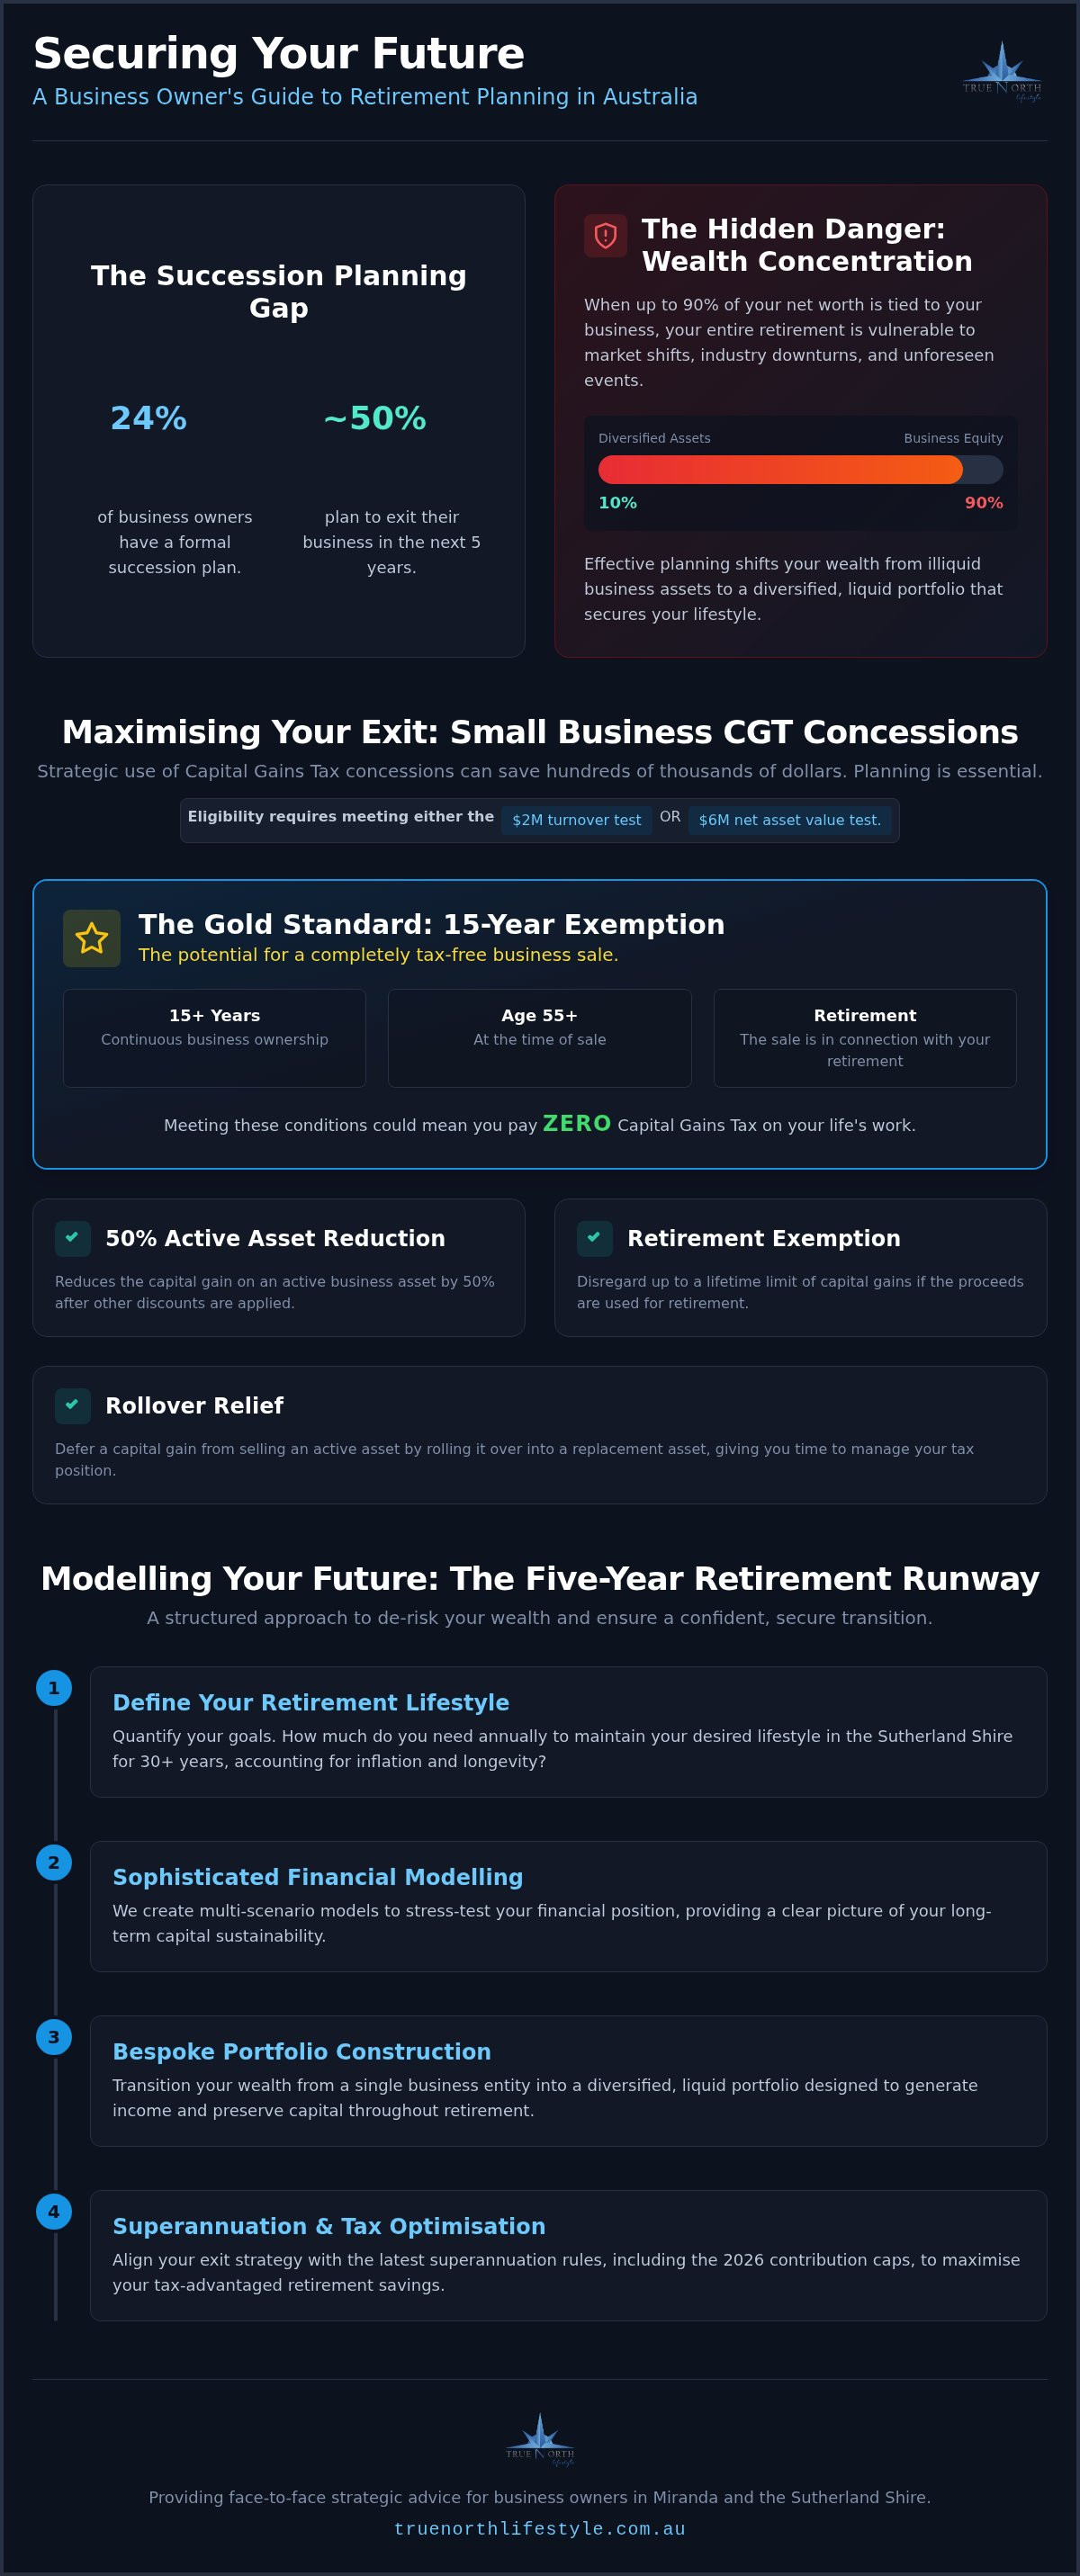
Only 24% of Australian business owners have a formal succession plan in place, even though nearly half plan to exit within the next five years. It’s a startling figure that highlights a common reality: your wealth is often illiquid and entirely tied to the daily performance of your company. This makes effective retirement planning for business owners Miranda a matter of strategic de-risking rather than just simple savings. You deserve to know that your life's work will translate into a stable, high-lifestyle future in the Sutherland Shire without the looming anxiety of a heavy Capital Gains Tax bill.
We believe your transition should be defined by order and clarity. This guide explores how to move from the demands of daily operations to a secure retirement through expert financial modelling and bespoke portfolio construction. We will preview the 2026 superannuation landscape, explain how to optimise small business tax concessions, and provide a clear timeline for a confident exit. By the end, you’ll see the path toward a sustainable, 30-year retirement that preserves both your legacy and your lifestyle.
Key Takeaways
- Identify the risks of wealth concentration and learn how to transition from business-heavy assets to a diversified, liquid portfolio that supports your personal lifestyle.
- Explore the four Small Business CGT concessions available in 2026, including strategies that could facilitate a tax-free exit for long-term Miranda business owners.
- Optimise your superannuation strategy by leveraging the increased 2026 contribution caps and adjusting for the latest Superannuation Guarantee rate changes.
- Understand how sophisticated multi-scenario modelling creates a "five-year runway," providing the quiet certainty needed for effective retirement planning for business owners Miranda.
- Discover the value of bespoke portfolio construction and face-to-face strategic advice delivered from our local office in the heart of Miranda.
The Miranda Entrepreneur’s Dilemma: Balancing Business Growth and Personal Retirement
Your business is likely your proudest achievement. For many in the Sutherland Shire, a company isn't just a source of income; it's a decade-long project of passion and constant reinvestment. However, this dedication often creates a significant blind spot. We frequently see local directors who've poured every surplus dollar back into staff, equipment, or expansion, leaving their personal superannuation neglected. While this growth builds a valuable asset, it tethers your future security entirely to the performance of a single entity. Effective retirement planning for business owners Miranda requires a shift in perspective. It's about recognising that your business is a tool to fund your life, not the life itself.
The local property market in Miranda and surrounding suburbs also adds a layer of complexity. With median house prices in the Shire remaining significantly higher than the national average, the "lifestyle floor" for a comfortable retirement is elevated. You aren't just planning for a basic pension; you're planning to maintain a standard of living that includes local dining, travel, and the upkeep of a premium family home. Relying solely on a future business sale to fund this is a high-stakes gamble that lacks the stability required for long-term peace of mind.
Identifying Concentration Risk in Your Portfolio
Wealth concentration is a quiet threat. When 90% of your net worth is tied to one local entity, you're vulnerable to specific economic shifts within the Sutherland Shire or your specific industry. If a market downturn coincides with your intended exit date, your nest egg could shrink overnight. Retirement planning for high-net-worth individuals involves deliberately de-risking this position. We help you begin the transition from an active business owner to a passive wealth manager, ensuring your lifestyle is supported by a diversified portfolio rather than just one balance sheet.
Defining Your Retirement Lifestyle in the Shire
What does retirement actually look like for you? For some Miranda residents, it's mornings at Cronulla beach and afternoons with grandkids. For others, it's six months of international travel every year. If your ideal retirement involves exploring the Sutherland Shire coastline on a luxury vessel, you might visit Neptune Oceanic to learn about their yacht share and vessel management services. Quantifying these goals is essential before we look at the numbers. A sustainable 30-year retirement in this region requires a clear understanding of your burn rate. Retirement planning for business owners Miranda must account for inflation and longevity. You need the quiet certainty that your capital won't just last, but will thrive, allowing you to step away from daily operations with your identity and your dignity intact.
Selling your business is often the most significant financial event of your life. In the context of retirement planning for business owners Miranda, it represents the moment your "paper wealth" becomes the liquid capital required to fund three decades of leisure. The Australian taxation system offers four specific Small Business CGT concessions that can dramatically alter your net proceeds: the 15-year exemption, the 50% active asset reduction, the retirement exemption, and the rollover relief. Accessing these requires meticulous structure and a clear understanding of the $2 million turnover threshold or the $6 million maximum net asset value test. If you don't align your business structure with these rules years before the sale, you risk losing hundreds of thousands of dollars to unnecessary tax.
The 15-Year Exemption: A Potential Tax-Free Windfall
This concession is the gold standard of exit strategies. If you've owned your Miranda-based business for at least 15 years and are aged 55 or over at the time of a "retirement-related" sale, you may be eligible to pay zero capital gains tax on the entire disposal. For an entrepreneur who established their entity in 2011, a 2026 exit fits this window perfectly. However, the definition of a "significant individual" and the way you distribute the final proceeds can make or break this eligibility. One wrong move in the final months of operation can disqualify a decade and a half of patient growth, turning a tax-free windfall into a significant liability.
Active Asset and Retirement Exemptions
Not every owner has 15 years of history, but other pathways remain highly effective. The $500,000 retirement exemption is a vital tool for wealth preservation. This concession allows you to disregard capital gains up to a lifetime limit of $500,000, provided the proceeds are directed into a complying superannuation fund if you're under 55. We often use this in conjunction with the 50% active asset reduction to ensure your exit is as tax-effective as possible. It's a complex puzzle that requires sophisticated retirement modelling to ensure you don't inadvertently breach your non-concessional contribution caps, which have increased to $130,000 for the 2026-27 financial year.
Precision requires time. You cannot simply decide to sell on a Friday and expect an optimised tax outcome by Monday. We recommend a three to five-year runway to clean up balance sheets, remove non-active assets, and ensure your business structure aligns with current ATO requirements. This period allows us to stress-test different exit scenarios, giving you the quiet certainty that your final payout will be protected from unnecessary erosion. By starting early, you move from a position of hope to a position of clinical, evidence-based control.
Superannuation Optimisation for Miranda Business Owners in 2026
As an employer and a beneficiary, the 2026 financial year brings specific challenges. The Superannuation Guarantee rate has reached 12%, a milestone that requires careful cash flow management for your Miranda company. However, for the owner, this increase is a forced mechanism for building passive wealth. Strategic superannuation advice Sutherland Shire ensures these contributions align with your broader exit strategy. With concessional caps now at $32,500 and non-concessional caps rising to $130,000, the window for tax-effective profit extraction is wider than ever. This is a core pillar of retirement planning for business owners Miranda, moving capital from a taxable business environment into a protected, low-tax vehicle.
SMSF Strategies for Business Real Property
Many Miranda business owners choose to hold their commercial premises, whether it's a retail shopfront or a professional office suite, within a Self-Managed Superannuation Fund (SMSF). This strategy allows your business to pay rent directly to your retirement fund, effectively building equity in an asset you already control. You must ensure the lease is strictly at "arm's length" market rates to maintain compliance with ATO regulations. The tax advantages are significant. Rental income is taxed at a maximum of 15% within the fund, and capital gains may be entirely tax-free if the property is sold while the fund is in the pension phase. It's a sophisticated way to diversify your wealth while retaining the benefits of your business's physical footprint.
The Re-contribution Strategy for Couples
Effective retirement planning for business owners Miranda involves looking beyond the business sale toward long-term wealth preservation. A re-contribution strategy helps couples level out their super balances, which is critical now that the general transfer balance cap has reached $2.1 million. By withdrawing funds and re-contributing them as non-concessional amounts, you can increase the "tax-free component" of your super. This reduces the potential "death tax" liability for non-dependant beneficiaries, such as adult children, who might otherwise face a 17% tax on the taxable component of an inherited fund. It's a methodical process of refinement that ensures your legacy remains protected and your spouse is financially secure.
Modelling Your Future: The Five-Year Retirement Runway
Retirement is not a single event. It is a multi-year transition that requires a methodical de-risking of your financial life. For those engaged in retirement planning Sydney, the process begins with a rigorous five-year runway. This period allows for sophisticated multi-scenario modelling that replaces guesswork with evidence. We start by auditing your current business and personal asset base, identifying what is liquid and what remains trapped in your company's balance sheet. By visualising these assets side-by-side, we can identify the exact gap between your current position and your ultimate retirement goal.
Precision is paramount. We project the specific cash flow requirements for your desired Sutherland Shire lifestyle, accounting for the reality of local costs. This model is then stress tested against various economic environments, including high inflation and market volatility. We ensure your plan survives even if the broader economy falters. Finally, we align your estate planning strategy with your retirement income stream, ensuring that your wealth is not only sustainable for your lifetime but also structured for a seamless transfer to the next generation. This is the cornerstone of effective retirement planning for business owners Miranda.
Bespoke Portfolio Construction for Stability
As you approach your exit, your investment philosophy must evolve. You move from the growth-heavy risks of business ownership toward bespoke investment advice Sydney that prioritises stability and income. We focus on low-volatility assets designed to protect your "exit capital" from a sequence of returns risk. This risk is particularly dangerous in the first few years after selling your business, where a market dip can permanently damage the longevity of your fund. Our collaborative approach ensures your portfolio is constructed to weather these fluctuations while providing a consistent yield.
Longevity and Sustainable Withdrawal Rates
Knowing exactly how much you can safely spend is the foundation of peace of mind. We calculate sustainable withdrawal rates tailored to the 2026 economic climate, specifically calibrated for the premium cost of living in the Miranda area. This data-driven approach provides the "Quiet Certainty" that your capital will last for 30 years or more. It allows you to enjoy your success and your time in the Shire without the underlying fear of outliving your money. To start building your own data-driven exit map, you can explore our retirement modelling services today.
Bespoke Retirement Solutions: Why Miranda Business Owners Choose True North Lifestyle
Transitioning from the helm of a successful company to a life of leisure in the Sutherland Shire is a profound shift. It isn't just a financial transaction; it's an emotional and identity-based evolution. At True North Lifestyle, we act as the steady navigator for this journey, providing the structured guidance needed to move from the chaos of daily operations to the quiet certainty of a well-funded future. Our local presence in the heart of Miranda allows for face-to-face strategic advice, ensuring that the human element of your legacy is never lost in the numbers. We specialise in retirement planning for business owners Miranda, focusing on the specific needs of entrepreneurs whose wealth is often concentrated in their life's work.
Our methodology is grounded in "real-world" probability rather than speculative hype. We utilise a research-driven approach to tax planning for retirement Australia, ensuring that every concession and exemption is maximised to protect your exit proceeds. By simplifying the complex interplay between business valuation, superannuation law, and personal cash flow, we empower you to make informed decisions with confidence. You've done the heavy lifting of building a business; our role is to do the heavy lifting of protecting its value for the next 30 years.
A Stabilising Partner for Your Legacy
Exit-related anxiety is a natural response to uncertainty. We replace this feeling with a logical, step-by-step roadmap that accounts for your unique goals. Our Investment Committee provides rigorous oversight on every bespoke portfolio, ensuring your capital is managed with a focus on low-volatility and sustainable income. This institutional-grade expertise is delivered with the personal warmth of a local partner who understands the Miranda community. We don't just build portfolios; we build the financial infrastructure that supports your continued contribution to the Shire, whether through family, philanthropy, or leisure.
Taking the First Step Toward Clarity
As you refine your long-term strategy, ensuring your business's digital profile is polished can be a vital part of your overall legacy; to explore custom website options, check out North Star Digital.
Preparation is the key to a successful exit. In your initial strategic consultation, we'll begin the process of business exit modelling by reviewing your current asset base and lifestyle expectations. To prepare for this session, you should gather your recent company financial statements, trust deeds, and superannuation summaries. This data allows us to create the first draft of your retirement runway, identifying specific opportunities for tax optimisation and risk reduction. If you're ready to define your path with clinical precision, book a consultation at our Miranda office today. Let's ensure your legacy is as secure as the life you've spent years building.
Securing Your Legacy in the Sutherland Shire
Transitioning from business ownership is a multi-layered process that demands clinical precision and strategic foresight. By leveraging the latest Small Business CGT concessions and optimising your superannuation for the 2026 landscape, you can transform years of hard work into a tax-effective, lifelong income stream. Our research-driven Investment Committee provides the oversight necessary to construct a bespoke portfolio that prioritises stability, ensuring your lifestyle in the Shire remains sustainable for decades to come. This methodical approach replaces the anxiety of the unknown with a structured, logical path toward freedom.
Expert retirement planning for business owners Miranda requires a local partner who understands both the technical complexity of an exit and the emotional weight of your legacy. From our office in Miranda 2228, we provide the sophisticated modelling and quiet certainty needed to step away from daily operations with confidence. We've already done the heavy lifting and rigorous testing so you can step into a role of oversight. Secure your Miranda business exit strategy with a bespoke retirement modelling session. Your next chapter is ready to begin.
Frequently Asked Questions
What are the best CGT concessions for business owners in Miranda?
The 15-year exemption is the most powerful tool for long-term owners, potentially allowing for a completely tax-free exit. Other vital concessions include the 50% active asset reduction and the $500,000 retirement exemption. For those engaged in retirement planning for business owners Miranda, the choice depends on your age, ownership duration, and the total value of your net assets. Aligning these concessions with your superannuation strategy is essential for wealth preservation.
How much do I need to retire comfortably in the Sutherland Shire?
A comfortable retirement in the Sutherland Shire typically requires a higher capital base than the national average due to local property maintenance and lifestyle costs. While generic industry standards exist, your specific requirement depends on your desired "burn rate" and longevity projections. We use sophisticated modelling to determine the exact lump sum needed to sustain your lifestyle for 30 years or more without the risk of exhausting your capital.
Can I sell my business and put all the money into superannuation?
You cannot simply deposit the entire sale proceeds into superannuation due to strict annual contribution caps. For the 2026-27 financial year, the non-concessional cap is $130,000, although the bring-forward rule may allow for $390,000 over three years. However, the Small Business CGT retirement exemption allows you to contribute up to an additional $500,000 over your lifetime. Navigating these limits requires precise timing to avoid significant tax penalties.
When should a Miranda business owner start retirement planning?
We recommend starting the process at least three to five years before your intended exit date. This timeframe allows you to clean up your balance sheet, satisfy the "active asset" requirements for CGT concessions, and maximise your superannuation contributions. Early retirement planning for business owners Miranda provides the necessary runway to stress-test various scenarios, ensuring you aren't forced to sell during a period of market volatility or local economic downturn.
What is the difference between a general financial planner and a retirement specialist?
A retirement specialist focuses on the complex transition from active earning to sustainable spending, whereas a general planner often focuses on broad wealth accumulation. Specialists provide deep expertise in tax-minimisation, Centrelink structuring, and longevity risk modelling. Our role is to act as a steady navigator through the specific regulatory hurdles of business exits, ensuring your portfolio is constructed for income stability rather than just speculative growth.
How does the 2026 superannuation rate affect my business exit strategy?
The 12% Superannuation Guarantee rate in 2026 increases your operational overheads but also accelerates your personal wealth building. When planning an exit, this higher rate must be factored into your business's profitability and valuation. Buyers will scrutinise these increased labour costs, so your financial modelling must demonstrate that the business remains a high-yielding asset despite the higher mandatory contribution levels for your staff and yourself.
Is it better to sell my business or pass it on to family for retirement income?
Selling to an external party often provides a cleaner break and access to the 15-year CGT exemption, whereas passing a business to family involves complex succession issues. Family transfers may not always trigger the same tax-free windfalls and can create ongoing reliance on the business's future performance. We help you weigh the emotional desire for a family legacy against the financial security of a structured market sale and a diversified portfolio.
How do I protect my retirement assets from inflation in 2026?
Protecting your assets from inflation involves moving away from stagnant cash holdings toward a bespoke portfolio of income-generating assets. We focus on investments that have a historical correlation with rising prices, such as specific equities and infrastructure. By utilising sophisticated modelling, we ensure your withdrawal rate is adjusted for the 2026 economic climate, providing the quiet certainty that your purchasing power remains intact throughout your entire retirement.


