

Your financial adviser should be your strongest advocate. For too long, the Australian wealth management industry relied on opaque structures that prioritised product sales over personal outcomes. You've likely felt that familiar sense of unease while reviewing your superannuation statements, wondering if those "bundled costs" are actually funding your future or merely padding a bank's bottom line. It's a common burden to carry, especially when the very people meant to guide you seem tethered to the products they recommend.
We understand that complexity breeds anxiety, particularly as tax and superannuation laws continue to evolve through 2026. By partnering with a fee for service financial planner Australia, you're choosing a path of total cost transparency and absolute ethical clarity. This guide will demonstrate how conflict-free, research-driven strategies can protect your wealth and provide the quiet certainty you deserve. We'll examine the structural shift toward bespoke portfolio construction and show you exactly how to ensure your navigator is legally and ethically on your side as you move toward retirement.
Key Takeaways
- Understand how a fee for service financial planner Australia eliminates the anxiety of hidden commissions, replacing them with a transparent, professional fee structure that puts you in control.
- Learn how to evaluate the true value of a Statement of Advice (SoA) and why this comprehensive roadmap is essential for navigating the complex 2026 superannuation landscape.
- Discover the strategic benefit of bespoke portfolio construction, where every decision is driven by rigorous research rather than bank-aligned product incentives.
- Explore how tax-minimisation and Centrelink optimisation strategies contribute to a sustainable retirement plan, ensuring your wealth is preserved for the long term.
- Gain a sense of calm and order by understanding the "Peace of Mind" premium, where expert guidance transforms financial complexity into a structured, manageable path.
What is a Fee-for-Service Financial Planner in Australia?
Clarity brings peace. A fee for service financial planner Australia operates on a simple premise: you pay for professional expertise, not for the privilege of being sold a financial product. This model replaces the opaque commission structures of the past with a transparent, flat-dollar professional fee. It's a structural commitment to objectivity that ensures your adviser's success is tied directly to the quality of their strategy, rather than the volume of products they sell. By removing the incentive to recommend specific funds or insurance providers, the fee-for-service model creates a foundation of trust where your goals are the only priority.
The Australian financial landscape has shifted away from product-pushing toward genuine strategic advice. This evolution makes meeting the "Best Interests Duty" far more straightforward. When an adviser isn't tethered to a bank or a specific investment platform, their recommendations are dictated solely by rigorous research and your personal lifestyle goals. It's a cleaner way of working that prioritises your long-term wealth preservation over short-term sales targets.
The End of the Commission Era
The Australian financial landscape has undergone a profound transformation following the 2018-2019 Royal Commission. Previously, "free" advice often carried hidden costs, with trailing commissions quietly eroding superannuation balances over decades. Today, the industry prioritises professional standards and ethical clarity. The Financial Planning Association of Australia (FPAA), which has since merged into the Financial Advice Association Australia, played a pivotal role in this evolution toward higher education and ethical benchmarks. By 2026, the "Best Interests Duty" isn't just a legal checkbox; it's the foundation of a research-driven partnership where the adviser serves as your steady navigator.
Transparency as a Stabilising Force
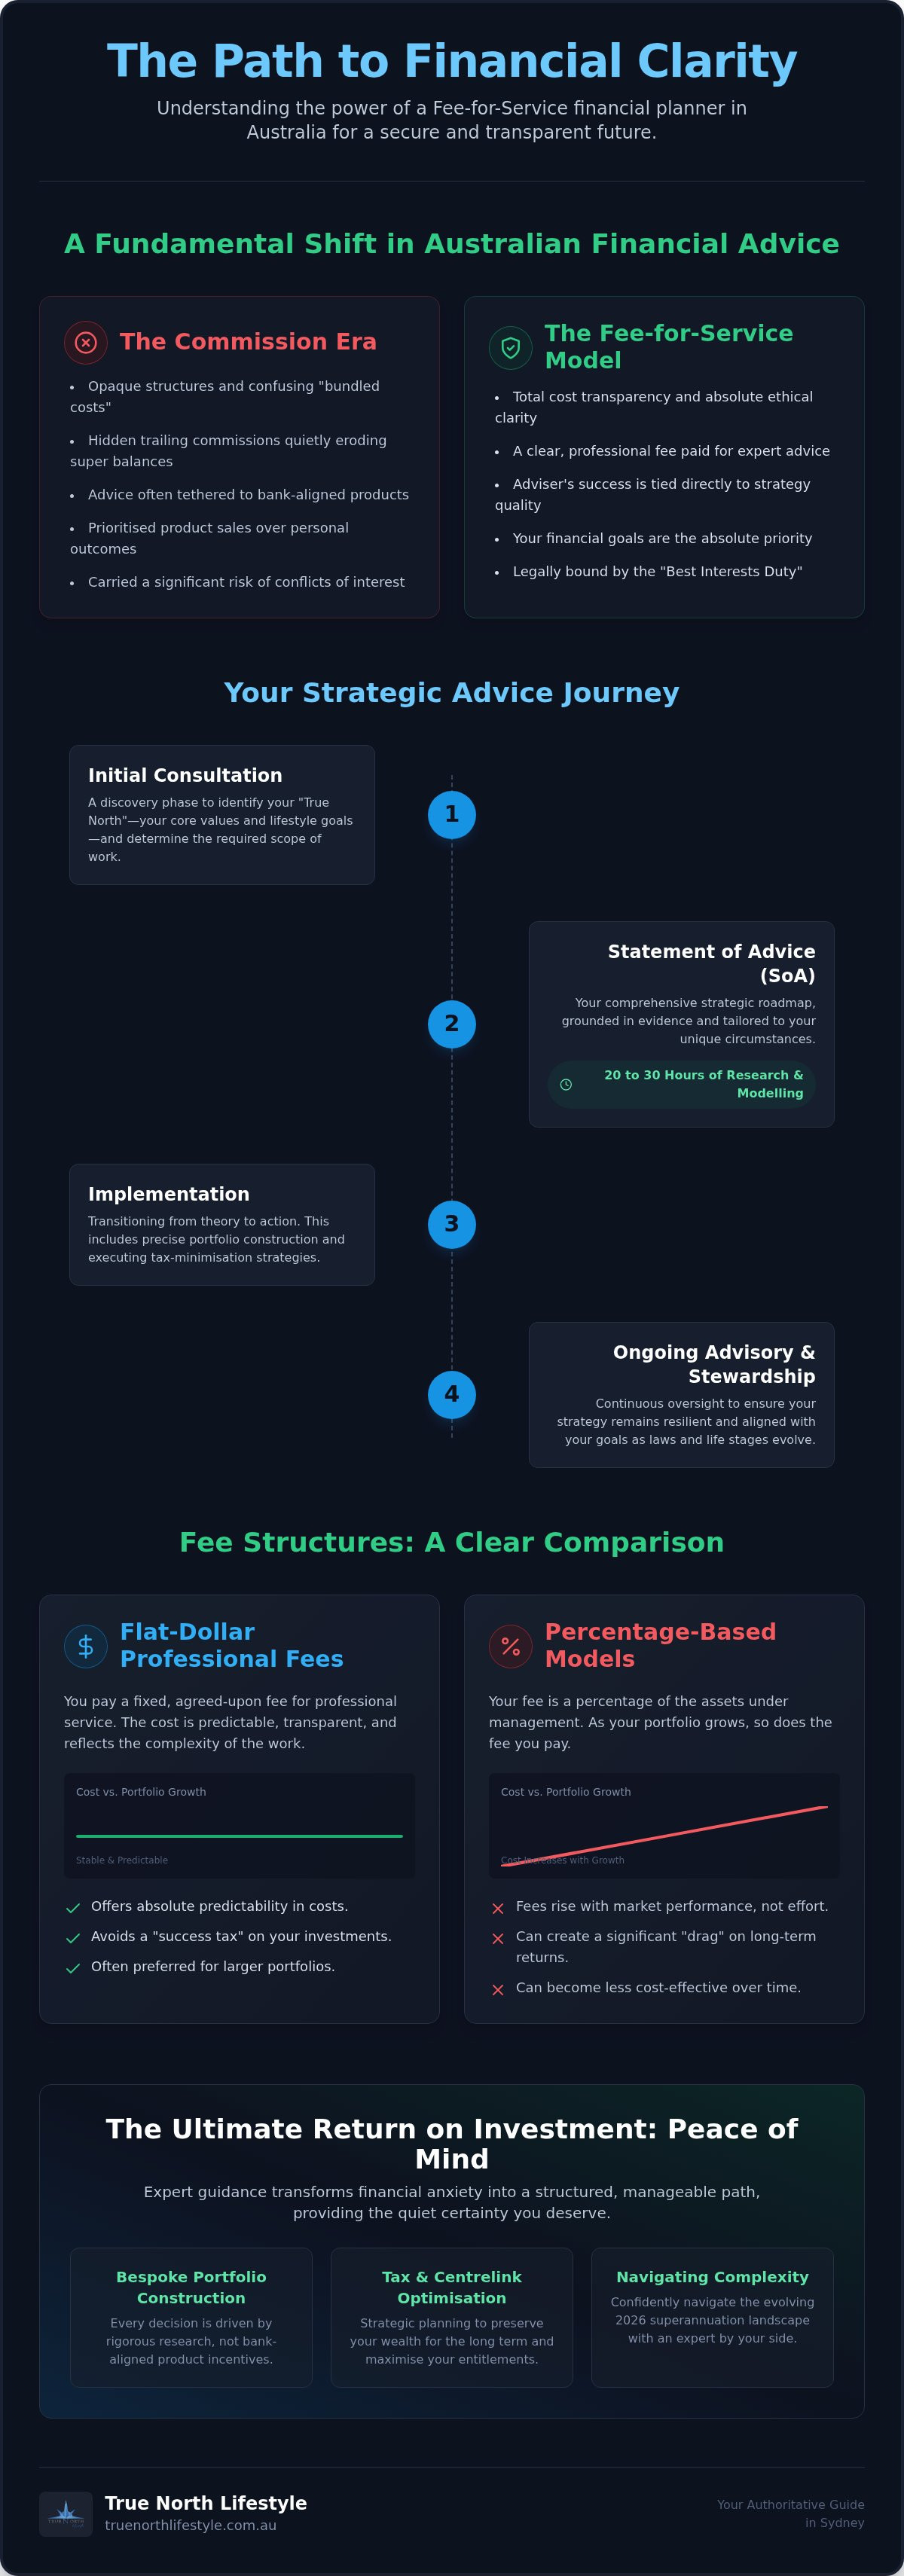
Knowing your exact costs upfront replaces financial anxiety with a sense of order. Under Australian law, advisers must provide a Fee Disclosure Statement (FDS), which clearly outlines the services provided and the fees charged. This transparency is vital because it shifts the focus from the size of your portfolio to the complexity of the strategy required. Whether you need intricate retirement modelling or bespoke portfolio construction, your fee reflects the intellectual labour and technical modelling involved. This distinguishes the model from asset-based fees, where you might pay more simply because your investments grew, even if the adviser's workload remained the same. Flat-dollar fees ensure your costs remain predictable and fair.
Understanding the Cost Structures of Professional Advice
Clarity is earned. When you engage a fee for service financial planner Australia, you aren't simply buying a document; you're investing in a rigorous process of discovery, modelling, and execution. This journey typically begins with an initial consultation, a vital phase where we identify your "True North" and determine the scope of work required to secure your future. Following this, the Statement of Advice (SoA) serves as your strategic roadmap. It's a high-level technical document that requires significant intellectual labour. Research indicates that a modern SoA typically takes 20 to 30 hours to research, document, and produce, ensuring every recommendation is grounded in evidence and tailored to your specific circumstances.
Implementation fees cover the transition from theoretical modelling to real-world action. This involves the precise construction of your portfolio and the coordination of tax-minimisation strategies. Finally, ongoing advisory fees provide the stewardship necessary to keep your plan resilient. As life stages evolve and Australian regulations shift, this continuous oversight ensures your strategy remains aligned with your long-term goals. Understanding these financial advice costs upfront replaces uncertainty with a sense of order, allowing you to focus on the human outcomes of your wealth.
Fixed Fees vs. Percentage-Based Models
Choosing the right billing structure is a critical decision for your long-term wealth preservation. Flat-dollar professional fees offer absolute predictability; they don't increase just because your portfolio grows. This is often the preferred choice for high-net-worth individuals who want to avoid a "success tax" on their investments. Alternatively, percentage-based fees, which typically range from 0.5% to 1.5% of assets under management, can be useful for those who prefer their costs to scale naturally with their portfolio size. Both models can exist within a fee-for-service framework, provided they are transparent and conflict-free. Selecting the structure that best suits your superannuation goals is a foundational step in establishing a trusting partnership.
What Influences the Cost of Your Advice?
Complexity is the primary driver of professional fees. A straightforward superannuation review requires less technical modelling than a strategy involving Self-Managed Superannuation Funds (SMSFs) or testamentary trusts. When your situation involves complex tax-minimisation or intricate Centrelink structuring, the depth of the research increases significantly. Bespoke portfolio construction also differs from "off-the-shelf" options; it involves an in-house Investment Committee and rigorous stress-testing of asset allocations. If you're seeking a structured path forward, starting with professional retirement modelling can provide the technical depth needed to navigate these variables with confidence.
The Strategic Advantages of Transparent Financial Advice
Alignment creates stability. When you engage a fee for service financial planner Australia, the structural conflict between product sales and strategic advice disappears. Your adviser succeeds only when your strategy succeeds, creating a partnership rooted in mutual outcomes rather than transaction volumes. This model eliminates the "product bias" often found in bank-aligned or commission-based environments, where recommendations might be skewed toward specific superannuation funds or insurance providers. Instead, you gain the freedom to pivot strategies as your life changes, without being locked into restrictive financial products that no longer serve your needs.
This transparency is particularly vital for retirement planning Sydney, where the high cost of living requires a precise, long-term approach to cash flow. According to the Financial Advice Association Australia (FAAA), professional standards now demand a higher level of ethical accountability, ensuring that advice is tailored to the individual's best interests. By decoupling the adviser's pay from the investment choice, the focus remains squarely on technical modelling and longevity planning. You aren't just buying a portfolio; you're securing a disciplined methodology designed to weather market volatility over decades.
Bespoke Portfolio Oversight
True wealth preservation requires a conflict-free environment. A fee-for-service structure allows for a research-driven bespoke investment advice Sydney approach, where every asset allocation is scrutinised by an in-house Investment Committee. This committee focuses on managing low-volatility portfolios that prioritise stability over aggressive, high-risk growth. Because the adviser has no financial incentive to recommend one fund over another, they can objectively select best-of-breed investments that align with your specific risk profile. This level of oversight ensures your capital is protected through rigorous stress-testing and strategic construction.
Maximising Superannuation and Tax Outcomes
Complexity necessitates expertise. Transparent professional fees facilitate sophisticated tax planning for retirement Australia, moving beyond basic compliance to active minimisation. This is essential as we navigate the 2026 superannuation guarantee changes, where understanding the interplay between contribution caps and tax offsets can significantly impact your final balance. Advising professionals can implement advanced re-contribution strategies for couples, effectively lowering future tax liabilities for beneficiaries. These technical manoeuvres require deep expertise and hours of modelling, a level of service that is only sustainable when the adviser is compensated for their time and intellectual labour rather than product placement.
Evaluating the Return on Investment (ROI) of Advice
Value is measurable. Engaging a fee for service financial planner Australia provides benefits that extend far beyond simple investment returns. It's about the technical optimisation of your entire financial ecosystem. This includes active tax-minimisation and strategic Centrelink structuring, which can significantly increase your net income in retirement. For many, the "Peace of Mind" premium is the most valuable outcome. Knowing you have a structured path replaces the persistent anxiety of managing complex wealth alone. You're paying for the certainty that your strategy is built on logic rather than luck.
Professional guidance also mitigates critical risks like the sequence of returns. This is the danger of a market downturn occurring just as you begin to draw down your capital. Without a disciplined strategy, a poorly timed withdrawal can permanently damage your portfolio's longevity. A research-driven approach ensures your cash flow is protected through diverse market cycles, allowing you to maintain your lifestyle without fear of exhausting your assets prematurely.
Tax Deductibility of Financial Advice Fees
Navigating ATO rules requires precision. In 2026, the distinction between deductible strategic advice and non-deductible capital costs remains a focal point for high-net-worth individuals. Generally, fees associated with the ongoing management of your investments are tax-deductible, whereas the initial cost of producing a Statement of Advice is often treated as a capital expense. By structuring your professional fees correctly, you can maximise your after-tax position and ensure you aren't overpaying for expertise. You should work with an adviser who understands these nuances to ensure your strategy remains as cost-effective as possible.
Longevity and Wealth Preservation
Protecting your capital is a lifelong commitment. Implementing robust wealth preservation strategies involves more than just picking the right stocks; it requires rigorous portfolio stress testing. We model various economic scenarios to ensure your money lasts as long as you do, accounting for inflation and shifting lifestyle costs. The cheapest advice often proves the most expensive if it fails to account for these long-term variables. If you're ready to secure your legacy with a structured approach, you can request a retirement modelling consultation to begin your journey.
True North Lifestyle: Your Authoritative Guide in Sydney
Confidence is built on structure. At True North Lifestyle, we embody the role of the Steady Navigator, providing the professional authority and research-driven methodology required to steer through the complexities of 2026 wealth management. As a premier fee for service financial planner Australia, we have removed the inherent conflicts of bank-aligned advice, replacing them with a disciplined, in-house Investment Committee approach. Our partnership with Resonant Asset Management ensures that your portfolio is not merely a collection of products, but a strategically constructed engine designed for longevity and capital preservation. We provide a stabilising presence, allowing you to step into a role of confident oversight while we manage the technical lifting.
Location matters when it comes to understanding your lifestyle. With local offices in Miranda and the Sydney CBD, we provide convenient access to high-level strategic advice for residents across the Sutherland Shire and the greater metropolitan area. Sydney’s unique cost of living and property market dynamics require a bespoke approach to retirement modelling. We don't rely on generic national averages; instead, we build projections based on the real-world probabilities of your specific environment. This local expertise, combined with our privately owned status, ensures that our loyalty remains exclusively with you, free from the pressure of corporate product quotas.
A Personalised Approach to Strategy
We focus on human outcomes. While arbitrary market benchmarks have their place, your personal lifestyle goals are the true measure of success. Our process involves simplifying dense financial jargon into a logical, step-by-step realization of your goals, ensuring you feel empowered rather than overwhelmed. This clarity is especially critical when managing wealth transfer strategies Australia, where we help Sydney families navigate the emotional and technical complexities of passing a legacy to the next generation. We ensure that your estate planning and asset protection strategies are as resilient as your investment portfolio.
Securing Your Future in the Sutherland Shire and Beyond
Honesty is our foundation. By operating as a privately owned firm, we offer a "no-nonsense" approach to value that prioritises directness and proven outcomes. Miranda residents and those in the CBD benefit from a partner who has already done the rigorous testing, allowing for a structured and calm transition into retirement. Your journey toward financial certainty begins with a clear understanding of your current position and a well-defined path forward. We invite you to experience a consultation process that mirrors the order and stability you seek for your future, moving you from uncertainty toward a disciplined, research-focused strategy.
Securing Your Financial Legacy with Confidence
Order replaces uncertainty. By choosing a fee for service financial planner Australia, you've prioritised a relationship built on total transparency and ethical clarity. We've explored how a conflict-free structure ensures your adviser's interests remain perfectly aligned with your lifestyle goals, protecting you from the hidden costs of bank-aligned models. True North Lifestyle remains a privately owned, research-driven firm dedicated to providing the quiet certainty you deserve. Our in-house Investment Committee and deep expertise in complex retirement modelling allow us to construct bespoke portfolios that focus on capital preservation and longevity.
Your financial future isn't a collection of numbers; it's the foundation of your personal freedom. With a structured plan and a steady navigator, the complexities of Australian tax and superannuation laws become a clear path toward stability. We invite you to book a confidential strategy session with our Sydney advisers to begin refining your long-term projections. Step forward with the confidence that comes from professional authority and a strategy designed exclusively for your journey. You've done the hard work of building your wealth; now, let's ensure it's protected for the decades to come.
Frequently Asked Questions
What is the difference between fee-for-service and commission-based advice?
Fee-for-service advice involves a transparent, flat professional fee paid directly by the client for technical expertise. In contrast, commission-based models involve payments from product providers to the adviser, which can create inherent conflicts of interest. By engaging a fee for service financial planner Australia, you ensure that every recommendation is driven by your best interests rather than the potential for a product-related payment. This structural clarity is the foundation of a trusting, long-term partnership.
How much does a Statement of Advice (SoA) cost in Australia in 2026?
The cost of a Statement of Advice (SoA) varies significantly based on the technical complexity of your financial situation. A comprehensive plan typically requires 20 to 30 hours of rigorous research, modelling, and documentation by a senior professional. Factors such as Self-Managed Superannuation Funds (SMSFs), complex tax-minimisation needs, or intricate estate planning will influence the final professional fee. This investment reflects the intellectual labour required to build a resilient, bespoke roadmap for your future.
Are financial planning fees tax-deductible for Australian residents?
Tax deductibility depends on the nature of the advice provided under current ATO guidelines. Generally, fees paid for ongoing advice related to managing your existing investments or superannuation are deductible. However, the initial cost of establishing a financial plan is often considered a capital expense and isn't deductible. It's vital to work with an adviser who can clearly distinguish between these components to help you optimise your after-tax position effectively.
Can I pay for financial advice using my superannuation fund?
You can often pay for financial advice directly from your superannuation fund, provided the advice relates specifically to your interest in that fund. This is a common method for Australian residents to access professional expertise without impacting their daily cash flow. However, strict regulatory rules govern what can be deducted from super. Your adviser will help you determine if your specific strategy meets these requirements while ensuring your retirement savings remain protected.
What should I look for when choosing a fee-for-service financial planner in Sydney?
Seek a partner who's privately owned and operates without bank-aligned product quotas. You should look for a fee for service financial planner Australia who utilises an in-house Investment Committee to manage bespoke portfolios. Local expertise in the Sydney market is also essential for accurate lifestyle modelling. Ensure the firm prioritises research-driven strategies over flashy innovation, providing a stabilising presence that allows you to maintain confident oversight of your wealth.
Does fee-for-service advice guarantee better investment returns?
No professional adviser can guarantee specific investment returns, as market performance is inherently unpredictable. Fee-for-service advice instead focuses on optimising what can be controlled: costs, tax efficiency, and risk management. By removing product-based incentives, your adviser can objectively select asset allocations that prioritise stability and capital preservation. The goal is to maximise the probability of achieving your lifestyle goals through disciplined, evidence-based strategy rather than speculative growth.
How often should I review my financial plan with a fee-for-service adviser?
We recommend a formal review of your financial strategy at least once every twelve months. This methodical approach ensures your plan remains resilient against shifting Australian regulations and market fluctuations. You should also trigger a review whenever significant life events occur, such as a career change, inheritance, or family expansion. Continuous oversight allows for the subtle adjustments necessary to keep your long-term projections aligned with your evolving "True North."
What happens during the first meeting with a True North Lifestyle adviser?
Your initial consultation is a structured discovery process focused on your personal lifestyle goals. We begin by reviewing your current financial landscape and identifying any sources of anxiety or complexity. This meeting isn't a sales pitch; it's a professional consultation designed to see if our research-driven methodology aligns with your needs. We focus on understanding the human outcomes you desire, allowing us to eventually simplify the complex into a manageable, actionable path forward.


