

With the General Transfer Balance Cap reaching $2.1 million in July 2026, many Sydney residents are discovering that their long-term financial structures are no longer as efficient as they once were. It is a confronting reality. When implementing tax effective retirement strategies Sydney presents a distinct landscape where high property values and shifting superannuation caps can quickly erode your hard-earned wealth. You want to ensure your capital lasts as long as you do, yet the constant flux of tax rules often creates more questions than answers.
We believe that complex financial decisions should lead to clarity, not confusion. It's possible to secure your future without the constant worry of leaving a tax bill for your children or falling short of your lifestyle goals. This guide delivers a research-driven roadmap for legally minimising tax and maximising your retirement income. We'll outline how to integrate superannuation, property, and bespoke portfolio construction into a singular, cohesive plan that provides the stability and tax-free income you deserve.
Key Takeaways
- Understand why structural discipline is essential in the 2026 tax environment to protect your capital from high Sydney living costs.
- Learn how to navigate the $2.1 million Transfer Balance Cap and maximise contribution limits through tax effective retirement strategies Sydney residents can implement today.
- Discover the transition from accumulation to the pension phase, turning your superannuation into a tax-free income stream that supports your lifestyle.
- Explore advanced re-contribution techniques designed to eliminate the 17% "death tax" and protect your children's inheritance.
- See how bespoke retirement modelling replaces generic advice with a clear, low-volatility roadmap tailored to your specific financial goals.
The Evolving Landscape of Retirement Taxation in Sydney
Structure brings stability. For many, the concept of a tax-effective retirement is often misunderstood as a series of clever loopholes or aggressive avoidance. In reality, it's a disciplined exercise in financial architecture. When we design tax effective retirement strategies Sydney residents can rely on, we're looking for order within a complex legislative environment. It's about ensuring your assets are positioned correctly to withstand the pressures of a shifting economy. As a "Steady Navigator," our role is to replace the inherent anxiety of these changes with a clear, logical path forward.
Local expertise matters. Planning for a retiree in Miranda or the Sydney CBD requires a different lens than a generic national strategy. High-net-worth individuals in these areas often face unique challenges, from managing significant property portfolios to navigating the $2.1 million General Transfer Balance Cap effective from July 2026. A foundational understanding of Superannuation in Australia is essential, but the application must be bespoke. We focus on the human outcome, ensuring your wealth preservation strategy is as sophisticated as the life you've built.
Understanding the 2026 Tax Thresholds for Retirees
Clarity through data. In 2026, the tax-free threshold remains a vital component of any plan, but it's only the starting point. For many Sydney residents, the interaction between the Seniors and Pensioners Tax Offset (SAPTO) and their superannuation income determines their true net position. We've seen how high property values in the Sydney market can inadvertently create liquidity issues. Land tax obligations on investment properties can erode retirement income if not modelled correctly. We use precise projections to identify these friction points early, allowing for structural adjustments before they impact your lifestyle.
The Interplay Between Tax and Sydney Living Costs
Context is everything. A strategy that works in a regional centre often fails in the Sydney market because it ignores the "Sydney premium." The cost of maintaining a home and lifestyle in the CBD or the Sutherland Shire requires a higher level of liquid cash flow. Balancing tax minimisation with this need for liquidity is a delicate process. Longevity risk in the context of Sydney inflation is the mathematical probability that an individual's financial resources will be depleted before their death, exacerbated by the unique cost-of-living pressures found in the New South Wales capital. We prioritise portfolio sustainability to ensure your capital remains a reliable anchor throughout your later years.
Superannuation Optimisation: The Engine Room of Tax Efficiency
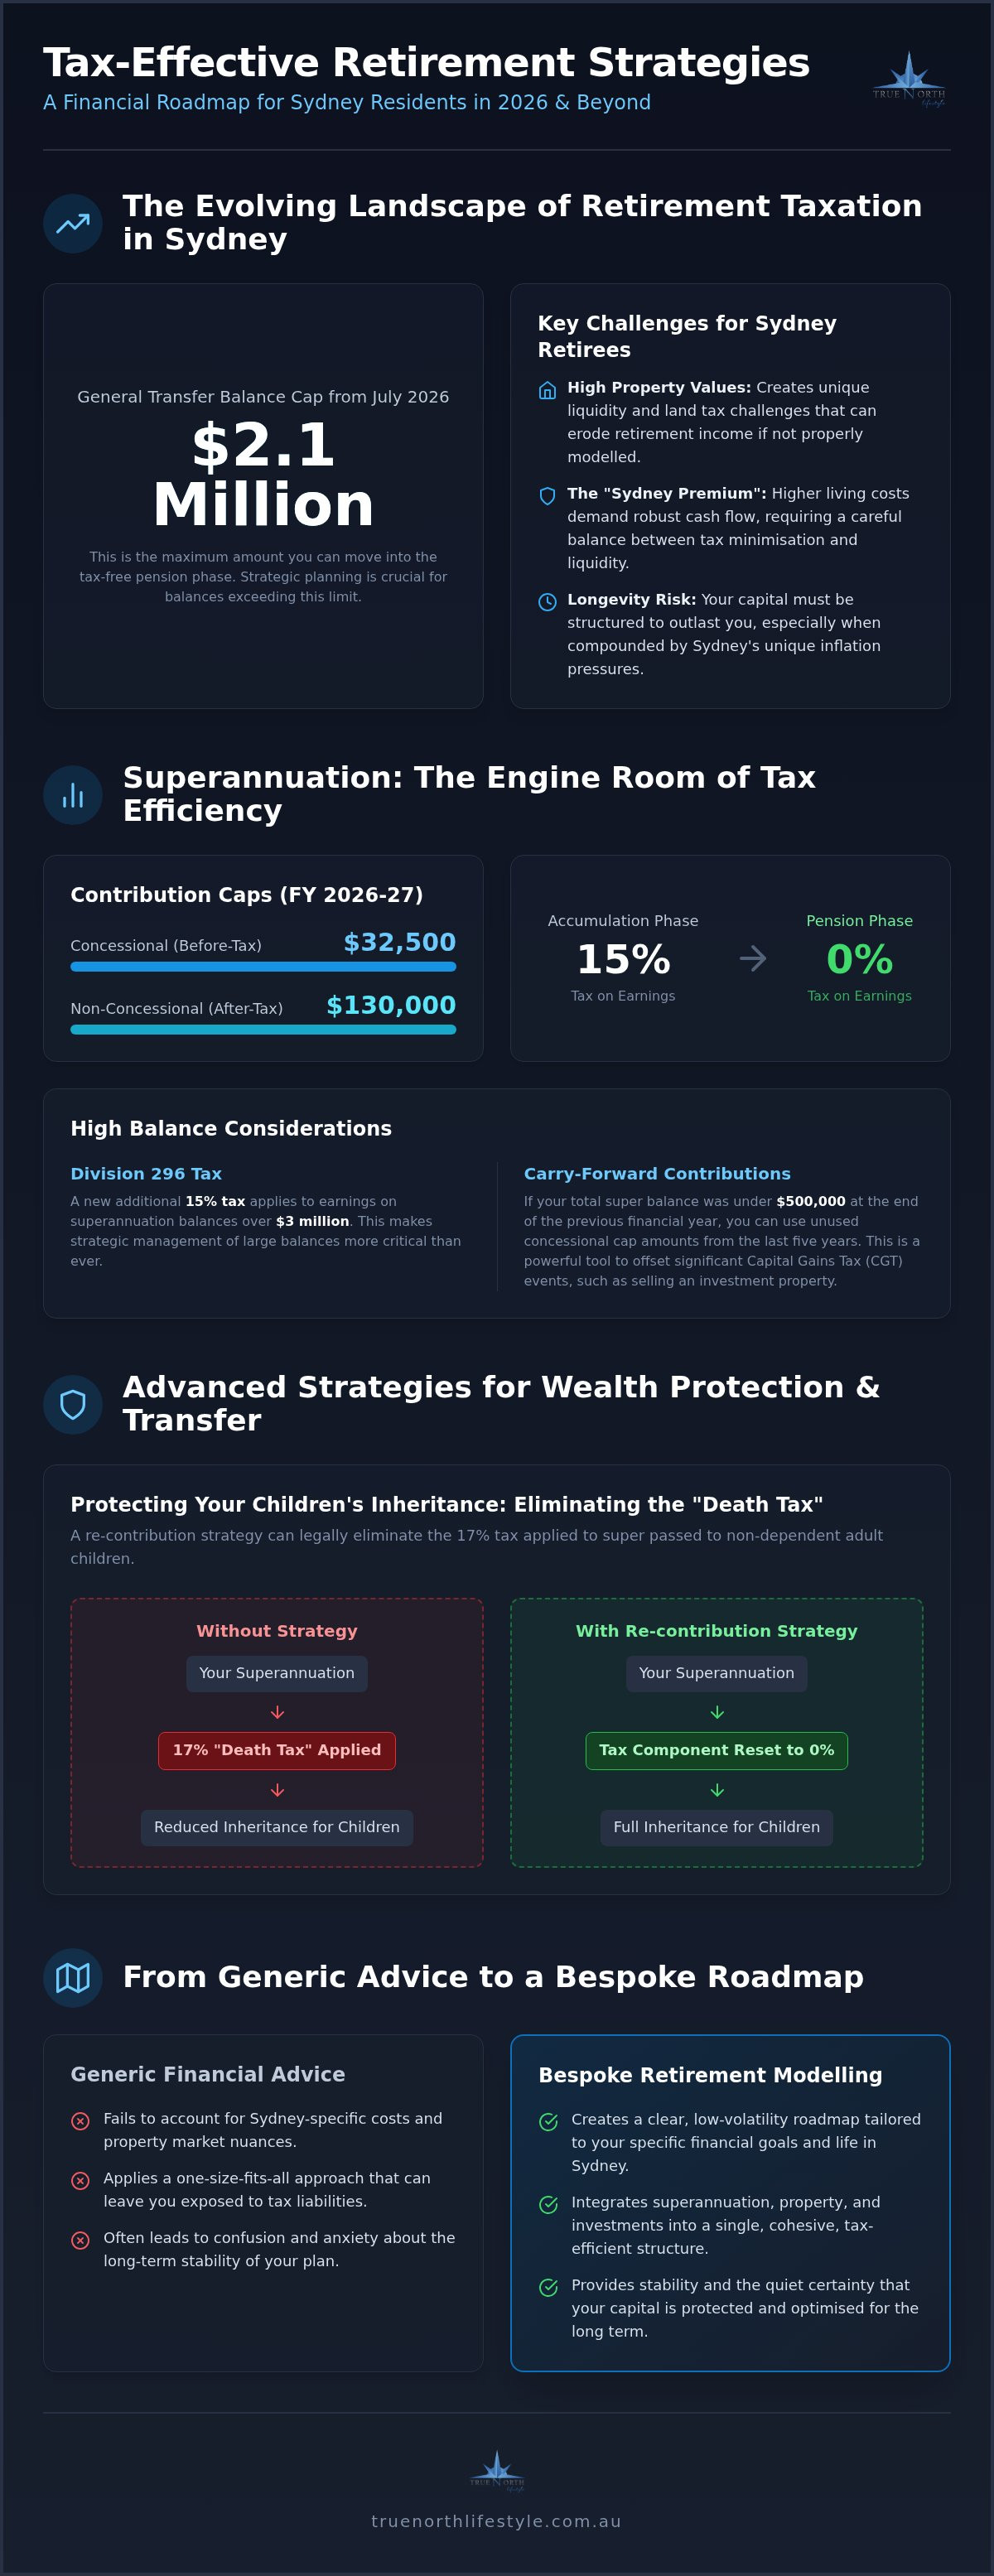
Efficiency starts here. Superannuation remains the most powerful tool for tax effective retirement strategies Sydney families can utilise to build and protect their wealth. For the 2026-2027 financial year, the concessional contributions cap has moved to $32,500, while the non-concessional cap sits at $130,000. Understanding how super works at a structural level allows you to shield more of your wealth from the top marginal tax rates. It's a process of moving capital from a high-tax environment into one where earnings are taxed at just 15% or, eventually, 0%.
Structure requires precision. The $2.1 million General Transfer Balance Cap, effective from 1 July 2026, represents a significant ceiling in your planning. This is the maximum amount you can move into the tax-free pension phase. For those with balances exceeding this limit, strategic oversight is required to manage the excess. We focus on modelling these outcomes to ensure you don't fall foul of the Division 296 tax, which adds an additional 15% tax on earnings for balances over $3 million. Our role is to provide the quiet certainty that your caps are maximised without overstepping regulatory boundaries.
Catch-up Contributions and Timing Strategies
Timing is everything. The "carry-forward" rule allows you to use unused concessional cap amounts from the previous five years, provided your total super balance was under $500,000 at the end of the prior financial year. This is particularly effective for Sydney residents who have recently sold an investment property and are facing a significant Capital Gains Tax (CGT) bill. By making a large "catch-up" contribution, you can offset a portion of that gain, effectively turning a tax liability into a retirement asset. Our superannuation advice Sutherland Shire services focus on this precise modelling to find your specific contribution "sweet spot."
SMSF vs Industry Funds: A Sydney Perspective
Choice dictates outcome. While industry funds offer simplicity, a Self-Managed Super Fund (SMSF) often provides greater tax transparency and control for high-net-worth individuals. In an SMSF, you can manage the timing of asset disposals to optimise CGT outcomes, a level of granularity rarely found in pooled funds. We look at bespoke portfolio management to ensure your super fund isn't just a holding pen, but a high-performance vehicle. If you're looking for a partner to review your current structure, our team provides the superannuation review and optimisation needed to ensure your fund is truly fit for purpose.
Transition to Retirement (TTR) and Pension Phase Structuring
Structure creates freedom. For those approaching the end of their primary career, the transition period is often fraught with unnecessary complexity. A Transition to Retirement (TTR) strategy serves as a bridge, allowing you to access a portion of your superannuation once you reach your preservation age, which is 60 for anyone born after 1 July 1964. When we implement tax effective retirement strategies Sydney professionals can use to ease into their next chapter, the goal is twofold: reducing your current tax liability while simultaneously bolstering your super balance. It is a sophisticated balancing act that requires precise mathematical modelling to ensure your lifestyle remains uninterrupted.
The distinction between phases is vital for long-term wealth preservation. While earnings on assets supporting a TTR pension are taxed at up to 15%, the move to a full account-based pension represents a significant milestone where all investment earnings within the fund become entirely tax-free. Managing this shift requires a deep understanding of the General Transfer Balance Cap, which stands at $2.1 million as of July 2026. Staying within this limit is essential to avoid excess transfer balance tax, ensuring that your most productive assets remain shielded from the broader tax system.
TTR Strategies for Miranda Professionals
Efficiency through coordination. Consider a professional in Miranda earning a high salary who wishes to reduce their working hours without sacrificing net income. By pairing salary sacrifice contributions up to the $32,500 concessional cap with a TTR income stream, they effectively swap high-taxed salary for lower-taxed pension payments. This strategy "recycles" income through the low-tax super environment. Professional oversight is critical here; a single administrative error or an accidental breach of contribution caps can lead to significant tax penalties that erode the very benefits you're trying to create.
Optimising Account-Based Pensions for Longevity
Stability for the long term. Once you fully retire or reach age 65, your super moves into the pension phase, triggering the requirement for minimum annual drawdowns. For those aged 60 to 64, this minimum is typically 4% of your account balance. We focus on structuring these income streams so they complement your non-super investments, such as Sydney property or private share portfolios. This integrated approach ensures you aren't drawing down on volatile assets during market dips. For a deeper look at sustaining your lifestyle, our guide to retirement planning Sydney provides the framework needed for true financial longevity.
Advanced Techniques: Re-contribution and Wealth Transfer
Legacy matters deeply. Many retirees are unaware that their superannuation often carries a hidden tax liability for their adult children. Non-dependant beneficiaries typically face a 17% tax (including the Medicare levy) on the taxable component of an inherited super balance. By implementing a re-contribution strategy, you can "wash" these funds. This involves withdrawing a portion of your super and re-contributing it as a tax-free non-concessional contribution. It's one of the most impactful tax effective retirement strategies Sydney families can use to ensure their wealth remains with their loved ones rather than the tax office.
Strategic gifting also plays a role in wealth transfer. However, you must be mindful of the five-year deprivation rules set by Centrelink. Gifting more than $10,000 in a single financial year, or $30,000 over a rolling five-year period, can result in those funds still being counted under the asset test. This requires a disciplined approach to timing and documentation. For a comprehensive look at these mechanics, see our detailed guide on tax planning for retirement Australia.
Estate Planning and Intergenerational Tax Minimisation
Protecting family wealth requires more than a simple will. A Testamentary Trust, established through your estate planning process, provides a robust structure for managing assets after you pass. It offers significant tax advantages for beneficiaries, particularly when distributing income to minors at adult tax rates. Avoiding the common pitfall of basic asset distribution can prevent unnecessary tax leakage during the transfer of wealth. Explore our insights on wealth transfer strategies Australia to secure your family's future.
Centrelink Structuring for Sydney Retirees
Sydney asset values are often high. While the family home is usually exempt from the Age Pension asset test, other investments can quickly push you over the thresholds. We look at specific instruments, such as funeral bonds up to the current limit or certain lifetime annuities, which can reduce your assessable assets and potentially improve your pension eligibility. True North provides the detailed modelling required to see how these choices impact your long-term cash flow and net tax position. If you're ready to protect your legacy, we invite you to review your estate planning strategy with our specialist team.
Securing Your Future with True North’s Bespoke Modelling
Clarity replaces concern. While understanding the mechanics of superannuation and tax legislation is vital, the true value lies in the precise application of those rules to your unique life. Generic financial advice often fails to account for the specific nuances of your goals, family structure, and lifestyle expectations. When we develop tax effective retirement strategies Sydney residents can rely on, we move beyond broad generalisations to create a bespoke retirement roadmap. This is a living document, designed to evolve as your needs change and as the Australian regulatory landscape shifts.
Stability is our priority. Our team, operating from our offices in Miranda and the Sydney CBD, acts as your "Steady Navigator" through the complexities of wealth preservation. We understand that for high-net-worth individuals, the goal isn't just growth; it's the quiet certainty that your capital is protected and your income is sustainable. Ongoing advisory is essential in this environment. With the introduction of the Division 296 tax and the shifting Transfer Balance Caps in 2026, having a partner who has already done the heavy lifting and rigorous testing allows you to step into a role of confident oversight.
Research-Driven Portfolio Construction
Evidence guides every choice. For 2026, our investment philosophy remains firmly rooted in stability and income generation. We don't chase flashy innovation; instead, we value proven outcomes and real-world probability. This approach is bolstered by our in-house Investment Committee and our strategic collaboration with Resonant Asset Management. By focusing on low-volatility, income-focused portfolios, we ensure that your retirement isn't subject to the whims of market turbulence. If you're seeking a structured approach to your wealth, explore our bespoke investment advice Sydney to see how we craft stability for your specific lifestyle.
Your Path to a Calm Retirement in Sydney
Confidence begins with a conversation. In your initial retirement modelling session, we perform a deep dive into your current position, using sophisticated projections to map out your long-term cash flow and tax obligations. We replace financial anxiety with a sense of order, showing you exactly how your assets will support you over the coming decades. It's a transparent process that moves you from uncertainty toward a well-defined path. We invite you to take the first step toward a protected future and book a consultation at our Miranda or Sydney offices today.
Charting Your Path to Financial Clarity
Order brings peace. Throughout this guide, we've explored how structural discipline and proactive planning can shield your wealth from unnecessary tax leakage. From maximising the $2.1 million Transfer Balance Cap to utilising sophisticated re-contribution strategies to protect your beneficiaries, the goal remains the same: quiet certainty in an ever-shifting environment. Implementing tax effective retirement strategies Sydney families can rely on requires a move away from generic advice toward a research-driven, bespoke roadmap.
Our team in Miranda and the Sydney CBD is dedicated to providing the high-level professional authority you need to navigate these complex waters. We specialise in bespoke retirement modelling and complex wealth transfer techniques that ensure your legacy is preserved for the next generation. It's time to replace financial anxiety with a structured plan built on evidence and stability. Secure your tax-effective retirement roadmap with True North Lifestyle today. You've worked hard to build your future; we're here to help you protect it with confidence.
Frequently Asked Questions
What are the most tax-effective retirement strategies for Sydney residents in 2026?
The most effective approach involves a combination of superannuation optimisation, Transition to Retirement (TTR) income streams, and strategic re-contribution. When implementing tax effective retirement strategies Sydney residents should focus on moving capital into the tax-free pension phase. By utilising the $32,500 concessional contribution cap and the $130,000 non-concessional cap, you can shield earnings from high personal tax rates. This structural discipline ensures your wealth is positioned for long-term sustainability and growth.
How does the superannuation re-contribution strategy work?
This strategy involves withdrawing a portion of your superannuation after reaching preservation age and re-contributing it as a non-concessional contribution. It effectively "washes" the taxable component of your super, converting it into a tax-free component. This process is essential for estate planning, as it can eliminate the 17% tax otherwise levied on non-dependant beneficiaries. Precise modelling is required to ensure you stay within the $130,000 annual non-concessional cap or the $390,000 bring-forward limit.
Can I still use a Transition to Retirement (TTR) strategy to save tax?
Yes, TTR remains a valuable tool for those who have reached their preservation age of 60. By starting a TTR pension, you can access your super earnings, which are taxed at a maximum of 15%, to supplement your income. This allows you to increase salary sacrifice contributions into your super fund, effectively recycling your income through a lower-tax environment. It's a sophisticated way to bolster your retirement savings while maintaining your current lifestyle in Sydney.
What is the Transfer Balance Cap for 2026 and how does it affect me?
From 1 July 2026, the General Transfer Balance Cap is $2.1 million. This cap limits the total amount of superannuation you can transfer into a tax-free retirement phase income stream. If your balance exceeds this threshold, the excess must remain in the accumulation phase, where earnings are taxed at 15%. Understanding your personal cap is vital, especially with the introduction of the Division 296 tax on balances over $3 million, to avoid unnecessary tax penalties.
How can I minimise the tax my children will pay on my superannuation?
You can significantly reduce this burden by using the re-contribution strategy to increase the tax-free component of your superannuation balance. Adult children are considered non-dependants for tax purposes and typically pay 17% tax on the taxable portion of an inherited super death benefit. By restructuring your account components while you're still alive, you ensure that more of your hard-earned wealth remains with your family rather than being lost to the Australian Taxation Office.
Are there specific tax benefits for Sydney business owners retiring in 2026?
Sydney business owners can often access significant Small Business CGT concessions when selling their enterprise to fund retirement. These concessions can potentially allow you to disregard or defer capital gains, provided specific eligibility criteria are met. We focus on integrating these concessions into your broader retirement roadmap. This ensures that the proceeds from your business sale are contributed to superannuation in the most tax-efficient manner possible, maximising your eventual tax-free pension income.
How do Sydney property values affect my Age Pension eligibility?
While your principal place of residence is generally exempt from the Age Pension asset test, the high value of other Sydney-based investments can impact your eligibility. As of September 2026, the full Age Pension rate for a single person is $1,237.70 per fortnight. If your non-exempt assets, such as holiday homes or share portfolios, exceed the thresholds, your pension may be reduced. We use detailed modelling to restructure assets and potentially improve your pension outcomes.
Why should I seek professional advice for tax minimisation instead of doing it myself?
The Australian retirement landscape is becoming increasingly complex with the introduction of new taxes like Division 296 and changing contribution caps. Professional advice provides the "Steady Navigator" approach needed to manage these shifts without feeling overwhelmed. We offer bespoke modelling that generic calculators cannot replicate, ensuring your strategy accounts for Sydney's high cost of living. This clarity replaces financial anxiety with a structured path, protecting your estate from avoidable tax leakage and ensuring longevity.


