

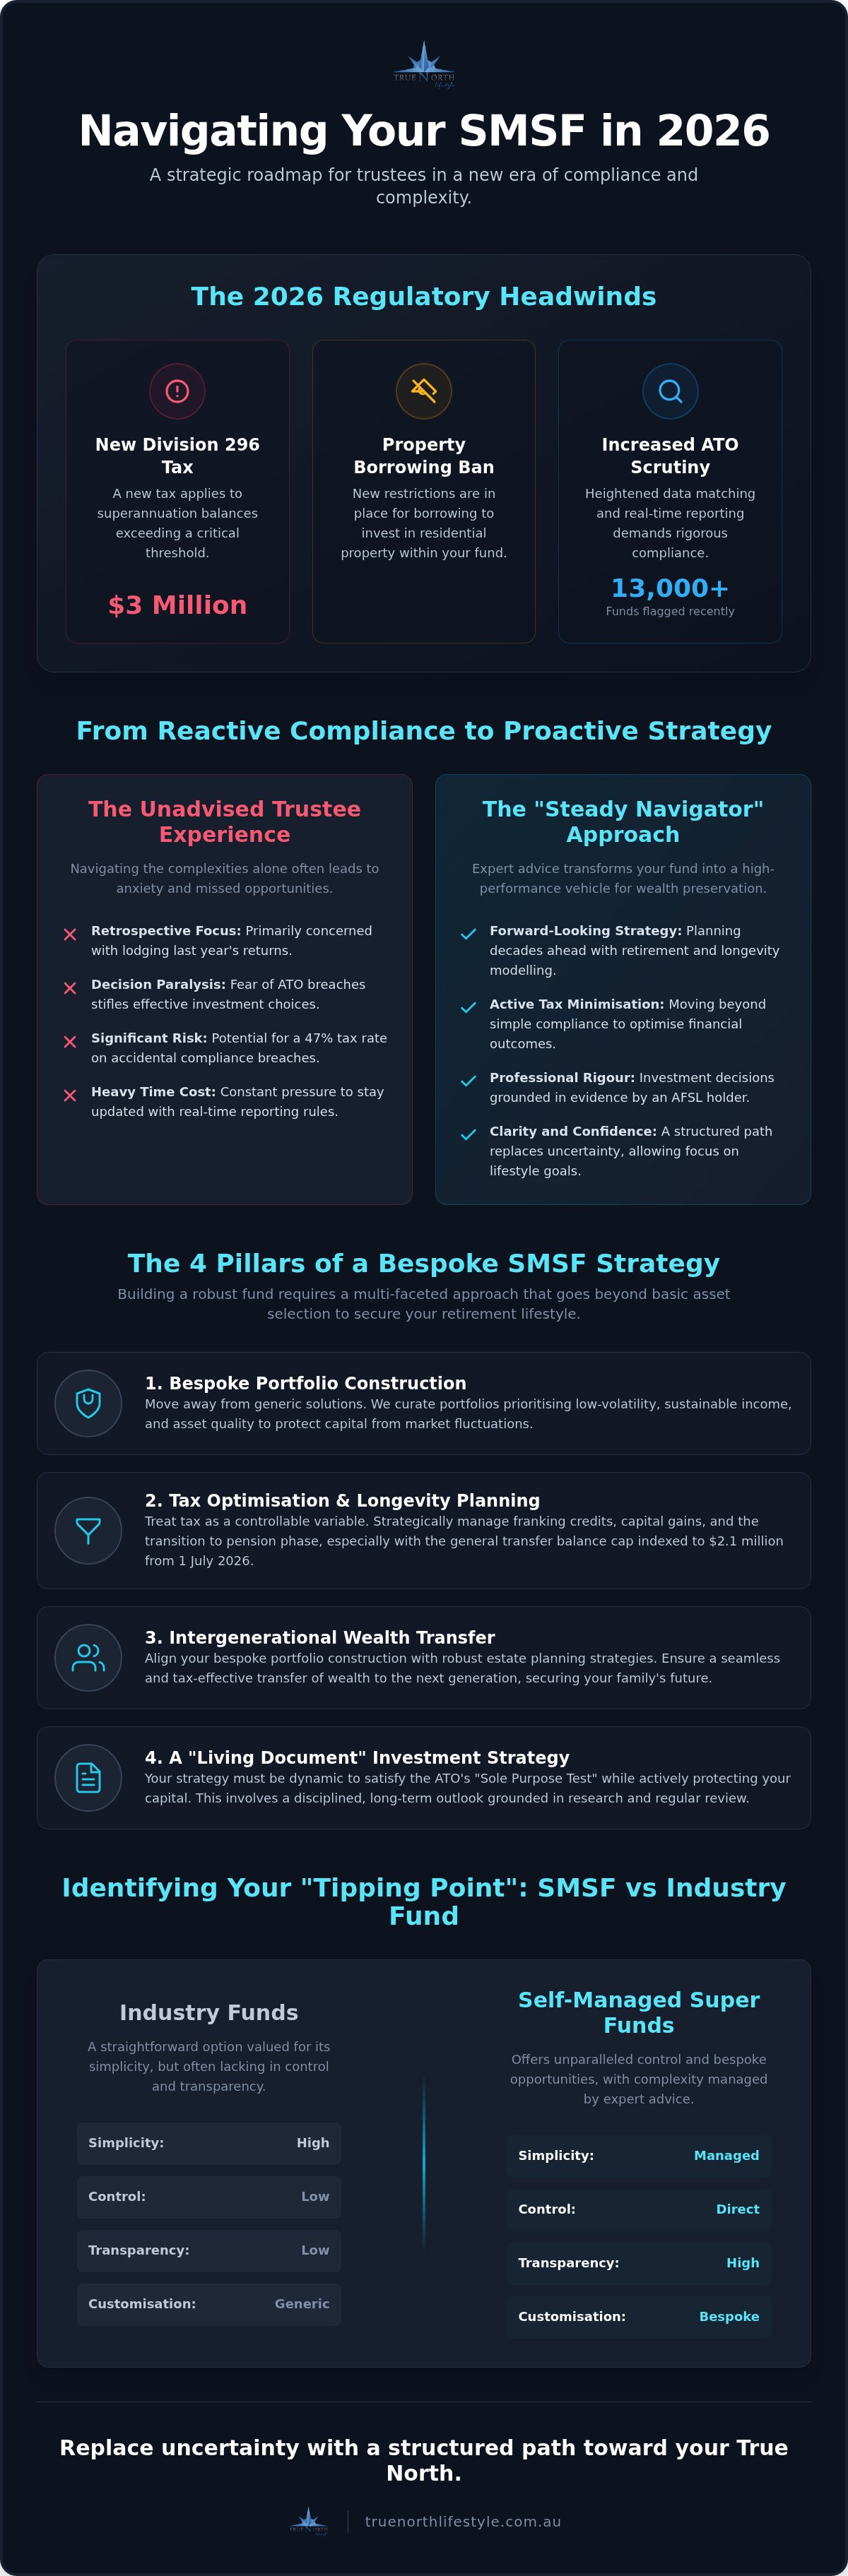
What if the very vehicle designed to secure your future has become a source of quiet anxiety rather than confidence? It's a common sentiment in 2026. With the introduction of the Division 296 tax on balances exceeding $3 million and the ban on new residential property borrowing, the landscape of self-managed super has shifted. You likely sought autonomy to escape the lack of transparency in industry funds, yet you now find yourself managing a complex web of ATO compliance and market volatility. We understand this frustration. It's difficult to maintain a steady course when the rules of the sea keep changing.
Order and clarity. Expert smsf advice can restore your sense of control by moving beyond mere compliance. By partnering with a steady navigator, you can transform your fund into a sophisticated, bespoke vehicle for lifestyle security and significant tax minimisation. This guide provides a clear roadmap for the year ahead. We will explore how research-driven portfolio construction, longevity modelling, and strategic wealth transfer can replace uncertainty with a structured path toward your True North.
Key Takeaways
- Understand why the 2026 regulatory environment, including new tax thresholds, makes professional smsf advice essential for maintaining fund compliance and performance.
- Learn how retirement modelling and longevity planning provide a clear projection of your future, ensuring your contribution strategy is optimised for long-term security.
- Identify the specific "tipping point" where the benefits of direct investment control and fee transparency outperform the simplicity of a standard industry fund.
- Discover how to transform your Investment Strategy into a "living document" that satisfies the ATO while actively protecting your capital from market volatility.
- Gain a clear roadmap for intergenerational wealth transfer by aligning your bespoke portfolio construction with robust estate planning strategies.
SMSF Advice in 2026: Why Strategic Guidance is Non-Negotiable
The 2026 financial environment demands more than just record-keeping. It requires foresight. As the Australian superannuation system continues to evolve, the complexity of managing your own fund has reached a critical threshold. The days of simple "DIY" super are fading. With the ATO flagging over 13,000 funds for potential breaches in recent cycles, the margin for error has disappeared. Strategic smsf advice is no longer a luxury; it's a fundamental requirement for those seeking to protect their hard-earned capital from unnecessary tax leakage and regulatory penalties.
Replace anxiety with order. Our "Steady Navigator" approach is designed to bridge the gap between basic compliance and high-performance wealth preservation. Many trustees find themselves overwhelmed by the sheer volume of data matching and real-time reporting now required by the regulator. By implementing a research-driven strategy, we transform that complexity into a structured path. This isn't just about avoiding fines. It's about ensuring your fund remains a bespoke vehicle that actually delivers the retirement lifestyle you've envisioned.
The Distinction Between Administration and Strategic Advice
Clarity precedes confidence. While a tax agent or administrator is essential for lodging annual returns, their role is often retrospective. They look at what happened last year. In contrast, strategic guidance looks decades ahead. It involves retirement modelling and bespoke portfolio construction designed to withstand market volatility while remaining within the strict boundaries of the "Sole Purpose Test."
- Optimised Outcomes: Moving beyond "lodging forms" to active tax-minimisation strategies.
- Professional Rigour: Leveraging the expertise of an AFSL holder to ensure investment decisions are grounded in evidence.
- Intergenerational Focus: Structuring the fund to facilitate seamless wealth transfer to the next generation.
The Cost of "Going it Alone" in a Regulated Environment
Compliance is heavy. The emotional weight of potentially triggering a 47% tax rate through an accidental breach can be overwhelming for unadvised trustees. Beyond the financial risk, there is the time cost of staying current with real-time reporting requirements and the new payday super mandates starting 1 July 2026. Managing these nuances without professional support often leads to "decision paralysis," where fear of the ATO prevents you from making the bold investment choices your retirement requires. Professional smsf advice serves as a vital risk-mitigation tool that ensures Sydney families can focus on their lifestyle goals while we handle the technical rigour of fund sustainability.
The Pillars of a Bespoke SMSF Strategy
A strategy is a living document. It's the DNA of your fund. While many focus solely on staying compliant, the true value of smsf advice lies in creating a roadmap that actively builds wealth while shielding it from unnecessary risks. To meet the "Sole Purpose Test," every investment decision must be justified by its ability to provide retirement benefits for members. This requires a level of technical rigour that goes beyond simple asset selection. It involves deep retirement modelling to ensure your contribution limits and investment choices align perfectly with your projected lifestyle needs.
Bespoke Portfolio Construction for SMSF Trustees
Standard portfolios often fail. They are built for a generic "average" investor, not for your specific family objectives or unique tax position. Off-the-shelf solutions rarely account for the nuances of self-managed funds. We utilise an in-house Investment Committee to curate portfolios that prioritise low-volatility and sustainable income generation. This research-driven methodology is vital in 2026, a year where market fluctuations can quickly derail a poorly constructed plan. By focusing on asset quality and strategic diversification, we replace the anxiety of market timing with a disciplined, long-term outlook. This structured approach ensures your portfolio is built to last, not just to perform in the short term.
Tax Optimisation and Longevity Planning
Tax is a controllable variable. Through professional smsf advice, trustees can navigate complex hurdles such as franking credit refunds, capital gains management, and the transition to the pension phase. With the general transfer balance cap indexed to $2.1 million from 1 July 2026, the stakes for precise planning have never been higher. We also focus heavily on managing sequence of returns risk. This is the specific danger of a market downturn occurring just as you begin your pension, which can significantly deplete your fund's longevity if not managed correctly. Implementing robust tax planning for retirement Australia ensures fund sustainability and provides a predictable income stream for your later years. If you're looking for a partner to help anchor your strategy, our team can help you optimise your superannuation structure for the years ahead according to current ATO SMSF regulations.
SMSF vs Industry Funds: A Comparative Analysis for 2026
Control is the primary driver. For many Sydney professionals, the decision to move away from industry funds isn't just about fees; it's about the tipping point where the desire for transparency outweighs the convenience of a managed product. Industry funds provide a stable environment, but they often lack the granular visibility required for sophisticated wealth preservation. In an SMSF, you don't just own a balanced option. You own specific assets that you can see and manage. This shift requires a significant commitment of time and expertise. As highlighted in ASIC's Moneysmart guide, trustees must be prepared for the legal and financial responsibilities that come with this autonomy. Professional smsf advice helps you determine if your fund has reached the critical mass necessary to make this structure cost-effective, typically when the benefits of bespoke asset selection and tax control outweigh the fixed administration costs.
One of the most distinct advantages in 2026 remains the ability to hold direct property. While the recent ban on new limited recourse borrowing arrangements for residential property has changed the landscape, the ability to hold commercial premises within your fund remains a powerful tool for Sydney business owners. This level of direct ownership is simply not possible within an industry fund framework. By holding your business premises within your super fund, you can create a stable, long-term lease arrangement that benefits both your business and your retirement savings.
When Does the Advice Suggest a Switch?
A thorough superannuation review Australia wide often reveals that as balances grow, the percentage-based fees of industry funds can begin to exceed the flat-fee structure of a well-managed SMSF. However, the switch should never be based on numbers alone. It's about the value of bespoke investment advice Sydney residents need to navigate a volatile market. We look at your time cost. If the burden of compliance is eroding your lifestyle, the convenience of an industry fund might still be the better path. Our role is to provide a clear, evidence-based comparison so you can choose the vehicle that matches your capacity for oversight.
The Flexibility Advantage: Estate Planning and Legacies
Legacy matters. Industry funds are often rigid regarding death benefit nominations, frequently leaving the final decision to the fund trustee's discretion. An SMSF offers unparalleled control over how your wealth is distributed, allowing for non-lapsing nominations that provide absolute certainty for your heirs. This structure is ideal for complex family situations where intergenerational wealth transfer is a priority. By integrating a robust estate planning strategy Australia into your fund's core, you ensure that your family's financial future is protected from unnecessary legal disputes or tax complications. This bespoke approach allows the fund to continue as a family legacy, providing for multiple generations within a single, tax-efficient structure.
Compliance, Control, and the Role of an SMSF Specialist
Autonomy requires discipline. While the primary appeal of a self-managed fund is the freedom to choose your own path, that freedom is bound by a rigorous legal framework. Every investment decision you make carries the weight of "Best Interest" duty. This means you must be able to demonstrate that every transaction was made with the sole intention of providing for your retirement. Professional smsf advice acts as a vital guardrail here, ensuring that your desire for control never compromises your fund's compliance status. We replace the guesswork of trusteeship with a methodical, five-step implementation process: discovery, strategic modelling, structural optimisation, bespoke construction, and ongoing review.
A common mistake is treating the fund's Investment Strategy as a static piece of paperwork. The ATO increasingly views this as a "living document." It must be a genuine reflection of your current risk profile, liquidity needs, and diversification goals. If your strategy hasn't been updated to reflect the volatile market conditions of 2026, it may no longer satisfy the regulator. Our role is to ensure your strategy remains relevant and robust, pre-empting the annual audit process. A "clean" audit report isn't the result of a last-minute scramble in June; it's the outcome of year-round strategic discipline and meticulous record-keeping.
The Trustee Education Journey
Complexity shouldn't lead to confusion. We believe in simplifying the complex by breaking down your legal obligations into manageable, actionable tasks. You don't need to be a technical expert to be an effective trustee, but you do need to be informed. True North Lifestyle acts as the authoritative guide for Sutherland Shire trustees, providing the steady navigation required to stay ahead of legislative shifts. We ensure you understand the "why" behind every compliance requirement, allowing you to step into a role of confident oversight rather than administrative burden.
Risk Management and Portfolio Stress Testing
Passive management is a risk in itself. In a fluctuating economic environment, "set and forget" is perhaps the greatest threat to your long-term security. We apply rigorous portfolio stress testing to identify how your assets might perform under various adverse scenarios. This is particularly important for managing longevity risk, which is the very real danger of outliving your capital. Portfolio sustainability modelling for 2026 provides the necessary evidence to ensure your drawdown rates don't compromise the fund's viability over a thirty-year retirement horizon. To secure your fund's future, it's essential to partner with a specialist who provides professional SMSF advice tailored to your specific lifestyle goals.
True North Lifestyle: Your SMSF Advice Partner in Miranda and Sydney
Stability through structure. True North Lifestyle operates on the principle that the inherent anxiety of managing a high-value superannuation fund can only be replaced by a sense of calm and order when a rigorous methodology is applied. Our approach to smsf advice is grounded in evidence rather than speculation. We don't just look at the numbers; we focus on the human outcomes of every strategic decision. By utilising sophisticated retirement modelling and long-term projections, we provide a clear, evidence-based path that ensures your capital is protected and your lifestyle is secure for the decades ahead.
Local trust matters. Whether you visit our offices in Miranda 2228 or our Sydney CBD centre, you're engaging with a team that values directness and honesty. We understand the unique pressures facing Sydney professionals and business owners. To ensure the highest level of technical rigour, we collaborate closely with Resonant Asset Management. This partnership, alongside our in-house Investment Committee, allows us to construct bespoke portfolios that prioritise low-volatility assets and sustainable income. This isn't about chasing flashy trends. It's about the steady, research-driven construction of wealth that lasts. We act as your authoritative guide, taking the heavy lifting off your shoulders so you can step into a role of confident oversight.
Bespoke Solutions for Sydney Professionals and Families
Tailored excellence is our standard. We specialise in crafting strategies for high-net-worth individuals and business owners who require more than just basic administration. Our commitment to "no-nonsense" value means you receive transparent advice fees and a dedicated partner who has already done the heavy lifting and rigorous testing of your strategy. We avoid the fluff of corporate jargon, focusing instead on logic and proven outcomes. If you're seeking a local anchor for your financial journey, our team provides the expert superannuation advice Sutherland Shire residents rely on for long-term clarity and wealth preservation.
The Next Steps to Clarity and Confidence
Your journey begins with a conversation. During your initial strategy consultation, we focus on identifying your True North and understanding the specific lifestyle goals you wish to achieve. We map your future using detailed financial projections that account for various market scenarios and longevity risks. This process moves you from a state of uncertainty toward a well-defined, structured path. We invite you to discover the retirement planning Sydney advantage and see how a disciplined, research-focused partner can transform your self-managed super into a bespoke vehicle of quiet certainty.
Navigating Your Path to Retirement Certainty
The landscape of self-managed super has fundamentally shifted. In 2026, the transition from simple administration to high-level strategic oversight is essential for any trustee seeking true wealth preservation. We've explored how professional smsf advice replaces the anxiety of regulatory complexity with a structured, evidence-based roadmap. By prioritising bespoke portfolio construction and rigorous retirement modelling, you can ensure your fund remains a resilient vehicle for your family's future legacy.
Clarity is within reach. Our in-house Investment Committee and research-driven methodology are designed to provide the stability you need in a fluctuating market. Whether you join us at our Miranda or Sydney CBD offices, our team is ready to help you simplify the complex and secure your long-term lifestyle goals. Secure your retirement legacy with expert SMSF advice from True North Lifestyle. Your journey toward quiet financial certainty starts with a single, well-informed step.
Frequently Asked Questions
Is SMSF advice tax-deductible in Australia?
Ongoing strategic smsf advice is typically tax-deductible when paid by the fund, as it's an expense incurred in the production of assessable income. However, the initial cost of establishing the fund is generally considered a capital expense and is not deductible. It's vital to distinguish between upfront setup costs and the recurring advisory fees associated with portfolio construction and retirement modelling. Always ensure these fees are documented correctly within your fund's annual financial statements.
How much super do I need to make an SMSF worthwhile in 2026?
There is no legislated minimum balance; however, a combined balance of $500,000 is often cited as the tipping point where an SMSF becomes cost-competitive with industry funds. In 2026, the complexity of compliance and the increase in the annual ATO supervisory levy to $295 mean that smaller balances may find the fixed costs disproportionate. We assess suitability based on your specific goals, the complexity of your assets, and your capacity for trustee oversight.
Can an SMSF adviser also act as my fund auditor?
No, your adviser cannot perform your annual audit. To maintain the integrity of the regulatory framework, an SMSF auditor must be completely independent of the fund's administration and advisory services. This separation ensures an objective review of your fund's compliance with ATO regulations. While we provide the strategic roadmap and investment oversight, we work alongside independent auditors to ensure your fund receives a fair and transparent assessment every year.
What is the difference between an SMSF accountant and an SMSF financial adviser?
The primary difference lies in the scope of their guidance. An accountant typically focuses on historical record-keeping, tax return preparation, and annual compliance. A financial adviser provides forward-looking smsf advice, focusing on retirement modelling, bespoke portfolio construction, and wealth preservation strategies. While the accountant ensures you stay within the lines of current law, the adviser maps your long-term path, helping you navigate market volatility and lifestyle transitions with confidence.
Can I use my SMSF to buy a residential investment property in Sydney?
You can still hold residential property within your fund if it's purchased outright; however, as of June 2026, new limited recourse borrowing arrangements (LRBAs) for residential property are banned. Existing arrangements are grandfathered. This change requires a strategic shift toward liquidity and diversification. Commercial property remains an option for borrowing, which can be particularly advantageous for Sydney business owners looking to hold their premises within a tax-efficient superannuation structure.
What happens if my SMSF is found to be non-compliant by the ATO?
Non-compliance can lead to severe financial consequences. The ATO has the power to issue administrative penalties, freeze fund assets, or, in extreme cases, declare the fund non-complying. This results in the fund's assets being taxed at the highest marginal rate of 45% plus levies, effectively 47%. Professional guidance is designed to prevent these outcomes by ensuring every investment decision satisfies the "Sole Purpose Test" and meets all reporting deadlines.
How often should I review my SMSF investment strategy with my adviser?
You should review your investment strategy at least once a year or whenever your personal circumstances significantly change. The ATO views the investment strategy as a "living document" that must reflect current market conditions and the specific needs of all members. Regular reviews allow us to perform portfolio stress testing and adjust your asset allocation in response to the volatility expected in the 2026 market, ensuring your plan remains robust.
Can I manage my own SMSF without any professional advice?
You can manage your fund independently, but the legal and financial risks are substantial. Trustees are personally liable for all fund decisions and must stay current with complex legislative changes, such as the new Division 296 tax on balances over $3 million. Without professional support, many trustees find themselves overwhelmed by administrative burdens and ATO reporting requirements. Engaging an expert provides a steady navigator to handle the technical rigour, allowing you to focus on your lifestyle goals.


