

Confidence in retirement isn't a feeling you wait for; it's a structural outcome you build. For many Australians, the transition from accumulation to drawdown feels like stepping into a fog of longevity risk and complex Centrelink rules. You've likely spent decades building your wealth, yet the fear of running out of capital or being eroded by inflation remains a constant weight. This guide breaks down exactly how to retire with confidence by transforming that anxiety into a disciplined, research-driven strategy.
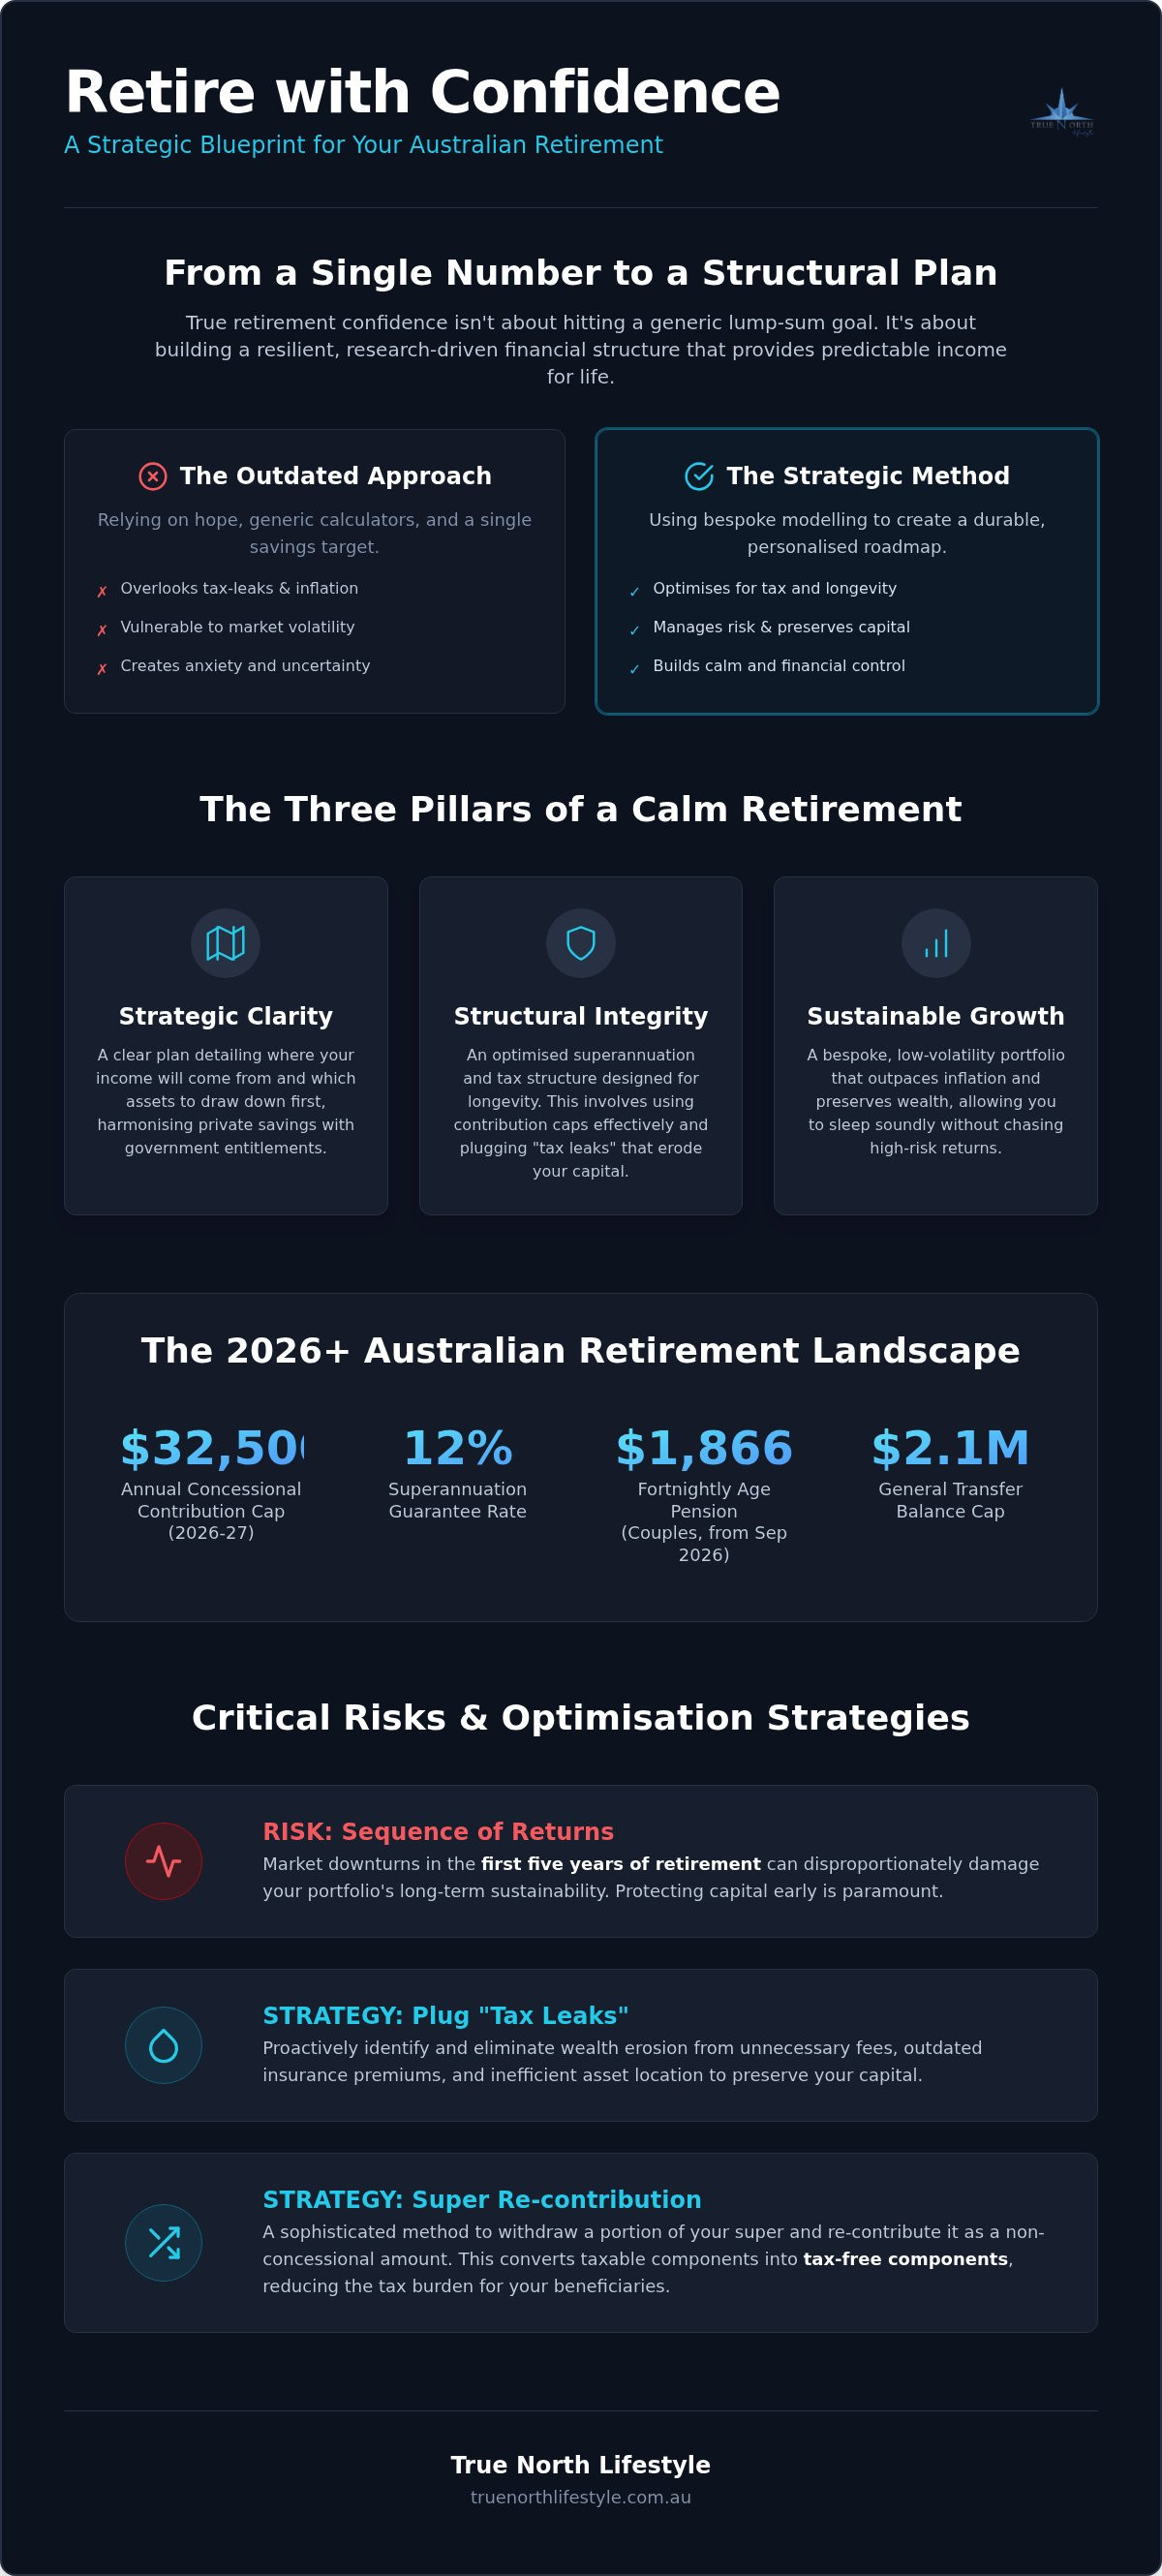
We understand that the current financial environment, with its shifting $32,500 concessional contribution caps and the 12% Superannuation Guarantee, requires more than just a generic calculator. You'll discover how to navigate the 2026 landscape using bespoke modelling that prioritises wealth preservation and tax optimisation. We'll preview the essential pillars of a sustainable roadmap, including how to manage the $2.1 million general transfer balance cap and structure your assets to enjoy the lifestyle you've earned with absolute certainty.
Key Takeaways
- Understand why a single lump-sum figure is often a misleading target and how bespoke modelling provides a more accurate roadmap for your financial future.
- Learn how to retire with confidence by identifying common "tax leaks" and optimising your superannuation structure for the 2026 regulatory environment.
- Discover the critical difference between generic fund calculators and strategic projections that account for inflation, healthcare costs, and market volatility.
- Protect your lifestyle from "sequence of returns risk" by focusing on the first five years of your retirement journey, where portfolio sustainability is most vulnerable.
- Shift from being an anonymous member of a retail fund to having a bespoke, low-volatility investment strategy tailored to your specific family goals.
Beyond the Super Balance: What it Means to Retire with Confidence
Clarity creates calm. Most people view retirement through the lens of a single, static number. However, the "enough" question is rarely solved by a balance alone. True confidence exists at the intersection of your lifestyle aspirations and mathematical probability. It's about replacing the fragile emotion of hope with a research-driven architecture that accounts for the variables you cannot control. Understanding how to retire with confidence is about moving beyond the "accumulation" mindset of simply saving more, and instead focusing on how those savings will be structured to provide a predictable income for thirty years or more.
The foundation of Superannuation in Australia provides a robust starting point, yet the complexity of the legislative system often breeds more confusion than certainty. Relying on a generic fund calculator often overlooks the nuances of tax-minimisation and bespoke portfolio construction. While the Association of Superannuation Funds of Australia (ASFA) suggests a lump sum of $730,000 for a couple to live comfortably, this figure assumes home ownership and specific spending habits that may not mirror your personal aspirations. Real certainty comes from knowing your specific strategy is resilient enough to withstand market downturns and rising living costs.
The Psychology of Financial Certainty
Structure follows logic. The transition from the accumulation phase to the decumulation phase is one of the most significant psychological shifts you'll ever make. During your working life, market volatility is often an opportunity to buy assets at a discount. As you approach the finish line, that same volatility can feel like a direct threat to your future security. Retirement confidence is a state of informed oversight where your lifestyle goals are supported by rigorous, evidence-based financial modelling. By visualising various scenarios, you can replace the anxiety of the unknown with a sense of order and control over your financial destiny.
The Three Pillars of a Calm Retirement
- Strategic Clarity: This involves knowing exactly where your income will come from and which assets to draw down first. It requires modelling that accounts for the September 2026 Age Pension rates of $1,866.00 per fortnight for couples, ensuring your private savings and government entitlements work in harmony.
- Structural Integrity: Your superannuation and tax settings must be reviewed to ensure they are optimised for longevity. With the concessional contributions cap set at $32,500 for the 2026-27 financial year, there are precise windows of opportunity to reduce your tax liability and prevent "tax leaks" that erode your capital.
- Sustainable Growth: You need a portfolio that outpaces inflation while maintaining a risk profile that allows you to sleep soundly. This means constructing a bespoke portfolio that focuses on wealth preservation rather than chasing high-risk returns that could derail your 30-year plan.
The Mechanics of Certainty: Superannuation and Tax Optimisation
Efficiency is silent wealth. While a large super balance is a traditional goal, the structural efficiency of that capital determines your actual lifestyle. In 2026, the legislative environment has evolved, making your choice of fund and tax positioning more critical than ever for your net income. Identifying "tax leaks" within your portfolio is a fundamental step in understanding how to retire with confidence. These leaks often appear as unnecessary fees, outdated insurance premiums, or poor asset location that fails to take advantage of tax-free thresholds.
For couples, the superannuation re-contribution strategy remains a sophisticated tool for wealth preservation. It involves withdrawing a portion of your super and contributing it back as a non-concessional amount, effectively converting taxable components into tax-free ones. This process reduces the potential tax burden on non-dependant beneficiaries, such as adult children, while keeping your capital within the tax-sheltered super environment. It's a prime example of how technical modelling can create a superior outcome compared to a generic "set and forget" approach.
If you're still in the workforce but approaching your desired finish line, a Transition to Retirement (TTR) strategy can bridge the financial gap. By accessing a portion of your super while continuing to work, you can often boost your final balance through salary sacrifice, provided you stay within the $32,500 concessional cap for the 2026-27 financial year. This allows you to maintain your lifestyle while aggressively building your nest egg in a tax-effective manner.
Optimising Your Superannuation for 2026
Small percentages matter. Over a thirty-year retirement, even a 0.5% difference in management fees or unnecessary insurance premiums can erode hundreds of thousands of dollars from your capital. It's essential to ensure your investment choice aligns precisely with your specific retirement date rather than a generic "balanced" or "growth" setting. For those seeking local expertise, our superannuation advice Sutherland Shire services focus on aligning your portfolio with your bespoke lifestyle roadmap to ensure every dollar is purposeful.
Tax Minimisation: Keeping More of Your Hard-Earned Wealth
Preserve what you've built. Strategic tax planning directly extends the life of a retirement fund by ensuring every dollar of growth is protected from unnecessary leakage. This includes managing Capital Gains Tax (CGT) when rebalancing your portfolio and understanding how the $2.1 million general transfer balance cap affects your pension phase. By focusing on wealth preservation, you ensure that your capital works harder for you, not the tax office. If you're unsure where to start, reviewing your portfolio sustainability can reveal hidden opportunities for optimisation.
Strategic Modelling vs. Simple Calculators: Visualising Your Financial Longevity
Precision replaces guesswork. While many retail super funds provide basic tools that estimate your balance in three simple steps, these straight-line projections often ignore the volatile reality of the Australian market. A simple calculator assumes your investments grow by a fixed percentage every single year, but real-world retirement is never a straight line. Understanding how to retire with confidence requires a more sophisticated approach that accounts for the sequence of returns, fluctuating inflation, and the rising costs of healthcare as you age.
Visualising your financial future involves identifying the "Income Gap"—the difference between your desired lifestyle spending and your projected sustainable income. By mapping this gap early, you can take proactive steps to close it before you stop work, such as adjusting your contribution levels or rebalancing your asset allocation. A critical part of this process is stress-testing your strategy. We model "black swan" events, such as a 20% market dip in your first year of retirement, to ensure your portfolio has the structural integrity to recover without forcing a drastic change to your lifestyle.
The Power of Cash Flow Modelling
Structure creates freedom. Effective cash flow modelling separates your essential living expenses from your discretionary "lifestyle" spending, such as international travel or home renovations. This granular view allows you to see exactly how your capital will deplete over a 30-year horizon. It also integrates complex variables like Age Pension entitlements and Centrelink asset test strategies to ensure you aren't leaving money on the table. Our approach to retirement planning Sydney provides this bespoke roadmap, transforming a collection of assets into a coordinated, multi-decade income stream.
Stochastic Modelling: Planning for Real-World Uncertainty
Probabilities outweigh predictions. Instead of relying on a single "average return," stochastic modelling runs thousands of simulations to show a range of probable outcomes for your portfolio. This methodology acknowledges that the future is uncertain but manageable. By seeing the statistical likelihood of your money lasting until age 95 or 100, you can move from a place of anxiety to one of informed oversight. There is a fundamental difference between a "forecast," which is often a best-guess scenario, and a "strategic plan," which is a disciplined framework designed to succeed across a variety of market conditions. This research-driven clarity is what allows you to spend and enjoy your wealth today, knowing the long-term projections remain secure.
Managing the 'What-Ifs': Sequence of Returns and Inflation Protection
Timing is everything. The first five years of your retirement represent a "fragile zone" where your portfolio is most vulnerable to market volatility. This is known as Sequence of Returns Risk. If a significant market downturn occurs just as you begin to draw down your capital, the mathematical impact on your long-term sustainability can be devastating. Understanding how to retire with confidence requires a strategy that protects your capital during these critical early years, ensuring a poorly timed dip doesn't derail a 30-year plan.
Inflation remains the silent thief of retirement purchasing power in 2026. While your super balance might look substantial today, the rising cost of essential services and lifestyle choices can erode its real-world value over time. To combat this, we utilise a "bucket strategy" that segments your wealth into distinct time horizons. This structure provides short-term liquidity for your immediate needs while allowing your long-term growth assets the time they need to outpace inflation and compound effectively.
Wealth Preservation in a Volatile World
Logic dictates your asset allocation. Low-volatility assets play a vital role in securing your core lifestyle income, acting as a buffer when markets become unpredictable. A "set and forget" approach is a dangerous strategy for modern retirees who face longer life expectancies and shifting economic cycles. You can explore our detailed 12-month outlook on wealth preservation strategies to understand how we insulate portfolios from unnecessary risk without sacrificing the growth needed for longevity.
Stress-Testing Your Lifestyle
Structure provides resilience. A truly robust plan must account for rising healthcare or aged care costs that often increase in the later stages of retirement. We recommend maintaining an "emergency buffer" held in liquid assets, ensuring you aren't forced to sell growth investments at a loss during a market correction. We define the bucket strategy as a tool for emotional and financial stability that allows you to weather market storms without compromising your daily lifestyle. If you're concerned about how your current assets would perform under pressure, discussing your portfolio sustainability with a specialist can provide the clarity you need to move forward with certainty.
Taking the Helm: Navigating Your Retirement Journey in Sydney
Strategy demands execution. While technical modelling provides the map, the actual journey requires a partner who understands your specific context. Transitioning from being "Member #12345" in a generic retail fund to having a bespoke lifestyle strategy is the definitive step in learning how to retire with confidence. It moves the conversation from abstract balances to the tangible reality of your daily life in Sydney, ensuring your financial structure serves your personal goals rather than the other way around.
2026 is also the critical year to formalise your estate planning and legacy goals. With the general transfer balance cap now at $2.1 million, ensuring your wealth transitions to the next generation without unnecessary tax leakage or legal complexity is paramount. This process is about more than just a will; it's about ensuring your values are preserved alongside your capital. By integrating your estate goals into your broader retirement model, you can provide for your family while maintaining the lifestyle you've worked decades to achieve.
The Sutherland Shire Advantage
Local knowledge provides a distinct edge. Living in Sydney or the Sutherland Shire brings unique financial considerations that a generic national calculator simply cannot capture. From local property values to the specific costs of a coastal lifestyle, a "Steady Navigator" who understands this economic landscape provides an advantage that a call-centre advisor cannot match. True North Lifestyle simplifies the complex for local families, providing face-to-face clarity in our Miranda and Sydney CBD offices. We help you account for the nuances of the Sydney market, ensuring your projections are grounded in the real-world costs of your home suburb.
Your Retirement Checklist for 2026
Preparation precedes peace of mind. Before your first strategic consultation, gather your latest superannuation statements, investment records, and a clear list of any remaining liabilities. More importantly, define your "Non-Negotiables." What does your ideal Tuesday look like? Whether it's mornings at Cronulla beach or funding a grandchild's education, these values drive the modelling. Booking a discovery session allows us to align your capital with these aspirations, creating a structured path from uncertainty toward a well-defined future. This proactive approach ensures that when you finally step away from the workforce, you do so with a clear, visual roadmap of your financial longevity.
Your Roadmap to a Defined Future
Confidence is the result of a deliberate architecture. You've explored how transitioning from generic calculators to bespoke modelling reveals the true sustainability of your wealth. By addressing sequence of returns risk and identifying tax-minimisation opportunities, you've taken the first steps toward securing your lifestyle for the next thirty years. Discovering how to retire with confidence is a journey that begins with structural clarity and disciplined modelling.
At True North Lifestyle, we act as your steady navigator, providing the research-driven strategies needed to transform retirement anxiety into financial certainty. Our in-house Investment Committee focuses on wealth preservation, ensuring your portfolio is built to withstand market volatility while supporting your non-negotiable lifestyle goals. With local expertise in Miranda and the Sydney CBD, we specialise in tailoring these complex strategies for Sydney families.
It's time to move beyond the fog of uncertainty and step into a role of informed oversight. Book a Strategic Retirement Consultation with True North Lifestyle today to begin visualising your future with absolute clarity. Your best years are ahead of you.
Frequently Asked Questions
How much do I actually need to retire comfortably in Australia?
ASFA suggests a couple needs a lump sum of $730,000 or an annual income of $78,566 for a comfortable retirement in 2026. This standard assumes you own your home outright and enjoy relatively good health. However, these are generic benchmarks. Your personal "enough" number depends on your specific lifestyle aspirations and how you choose to structure your assets to generate sustainable, inflation-adjusted income over a thirty-year horizon.
What is the "re-contribution strategy" and how can it save my family tax?
This strategy involves withdrawing a portion of your super and contributing it back as a non-concessional amount. By doing this, you convert taxable components into tax-free ones. This is a vital part of learning how to retire with confidence because it significantly reduces the 15% plus Medicare levy tax that non-dependant beneficiaries, such as adult children, might otherwise pay on your remaining super balance after you pass away.
Can I still get the Age Pension if I own my home in Sydney?
Yes, your principal place of residence is generally exempt from the Centrelink assets test regardless of its market value. This is particularly relevant for Sydney residents where property prices are high. While the home is exempt, your other assets and income will still be assessed against current thresholds. For a couple, the maximum Age Pension rate from September 2026 is $1,866.00 per fortnight, provided you meet the means-test requirements.
What is sequence of returns risk and why should I care?
Sequence of returns risk is the danger that a market downturn occurs in the early stages of your retirement. When you draw down capital during a dip, you sell more units at lower prices, which can prematurely deplete your nest egg. Managing this risk is central to how to retire with confidence. We address this through bespoke modelling and "bucket strategies" that protect your short-term cash flow from market volatility.
How often should I review my retirement plan once I stop working?
You should review your strategy at least once a year or whenever a significant legislative change occurs. The 2026-27 financial year brings new contribution caps, such as the $32,500 concessional limit, and shifting pension rates that may require adjustments to your drawdown plan. Regular reviews ensure your portfolio remains aligned with your goals and that you continue to optimise your tax position as market conditions and your personal needs evolve.
Should I pay off my mortgage before I retire?
Paying off your mortgage is typically a priority because it significantly reduces your required retirement income. The ASFA comfortable standard assumes you own your home outright; without this, your annual spending needs would be much higher. Eliminating debt provides a psychological sense of security and simplifies your cash flow. However, the decision should be part of a broader modelling exercise that considers your available liquid capital and tax-effective contribution limits.
What is a sustainable withdrawal rate for my superannuation?
A sustainable withdrawal rate typically ranges between 4% and 5% of your total balance, but this is not a one-size-fits-all rule. Your specific rate depends on your asset allocation, life expectancy, and whether you intend to leave a legacy. Strategic modelling helps define a rate that balances your desire to enjoy your wealth today with the necessity of ensuring your capital lasts as long as you do across various market cycles.
How does inflation affect my retirement savings over 20 years?
Inflation is the silent thief that erodes the purchasing power of your savings. Over 20 years, even moderate inflation can nearly double the cost of living. If your portfolio doesn't include growth assets that outpace inflation, your fixed income will buy significantly less in the future. We use probability-based modelling to ensure your strategy accounts for rising costs in essential areas like healthcare, electricity, and local Sydney council rates.


