

An account-based pension is not an administrative checkbox. It is an active cash-flow defence system. For retirees and pre-retirees across Cronulla, Miranda, and the wider Shire, securing bespoke account-based pension advice Sutherland Shire residents rely on is often the clear dividing line between ongoing financial anxiety and genuine freedom. Shifting from accumulating wealth to actively spending it down feels counterintuitive, particularly when early market volatility threatens your hard-earned capital.
You shouldn't have to spend your post-work years worrying whether statutory drawdown percentages, shifting Centrelink deeming rules, or the $2.1 million Transfer Balance Cap will erode your lifestyle. Discover how tailored account-based pension advice in Sutherland Shire secures your capital, minimises tax, and delivers sustainable retirement cash flow. In this 2026 guide, we outline the exact portfolio structures and sequencing protections required to replace your salary with a predictable, automated monthly paycheque designed to endure for decades.
Key Takeaways
- Understand how meeting a full condition of release converts superannuation into a zero-tax retirement income stream under current 2026 statutory rules.
- Discover how tailored account-based pension advice Sutherland Shire retirees rely on builds defensive cash buffers to insulate your core capital from market downturns.
- Uncover the real risks of default industry fund pensions that automatically liquidate depreciated growth assets to meet mandatory monthly payments.
- Learn the essential criteria for selecting a trusted, fee-for-service adviser in the Shire who operates without institutional sales conflicts.
- See how bespoke cash-flow modelling replaces post-work uncertainty with a reliable, structured income stream tailored to your lifestyle goals.
What Is an Account-Based Pension and How Does It Function in 2026?
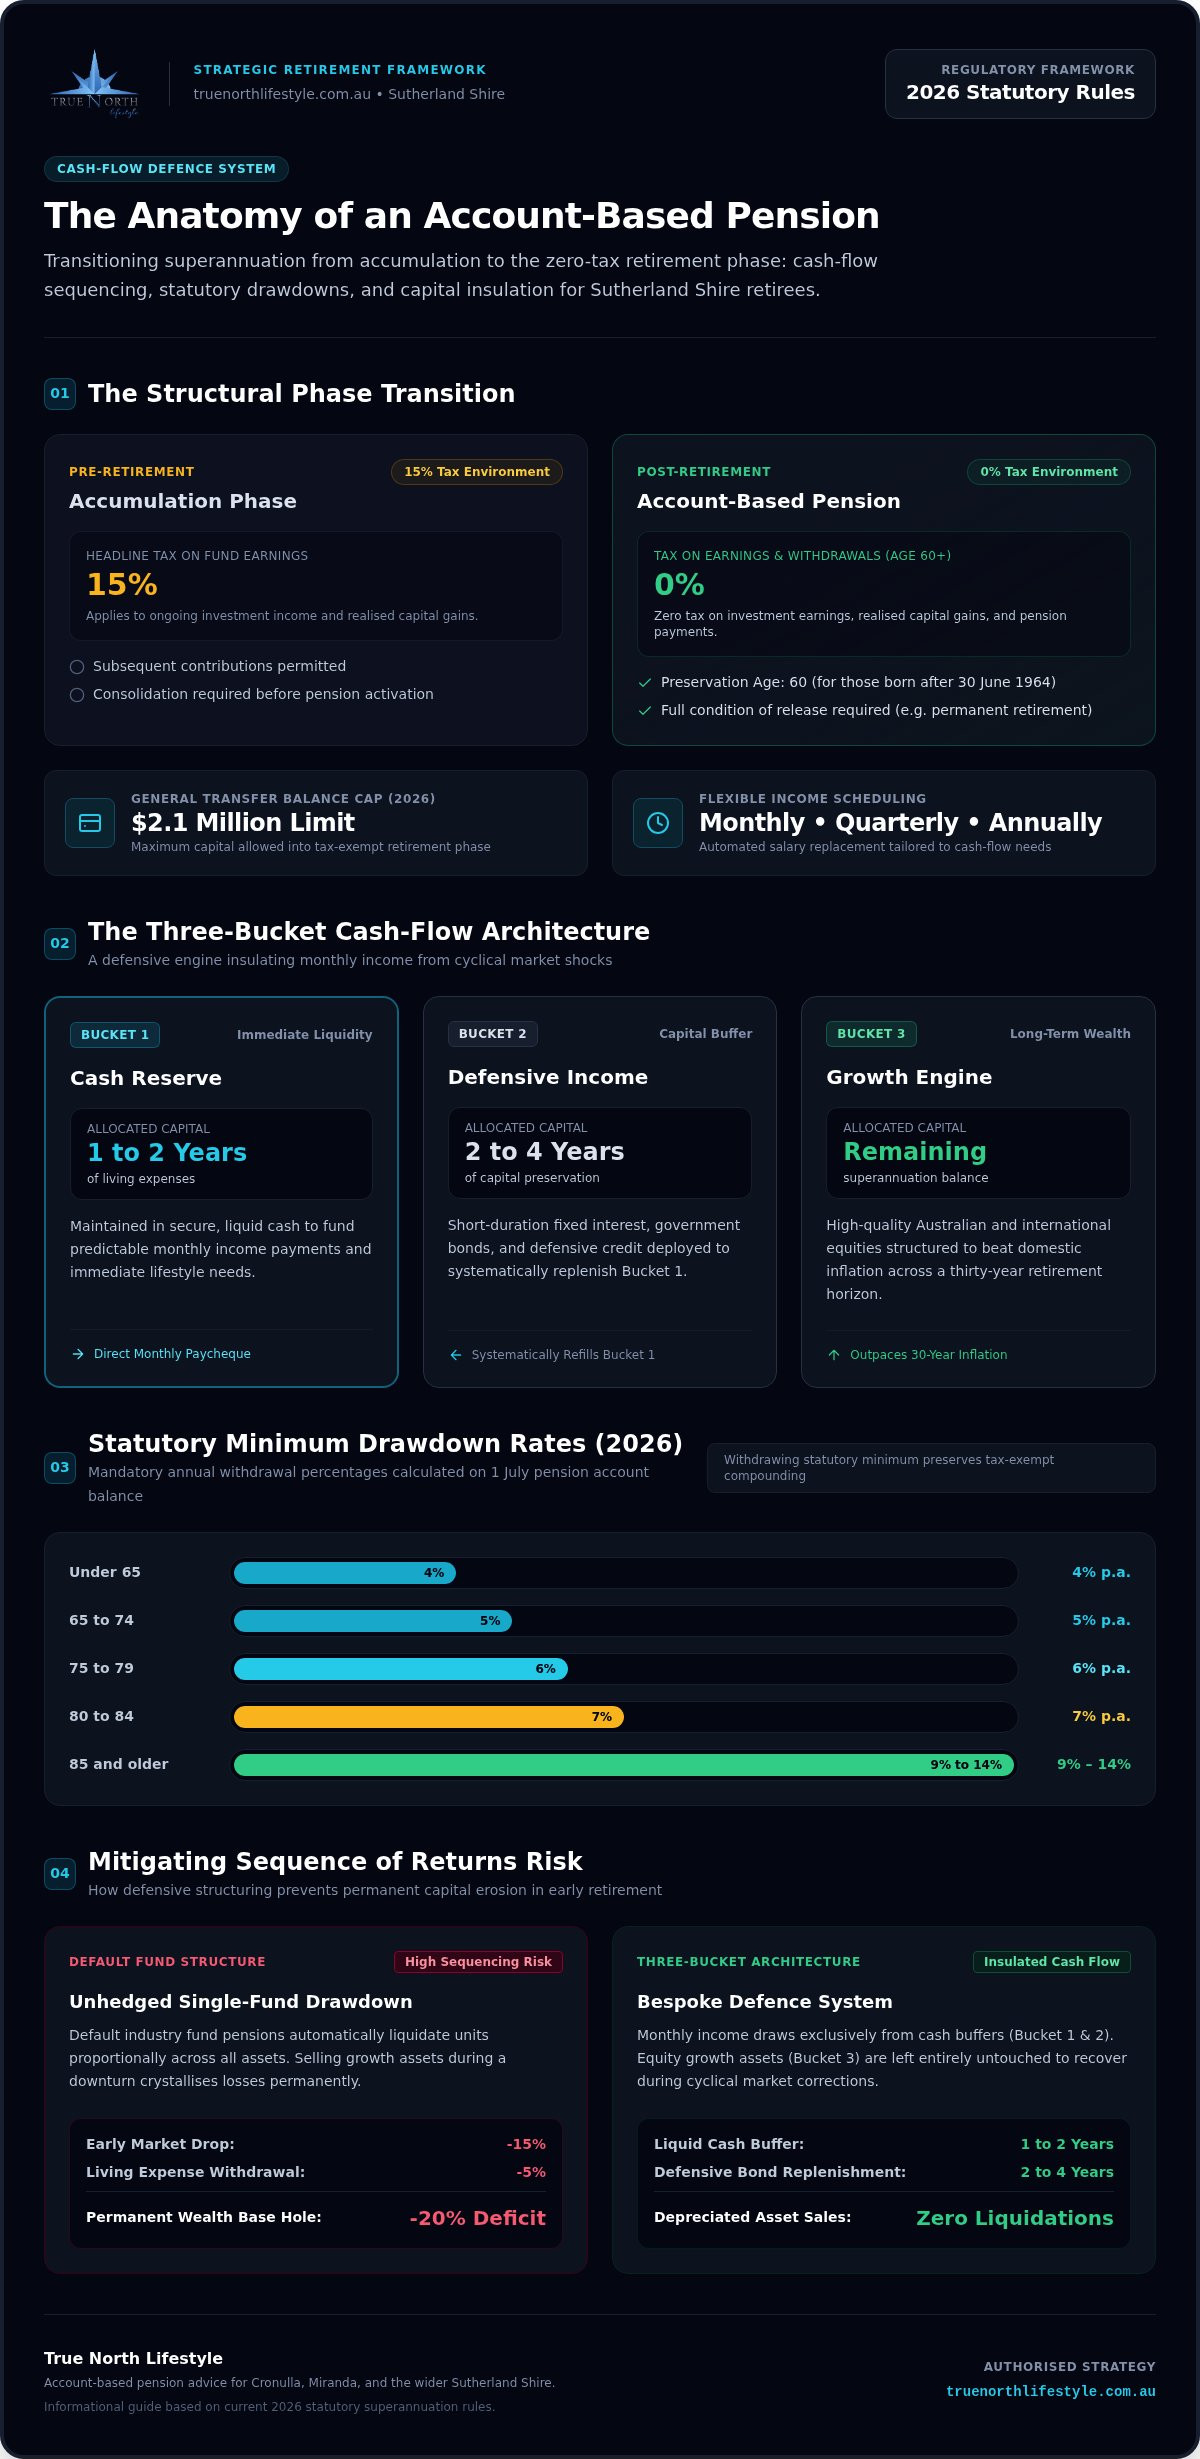
Control your capital. An account-based pension transforms accumulated superannuation savings into a flexible, tax-free income stream designed to replace your working salary. Established within the broad superannuation system in Australia, this vehicle becomes accessible once you reach preservation age (age 60 for anyone born after 30 June 1964) and satisfy a full condition of release, such as permanent retirement. Once commenced, the structural advantages are unmatched. All investment earnings and realised capital gains inside the pension account are taxed at 0%, while pension payments to individuals aged 60 and over are completely tax-free. Under current rules, individuals can transfer up to the general Transfer Balance Cap of $2.1 million into this tax-exempt retirement phase.
Converting Superannuation from Accumulation to Pension Phase
Timing is everything. Moving capital from the accumulation phase, where fund earnings face a 15% headline tax rate, requires deliberate administrative coordination. Retirees holding multiple accounts must consolidate balances beforehand, because superannuation law strictly prohibits adding subsequent contributions to an active pension account once it commences. As detailed in our guide to Superannuation Advice Sutherland Shire, aligning portfolio rollover dates with financial year cut-offs ensures you avoid unallocated tax liabilities and market out-of-pocket gaps. Engaging dedicated account-based pension advice Sutherland Shire specialists early prevents irreversible transfer mistakes.
Statutory Minimum Drawdowns: ATO Rules for 2026
Mandatory drawdowns apply annually. The Australian Taxation Office requires retirees to withdraw a minimum percentage of their account balance each fiscal year, calculated against their balance on 1 July:
- Under 65: 4%
- 65 to 74: 5%
- 75 to 79: 6%
- 80 to 84: 7%
- 85 and older: 9% to 14%
Restricting withdrawals to the statutory minimum leaves more capital inside the zero-tax environment to compound. Retirees can schedule these disbursements monthly, quarterly, or annually, establishing a predictable cash-flow rhythm that mirrors a dependable private salary.
Strategic Management: Managing Cash Flow, Tax and Sequencing Risk
Volatility demands structure. A poorly constructed pension portfolio forces retirees to sell productive assets when markets retreat, locking in permanent capital loss. Conversely, dynamic cash-flow modelling transforms your pension into a defensive engine that insulates day-to-day income from cyclical market shocks. As confirmed by Moneysmart guidance on account-based pensions, these structures provide the flexibility to dictate your regular drawings while keeping unspent capital invested. Integrating structured drawdown techniques with proactive Tax Planning for Retirement Australia ensures you maximise tax-free benefits without falling into common regulatory pitfalls.
The Three-Bucket Cash-Flow Architecture
Segment your capital. Rather than holding a single balanced fund where withdrawals shave off units evenly across all asset classes, a three-bucket architecture divides your portfolio strategically:
- Cash Reserve (Bucket 1): Holds one to two years of living expenses in secure, liquid cash to fund regular monthly income payments.
- Defensive Income (Bucket 2): Allocates two to four years of capital to short-duration fixed interest, government bonds, and defensive credit to replenish Bucket 1 systematically.
- Growth Engine (Bucket 3): Deploys remaining funds into high-quality Australian and international equities to beat domestic inflation over a thirty-year retirement horizon.
Mitigating Sequence of Returns Risk for New Retirees
Timing can derail wealth. Sequence of returns risk refers to the catastrophic impact of experiencing severe market downturns in the initial five years of retirement while actively withdrawing capital. When an unhedged pension account drops by 15% and you withdraw 5% for living expenses, you cement a 20% aggregate hole in your wealth base. That capital cannot easily recover. Disciplined Retirement Planning Sydney modelling demonstrates that drawing exclusively from liquid cash reserves during downturns gives your underlying equity investments the vital multi-year breathing room required to rebound intact.
Centrelink Deeming and the Age Pension Assets Test
Balance every entitlement. Inside an account-based pension, your balance counts toward Centrelink's assets test and is subject to statutory deeming rates under the income test. Following recent adjustments, Services Australia calculates deemed returns at 1.75% on the lower threshold ($66,800 for singles, $110,600 combined for couples) and 3.75% on financial assets beyond those limits. In the Sutherland Shire, where primary residence values often mean retirees exceed the assets test taper rate before failing the income test, bespoke account-based pension advice Sutherland Shire specialists deliver can strategically position investments, including spousal superannuation splits, to retain valuable concession card benefits. Exploring a tailored arrangement with True North Lifestyle provides the strategic clarity needed to coordinate your private capital alongside public entitlements.
Default Super Fund Pensions vs Bespoke Account-Based Advice
Default settings fail retirees. Large commercial and industry superannuation funds serve the accumulation phase well, but their pooled retirement products rely on blunt, automated mechanisms. When an industry fund pays your monthly income stream, its internal systems typically sell down units proportionally across all underlying holdings, regardless of whether equity markets are soaring or collapsing. In contrast, specialised account-based pension advice Sutherland Shire retirees seek provides tailored asset control. Integrating principles of Bespoke Investment Advice Sydney gives individuals targeted authority over precisely which assets generate their living cash flow.
Investment Flexibility and Dynamic Asset Allocation
Rigid pools hurt performance. Most default pension options group hundreds of thousands of members into broad balanced or conservative pools. These static products cannot adapt when the Reserve Bank of Australia shifts interest rates or when equity valuations compress. A bespoke mandate, managed with institutional-grade oversight, offers distinct operational advantages:
- Granular Asset Selection: Liquidate high-performing direct shares or cash accounts for regular drawings rather than selling depressed defensive securities.
- Dynamic Yield Harvesting: Capture direct dividends and franking credits to fund distributions without depleting core capital units.
- Tailored Volatility Management: Adjust equity duration and debt instruments according to personal risk capacity rather than a generic age bracket.
Estate Planning and Anti-Detriment Tax Minimisation
Protect your family. Beyond ongoing portfolio agility, default pension platforms routinely fall short in intergenerational wealth preservation. When pension capital passes to financially independent adult children, the taxable component of the death benefit faces a 15% tax plus the 2% Medicare levy. Under standard ATO minimum drawdown rates and income stream rules, an unmanaged account can leave substantial tax liabilities behind. Working with an adviser allows pre-retirees to execute re-contribution strategies, drawing lump sums under age limits and re-injecting them as non-concessional capital within the $130,000 annual allowance. This process converts taxable components to tax-free funds while anchoring binding non-lapsing death nominations to bypass protracted probate challenges.
Selecting the Right Pension Adviser in Sutherland Shire: A Buyer's Framework
Demand complete transparency. Decumulation is fundamentally distinct from wealth accumulation. Managing a permanent income stream requires deep modelling of longevity risks, tax-exempt earnings, and legislative thresholds. When evaluating professional account-based pension advice Sutherland Shire retirees must look beyond polished presentations and scrutinise adviser independence, professional credentials, and ongoing fiduciary care.
Licensing, Experience and Fiduciary Alignment
Verify before committing. Start your due diligence on the ASIC Financial Advisers Register to confirm your adviser holds current qualifications and operates with an unblemished record. Prioritise a transparent, fee-for-service model. If an advisory firm receives vertical product incentives or platform shelf-space fees, their recommendations may tilt toward institutional profit rather than your family's longevity. Ask these vital questions during your initial meeting:
- Are you tied to any proprietary superannuation or pension investment products?
- How specifically do you model portfolio cash flow across severe, multi-year market drawdowns?
- What exact ongoing strategy reviews are covered within your agreed professional fee?
Local Proximity and Long-Term Partnership in Miranda
Retirement is intensely personal. While remote digital advisers offer convenience, sitting down in a Miranda boardroom provides the depth needed for multi-decade financial planning. Local advisers understand Sutherland Shire living costs, from council rates and insurance costs to Cronulla lifestyle spending. They also maintain the structured discipline required to run annual strategy reviews, recalibrating mandatory minimum drawdown rates against prevailing inflation.
Crucially, an enduring local partnership welcomes your spouse and adult beneficiaries into the conversation. Coordinating intergenerational goals early prevents costly administrative oversights down the track. To establish a structured income plan built around your exact life goals, connect with the True North Lifestyle advisory team in Miranda today.
Partnering with True North Lifestyle for Sustainable Retirement Income
Navigate with conviction. Transitioning from accumulation to active drawdown presents psychological and financial friction that generic online calculators cannot solve. True North Lifestyle acts as your steady navigator, translating complex regulatory frameworks into a coherent, stress-tested income roadmap. Operating locally from Miranda, our fee-for-service practice delivers tailored account-based pension advice Sutherland Shire families rely on to protect their capital, eliminate tax inefficiencies, and maintain total lifestyle autonomy.
Institutional oversight anchors our approach. Rather than handing your future to a third-party retail platform, our in-house Investment Committee partners with Resonant Asset Management to craft low-volatility, income-generating portfolios. This dedicated collaboration delivers institutional-grade portfolio oversight, actively selecting quality defensive holdings and yield-bearing equities to insulate your income from domestic market turbulence.
The True North Retirement Clarity Roadmap
Structured clarity drives our three-stage implementation methodology:
- Phase 1: Lifestyle Cash-Flow Mapping: We conduct a comprehensive discovery analysis detailing your fixed household overheads and discretionary travel goals across the Sutherland Shire.
- Phase 2: Stochastic Durability Stress-Testing: We run mathematical modelling against historical recessions, testing portfolio survival under prolonged inflation and market drawdowns to ensure your capital survives thirty years.
- Phase 3: Strategic Portfolio Commencement: We orchestrate superannuation fund consolidation, establish non-concessional re-contribution pathways, and formally trigger the tax-exempt pension phase before executing your automated monthly paycheque.
Begin Your Retirement Transition in Miranda
Gain absolute peace of mind. True North Lifestyle invites Shire pre-retirees to schedule a confidential consultation at our Miranda office. Bring your latest superannuation statements, discuss your target exit dates, and receive an objective appraisal of your structural readiness. Take control of your financial longevity by connecting with True North Lifestyle to build an enduring income stream today.
Take Command of Your Retirement Cash Flow
Retirement should be defined by freedom, not balance sheet anxiety. Moving beyond generic default superannuation funds gives you complete authority over how your income is funded and preserved. When you implement structured cash buffers, eliminate sequencing risk, and align withdrawals with current statutory caps, you insulate your hard-earned wealth against economic volatility.
Achieving this level of strategic clarity requires experienced, unconflicted guidance. True North Lifestyle delivers the tailored account-based pension advice Sutherland Shire retirees trust to structure lasting income streams. Operating locally from Miranda 2228, our practice provides transparent, fee-for-service advice designed around your family's personal goals. Through our research-led partnership with Resonant Asset Management, we deliver institutional-grade portfolio governance that keeps your investments working quietly in the background. Your next chapter deserves structure, confidence, and absolute certainty. Book your retirement clarity consultation with True North Lifestyle in Miranda and step forward into retirement with complete peace of mind.
Frequently Asked Questions
Can I access my superannuation tax-free through an account-based pension before age 60 in Australia?
No, withdrawals before age 60 generally do not qualify for complete tax-free status. While individuals meeting a specific condition of release prior to age 60 can access preserved funds via an income stream, payments typically contain taxable components subject to your marginal tax rate minus a 15% tax offset. Once you reach your 60th birthday, all regular pension payments and lump-sum commutations become completely exempt from Australian income tax.
What happens to my account-based pension if financial markets suffer a significant downturn?
Your underlying portfolio balance fluctuates with broader market movements, but your regular cash flow doesn't have to stop. By engaging tailored account-based pension advice Sutherland Shire specialists design, you establish dedicated cash and fixed-interest buffers. This dynamic architecture ensures your scheduled pension payments draw from safe cash reserves rather than liquidating depressed equity units during cyclical corrections, allowing your core capital time to recover.
How much is the minimum annual drawdown rate on an account-based pension in 2026?
The statutory minimum drawdown rate depends entirely on your age on 1 July each fiscal year. For retirees under 65, the mandatory minimum is 4%. It increases to 5% between ages 65 and 74, 6% from 75 to 79, and 7% between 80 and 84. Above age 85, statutory rates scale from 9% up to 14% for retirees aged 95 or older.
Is my account-based pension balance counted toward Centrelink Age Pension assessment?
Yes, Services Australia evaluates your account-based pension under both the assets test and the income test. The total account value is assessed as a financial asset. For the income test, Centrelink applies standard deeming rates rather than assessing your actual pension drawings. Shire retirees often find their home equity and pension balances require careful structuring to prevent taper rates from cancelling valuable concession card benefits.
Can I stop or adjust my regular account-based pension income payments throughout the year?
Yes, you have the flexibility to alter your payment amounts, change draw frequencies, or request ad-hoc lump sums at any stage. You can receive payments monthly, quarterly, semi-annually, or annually to match your personal cash needs. However, your total drawings across the financial year must satisfy the ATO's statutory minimum drawdown requirement before 30 June to maintain the fund's 0% tax-exempt earnings status.
What happens to the remaining balance of my account-based pension when I die?
Any remaining capital is distributed to your chosen beneficiaries or your legal estate according to your binding death nomination. If directed to a spouse or financial dependant, the funds can continue as a tax-free reversionary pension. When transferred to adult children, the taxable component faces a 17% death benefits tax, which is why local families in Miranda utilise pre-commencement re-contribution strategies to protect wealth.
How does the Transfer Balance Cap impact how much money I can move into a pension?
The Transfer Balance Cap sets a lifetime limit on the total superannuation capital you can transfer into the tax-free retirement phase. As of 1 July 2026, the general cap sits at $2.1 million. Seeking proactive account-based pension advice Sutherland Shire retirees recommend helps navigate these limits, ensuring excess superannuation remains in the low-tax accumulation phase without triggering punitive Australian Taxation Office excess transfer balance tax charges.


