

Is your "magic number" actually a mirage? For many Australians, the quest for financial peace begins with a simple search for a retirement savings calculator Australia. You enter your current super balance, your age, and perhaps a desired annual income, hoping for a green light that says you're on track. Yet, as the cost of living in Sydney continues to climb and superannuation legislation grows increasingly complex, these basic tools often leave you with more questions than certainty. You aren't just looking for a generic estimate. You're seeking a way to protect your lifestyle against inflation and the very real risk of outliving your capital.
We understand that a comfortable retirement isn't found in a default setting. This guide will show you how to move beyond superficial projections to build a bespoke financial strategy tailored for the 2026 landscape. We'll explore how to stress-test your assumptions against tax implications and longevity risks, providing you with a clear, actionable pathway to validate your DIY calculations with professional precision. By the end of this article, you'll have the framework to transform a digital estimate into a robust, evidence-based plan for your future.
Key Takeaways
- A retirement savings calculator Australia provides an essential baseline for your superannuation projections, helping to replace financial anxiety with clear, data-driven insights.
- Accuracy depends on more than just your current balance; you must account for variables like insurance premiums, management fees, and real-world investment returns to avoid a future shortfall.
- Standard digital tools often ignore critical factors like sequence of returns risk and tax-minimisation strategies, which are vital for extending the longevity of your capital.
- Compare your results against the 2026 ASFA Comfortable Standard to identify any potential gaps in your strategy and understand what your bespoke retirement number really looks like.
- Professional modelling serves as the ultimate stress test for your DIY calculations, ensuring your portfolio is robust enough to withstand market volatility and shifting legislation.
The Role of a Retirement Savings Calculator in Australia
A retirement savings calculator Australia acts as a digital compass. It takes your current financial trajectory and projects where you might land in two or three decades. For many, this is the first step toward financial clarity. It replaces the heavy fog of uncertainty with a tangible data point. While these tools are excellent for establishing a baseline, they function on averages. They cannot account for your unique risk appetite or the sophisticated tax structures that often define a successful transition to post-work life.
The superannuation system in Australia forms the bedrock of these calculations, yet the interplay between mandatory contributions, personal savings, and Age Pension eligibility is often too nuanced for a basic algorithm. A calculator gives you a "what if" scenario; it doesn't provide a strategy. It serves as a stabilizing starting point that allows you to see the gap between your current super balance and your future lifestyle aspirations.
Why 2026 is a Critical Year for Retirement Planning
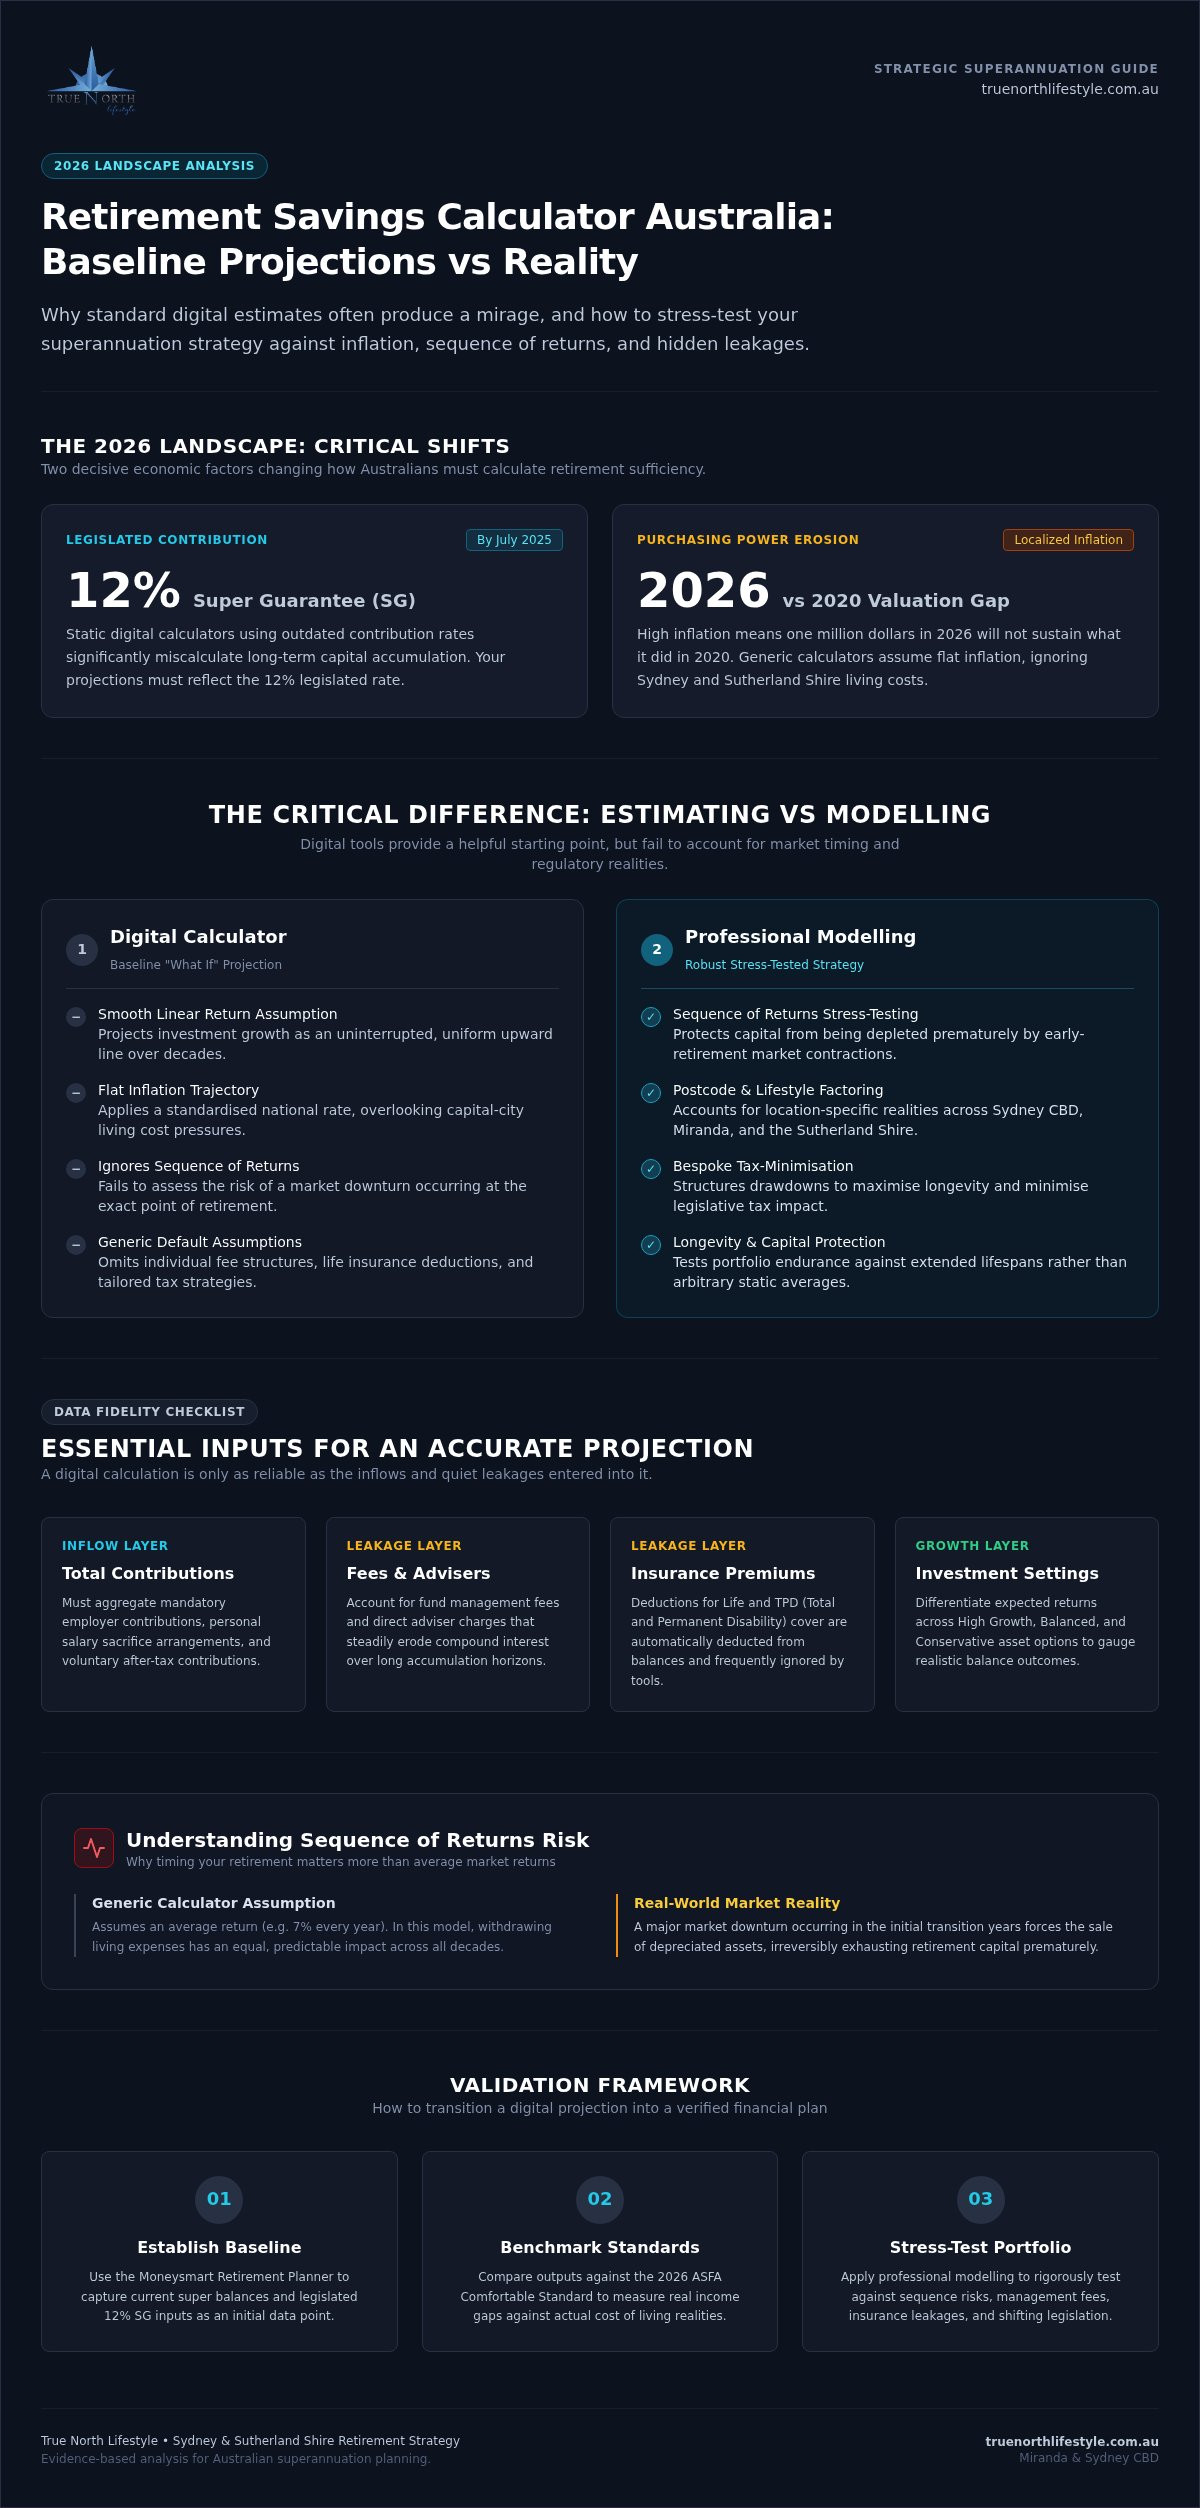
Planning for 2026 requires a shift in perspective. By July 2025, the Superannuation Guarantee (SG) rate is legislated to reach 12%. This increase is a significant driver for long-term super growth, yet many static calculators haven't updated their logic to reflect these higher contribution levels. If your projections are based on outdated rates, your "magic number" might be fundamentally flawed.
Purchasing power is the other side of the coin. High inflation trends, particularly in Sydney and the Sutherland Shire, mean that a million dollars in 2026 won't buy what it did in 2020. A basic calculator often assumes a flat inflation rate, failing to account for the localized cost of living pressures that impact Sydney retirees. You need to know if your projected balance can actually sustain a comfortable lifestyle in your specific postcode.
The Difference Between Estimating and Modelling
Online tools offer a one-size-fits-all estimate. They assume your investment returns will be a smooth, upward line. Real life is rarely that predictable. Professional retirement modelling goes deeper by accounting for "sequence of returns" risk. This is the danger that a market downturn occurs just as you stop working, which can derail a generic calculator's average return estimate and deplete your capital faster than expected.
Bespoke modelling provides the stress-testing that digital tools lack. For residents in Miranda or the Sydney CBD, professional oversight ensures that your strategy accounts for bespoke tax structures and portfolio sustainability. It moves you from a position of hope to a position of quiet certainty, backed by rigorous testing and a clear understanding of the road ahead.
How to Use a Retirement Calculator: Essential Inputs for Accuracy
Precision matters. A digital tool is only as reliable as the data it processes. Using a retirement savings calculator Australia effectively requires a comprehensive gathering of your financial facts, moving beyond a simple glance at your latest super statement. To move from a rough guess to a functional projection, you must account for every inflow and outflow that defines your current wealth trajectory.
Start by identifying your total annual contributions. This includes your employer payments, any personal salary sacrifice arrangements, and voluntary after-tax contributions. Don't overlook the "hidden" leakages that can quietly erode your capital over decades. Management fees, advisor costs, and insurance premiums for life or TPD cover are often deducted automatically, yet many basic calculators ignore these variables. Accounting for these costs now ensures your 2026 projections remain grounded in reality. For a reliable baseline, the Moneysmart Retirement Planner offers a robust starting point for these initial entries.
Step 1: Assessing Your Current Superannuation Position
Your journey begins with a clear-eyed look at your current super balance and investment settings. It's vital to understand whether you're currently in a "High Growth," "Balanced," or "Conservative" option, as the assumed investment return will drastically change your final outcome. If you're unsure how your current fund compares to market benchmarks, seeking superannuation advice Sutherland Shire can help align your risk profile with your long-term goals. The Superannuation Guarantee (SG) is the compulsory percentage of your ordinary time earnings that your employer must pay into your super fund, and with this rate legislated to reach 12% by 2026, it's a critical component of your future modelling.
Step 2: Defining Your Retirement Lifestyle
What does "comfortable" look like to you? The ASFA Retirement Standard provides a useful benchmark for Australian retirees, but it often requires adjustment for those living in high-cost areas like Sydney. You must factor in localized expenses such as property maintenance, higher healthcare costs, and your specific travel aspirations. If you plan on a "phased retirement" by transitioning to part-time work, your calculator inputs should reflect that reduced income and continued, albeit smaller, contributions. While these tools provide a helpful snapshot, bespoke portfolio construction ensures that your non-super assets, like investment properties or private shares, are fully integrated into your wealth preservation plan.
Beyond the Numbers: What Most Calculators Miss
Numbers provide comfort. However, a retirement savings calculator Australia often operates within a vacuum of perfect conditions. It assumes that market growth is a steady, linear climb and that your personal circumstances will remain static for three decades. In reality, the "average" return used by digital tools can be deeply misleading. If a significant market downturn occurs in the years immediately preceding or following your retirement, your capital may never fully recover, even if the long-term average remains high. This "sequence of returns" risk is a primary reason why a generic estimate is a starting point, not a final strategy.
Strategic tax planning for retirement Australia is another critical element that basic algorithms frequently overlook. By optimising how you draw down your different pools of capital, you can significantly extend the life of your savings. Without bespoke modelling, you might inadvertently pay thousands in unnecessary tax, effectively shortening your financial runway. While the Moneysmart retirement planner offers a helpful glimpse into your future, it cannot replace the nuanced construction of a tax-efficient income stream.
Longevity risk and inflation protection require a shift in perspective. A $1 million balance in 2026 sounds substantial, yet its purchasing power in 2046 will be vastly different. You aren't just planning for a 15-year holiday; you're likely planning for a 30-year lifestyle. Your projections must account for "real" returns, which are your investment gains minus the eroding effect of inflation, to ensure your standard of living doesn't diminish as you age.
Centrelink Asset Tests and Gifting Rules
Calculators rarely master the complexity of the Age Pension. The asset test creates a "taper zone" where every extra dollar of private wealth can reduce your pension entitlements, often leading to a lower total income than those with fewer assets. In New South Wales, the distinction between being a homeowner or a non-homeowner adds another layer of calculation that generic tools miss. Professional Centrelink structuring can help you manage these thresholds, ensuring your gifting and asset levels are optimised to improve your overall cash flow throughout your later years.
The Impact of Fees and Inflation on Long-term Capital
Fees are the silent killers of compounding growth. A 1% difference in annual management fees might seem negligible today, but over a twenty-year period, it can result in a six-figure difference in your final balance. You must ensure your modelling uses inflation-adjusted figures to see what your money will actually buy in the future. For Sydney retirees in 2026, wealth preservation is the absolute priority to maintain lifestyle stability in a high-cost environment.
Interpreting Your Results: Is Your Super on Track?
Seeing the final number on a retirement savings calculator Australia can trigger a mix of relief and apprehension. This figure is merely a destination on a map; its value depends entirely on the lifestyle it is intended to fund. To understand if your super is truly "on track," you must measure it against objective benchmarks while acknowledging the specific costs associated with your desired standard of living. A raw number without context is just an estimate. True confidence comes from knowing that your projected balance can withstand the realities of 2026 and beyond.
The ASFA Standard vs. Your Reality
The Association of Superannuation Funds of Australia (ASFA) provides a "Comfortable Standard" which many use as a baseline. For the current period, these figures suggest a couple needs approximately $72,000 per year, while a single retiree requires roughly $51,000. While helpful, these national averages often fall short for residents in the Sutherland Shire or Sydney's coastal suburbs. Higher local rates, insurance costs, and the desire for premium healthcare often necessitate a bespoke standard that sits significantly above the national benchmark. You should view these figures as a minimum floor rather than a ceiling for your aspirations.
Strategies to Close the Retirement Gap
Discovering a projected shortfall is not a signal to settle for less. It's an invitation to refine your strategy. Catch-up concessional contributions allow you to utilise unused caps from previous years, while the downsizer contribution scheme offers a way to inject up to $300,000 per person into super from the sale of a primary residence. If you're over 60, a Transition to Retirement (TTR) strategy can help you boost your super balance while you continue to work, often with meaningful tax advantages that a basic calculator cannot easily model.
Efficiency is just as important as contribution volume. Reviewing your fund for unnecessary consolidation or excessive fees can reclaim thousands in lost growth over a decade. You must also evaluate your projected withdrawal rate; taking out 5% or 6% annually might seem safe in a digital tool, but it could be reckless during a period of high inflation or market volatility. When the gap feels too wide to bridge alone, seeking bespoke investment advice Sydney can help you optimise your risk-adjusted returns and ensure your capital lasts as long as you do. A digital tool identifies the problem, but a structured plan solves it. To move beyond estimates and secure your financial future, professional retirement modelling can provide the certainty you need.
Turning Projections into Reality with Professional Modelling
Data is a beginning. While a retirement savings calculator Australia provides a necessary baseline, it remains a static snapshot of a dynamic world. A digital tool can tell you where you might land if everything goes perfectly, but it cannot prepare you for the inevitable fluctuations of the global economy or shifts in Australian legislation. To move from a hopeful estimate to a resilient reality, you need to transition from basic calculation to sophisticated modelling. This process doesn't just predict a number; it defines a lifestyle that's protected against the unknown.
Professional stress testing is the vital bridge between a DIY guess and a secure future. We push your portfolio through various "what-if" scenarios, such as a prolonged market downturn or a sudden spike in the cost of living. This rigorous approach ensures your capital isn't just sufficient on paper, but robust enough to withstand real-world volatility. By identifying potential vulnerabilities before they become crises, we help you build a wealth preservation strategy that prioritises stability and long-term peace of mind.
The True North Approach to Retirement Clarity
Clarity requires a holistic view. Our bespoke modelling process integrates every facet of your financial life, from superannuation and private investments to complex tax structures. We don't view retirement in isolation. We incorporate estate planning and wealth transfer strategies to ensure your legacy is protected for the next generation. This comprehensive oversight transforms your financial plan from a spreadsheet into a living strategy. Having a "Steady Navigator" in your corner means you can step into retirement with quiet certainty, knowing the heavy lifting and rigorous testing have already been done.
Next Steps for Sydney Residents
Action creates confidence. For those living in the Sutherland Shire or working in the Sydney CBD, we offer face-to-face strategy sessions at our Miranda and city offices. These consultations are designed to move you beyond the limitations of online tools. When you join us, bring your latest super statements, investment records, and a clear vision of your ideal lifestyle. We'll use this data to stress-test your current trajectory and refine your path toward a bespoke financial future. Ready to move beyond the calculator? Book your retirement modelling session with True North Lifestyle today and take the first step toward a managed, secure legacy.
Secure Your Financial Legacy Beyond the Digital Estimate
A digital tool offers a helpful baseline, yet your future deserves more than a generic projection. While a retirement savings calculator Australia identifies a possible destination, it cannot account for the intricate legislative shifts or localised cost pressures facing Sydney residents in 2026. True financial peace of mind comes from moving beyond these surface-level estimates toward a strategy that is rigorously stress-tested against market volatility and inflation.
At True North Lifestyle, we specialise in tax-minimisation and wealth preservation strategies that basic algorithms simply cannot replicate. Our local expertise in Miranda and the Sutherland Shire ensures that your plan reflects your specific lifestyle goals and the unique economic environment of New South Wales. By integrating professional modelling with bespoke portfolio construction, we help you replace uncertainty with a structured, resilient path forward.
Secure your financial future with bespoke retirement modelling from True North Lifestyle. You have worked hard to build your wealth; now, let us provide the steady navigation needed to protect it for decades to come.
Frequently Asked Questions
How accurate are retirement savings calculators for Australians?
A retirement savings calculator Australia provides a helpful baseline, but its accuracy is limited by its reliance on linear averages. These tools often assume steady investment returns and flat inflation rates, which rarely reflect the real-world volatility of the Sydney market. While they offer a useful starting point for your journey, they cannot replace the precision of bespoke modelling that accounts for your specific risk tolerance and shifting superannuation legislation.
Do retirement calculators account for the Age Pension?
Many basic online tools fail to integrate the complexities of the Age Pension, such as the taper rate in the asset and income tests. At True North Lifestyle, we move beyond generic estimates by providing expert Centrelink structuring. This ensures your private savings and superannuation are organised to maximise your entitlements, providing a clearer picture of your total cash flow for a lifestyle in Miranda or the Sydney CBD.
What is a "comfortable" retirement balance in Australia for 2026?
While the ASFA "Comfortable" standard provides a national benchmark of approximately $72,000 per year for couples, Sydney residents often find this figure inadequate. The high cost of living in the Sutherland Shire means your "comfortable" number is likely higher. We recommend using professional modelling to define a bespoke standard that accounts for your specific travel, healthcare, and property maintenance aspirations in a post-2026 economic environment.
Can a calculator help me with tax minimisation in retirement?
Standard calculators are typically "tax-blind" and assume a simplified environment that doesn't reflect your actual liabilities. Real-world tax-minimisation requires a strategic review of your contribution types and drawdown sequences. Our advisers in Miranda specialise in constructing portfolios that reduce your tax burden, effectively extending the longevity of your capital in a way that a digital tool simply cannot replicate through a basic algorithm.
Should I include my family home in my retirement savings calculation?
Your family home is generally excluded from the Age Pension asset test, but it remains a critical component of your broader wealth preservation strategy. While you shouldn't rely on it for direct retirement income, the downsizer contribution scheme allows you to inject significant capital into super after a sale. We help you model how your property assets in Sydney influence your overall liquidity and estate planning goals.
How does the 2026 Superannuation Guarantee rate affect my projections?
The Superannuation Guarantee (SG) rate is legislated to reach 12% by July 2025, which will significantly bolster the long-term projections for many Australians. This increase provides a meaningful boost to your final balance, yet it must be balanced against the rising cost of living. Accurate modelling ensures your 2026 projections reflect these higher contribution levels while accounting for the eroding effect of inflation on your future purchasing power.
What is the difference between a simple calculator and professional cash flow modelling?
A simple calculator offers a static snapshot based on current data, whereas professional cash flow modelling provides a dynamic stress test of your entire financial ecosystem. Modelling accounts for sequence of returns risk, complex tax structures, and estate planning strategies. This comprehensive approach, delivered at our Sydney and Miranda offices, replaces the uncertainty of a DIY estimate with the quiet certainty of a professionally managed, bespoke financial legacy.
How often should I re-run my retirement savings calculations?
You should review your projections at least once a year or whenever there is a significant change in your personal circumstances or government policy. With the legislative shifts expected by 2026, regular reviews are essential to keep your strategy aligned with your goals. Frequent recalibration allows you to adjust your "catch-up" contributions or investment risk profile, ensuring you remain on a stable path toward your desired retirement outcome.


