

With Miranda's median house price sitting near $2.05 million, even high-earning Sutherland Shire households are feeling the compounding friction of elevated interest rates and escalating living expenses. Balancing immediate monthly commitments with future security often feels like an uncomfortable compromise. You likely know the tension well, funding your children's present milestones while quietly wondering if your long-term wealth trajectory is drifting off course. Engaging bespoke financial planning for families Miranda residents can rely on transforms that persistent uncertainty into structured, lasting confidence.
You shouldn't have to sacrifice tomorrow's freedom to manage today's realities. In this guide, discover how Sutherland Shire families can synchronise cash flow, optimise superannuation, and protect generational wealth with bespoke financial planning. We explore the strategic frameworks required to coordinate family tax efficiency, insulate your household against unexpected life disruptions, and construct an enduring legacy that securely carries your children forward.
Key Takeaways
- Neutralise local cost-of-living pressures by synchronising household cash flows against substantial mortgage commitments and long-term education funding.
- Discover how tailored financial planning for families Miranda households rely on coordinates superannuation optimisation, tax-minimisation strategies, and risk mitigation into one cohesive framework.
- Safeguard generational wealth through structured estate planning strategies designed to protect your children's future inheritance from taxation and relationship liabilities.
- Implement a methodical five-step roadmap powered by multi-decade scenario modelling to keep family wealth resilient across changing economic cycles.
- Achieve sustained peace of mind through institutional-grade portfolio construction and disciplined, research-backed investment oversight.
Navigating Family Wealth in Miranda: Pressures Facing Sutherland Shire Households
High earnings don't guarantee financial simplicity. Across the Sutherland Shire, successful dual-income households routinely generate substantial revenue, yet they find their discretionary surplus eroded by escalating living expenses. Meeting high recurring commitments often obscures a vital reality: strong income alone does not equal long-term balance sheet stability. Without integrated oversight, family capital can fragment across disconnected accounts, leaving substantial superannuation opportunities and structural tax efficiencies uncaptured.
Calm replaces anxiety when ad-hoc financial choices become an intentional roadmap. Engaging disciplined financial planning for families Miranda households trust allows parents to step back from tactical firefighting. Rather than reacting to monthly outflows, you establish an orderly strategy that synchronises immediate domestic priorities with sustained, intergenerational growth.
The Reality of Modern Family Finances in the Shire
Miranda property demands significant balance sheet commitment. With local median house values hovering around $2.05 million, servicing substantial debt absorbs significant cash flow, particularly in an environment of persistent interest rates. Layered over these housing requirements are the compounding costs of independent schooling across the Shire, stretching from primary tuition through to university living support. Leaving surplus cash idle in standard accounts quietly erodes purchasing power against lifestyle inflation, ensuring that hard-earned income works far less effectively than it should.
Moving Beyond Reactive Cash Management
Structure creates freedom. Basic budgeting merely tracks historical outflows, whereas strategic wealth management methodically directs future capital toward targeted outcomes. Coordinating these resources early prevents the steep compounding penalties of delayed planning. A disciplined framework delivers three immediate shifts:
- Targeted debt amortisation: Offsets non-deductible liabilities while preserving liquidity buffers for family contingencies.
- Tax-effective capital deployment: Directs cash surpluses into diversified, high-conviction investment structures rather than low-yield deposits.
- Strategic superannuation maximisation: Utilises available concessional caps to lower current assessable income while building long-term reserves.
Through bespoke financial planning for families Miranda professionals can finally move past reactionary measures. You convert operational income into resilient, long-term family security.
Core Pillars of Family Financial Planning: A Strategic Framework
Isolated financial decisions invite unintended tax leakage and disjointed asset growth. True financial resilience emerges when every structural mechanism, from superannuation balances to risk protection, operates in deliberate alignment. By adopting comprehensive financial planning for families Miranda parents can rest assured that day-to-day liquidity actively reinforces their long-term legacy.
Superannuation Optimisation and Tax Minimisation
Superannuation remains Australia's most tax-effective wealth accumulator, yet many dual-earner couples underutilise its potential. Structuring annual concessional contributions up to the $32,500 cap alongside non-concessional thresholds ($130,000) substantially diminishes personal assessable income. Meanwhile, strategic spousal contributions equalise balances ahead of the $2.1 million transfer balance cap. Aligning these contributions with established tax planning for retirement Australia frameworks ensures family capital compounds under sheltered rates without starving household operations.
Bespoke Portfolio Construction and Risk Modelling
Sustaining multi-generational security requires disciplined investment management that looks beyond market momentum. Constructing low-volatility, research-driven portfolios shields family reserves against severe downturns while delivering reliable long-term expansion. Through institutional-grade governance and collaboration with an internal Investment Committee, families gain access to sophisticated modelling tailored to their exact liquidity schedules. Discerning Shire households frequently turn to bespoke investment advice Sydney specialists to secure resilient, evidence-based asset structures.
Family Risk Management and Wealth Preservation
Protecting your wealth engine is just as vital as growing it. Unexpected illness or injury can dismantle years of disciplined accumulation if income streams vanish. Structuring life, TPD, and income protection inside superannuation cushions the family against catastrophic shocks while conserving liquid cash flow. Incorporating robust wealth preservation strategies guarantees that your family's financial roadmap remains unbroken, no matter what surprises arise. To review how these interlinked pillars can support your household, partner with True North Lifestyle for clear, methodical direction.
Intergenerational Legacy: Estate Planning Strategies for Your Children
A simple Will rarely offers sufficient protection for growing Shire households. Effective legacy design requires an integrated strategy that shields accumulated assets from relationship breakdowns, future business liabilities, and tax leakage. Estate planning isn't merely an administrative exercise for the distant future; it's an active shield defending your children's financial security right now. Through proactive financial planning for families Miranda households can structure their balance sheets to preserve generational wealth with methodical certainty.
Protecting Family Assets Across Generations
Transferring capital smoothly requires deliberate alignment between separate legal entities. Standard distributions often expose young beneficiaries to unnecessary tax burdens. Establishing testamentary discretionary trusts allows investment income generated by the inheritance to be distributed to minor children or grandchildren at adult marginal tax rates, preserving capital value. Superannuation assets demand equal attention. Because superannuation balances bypass your Will by default, non-lapsing binding death benefit nominations must be kept accurate to avoid protracted estate disputes. Coordinating these mechanisms through comprehensive wealth transfer strategies Australia families trust ensures that your multi-decade accumulation remains intact.
Mitigating Future Risks for Dependants
Protecting capital requires proactive risk management. Without structural buffers, adult children receiving lump-sum inheritances face significant exposure to future commercial claims or matrimonial settlements. Discretionary testamentary structures ring-fence core family wealth, keeping capital secure within your family line. Crucially, structured planning models long-term guardianship liquidity, ensuring funding for private education, healthcare, and daily living is available immediately without forcing fire-sales of key property.
While strategic advisers design this overarching architecture and run financial sustainability projections, we coordinate directly with qualified estate planning lawyers who draft the legal deeds and testamentary documents. This collaborative approach guarantees that your strategic objectives are faithfully reflected in your legal structures, providing lasting reassurance for the entire family.
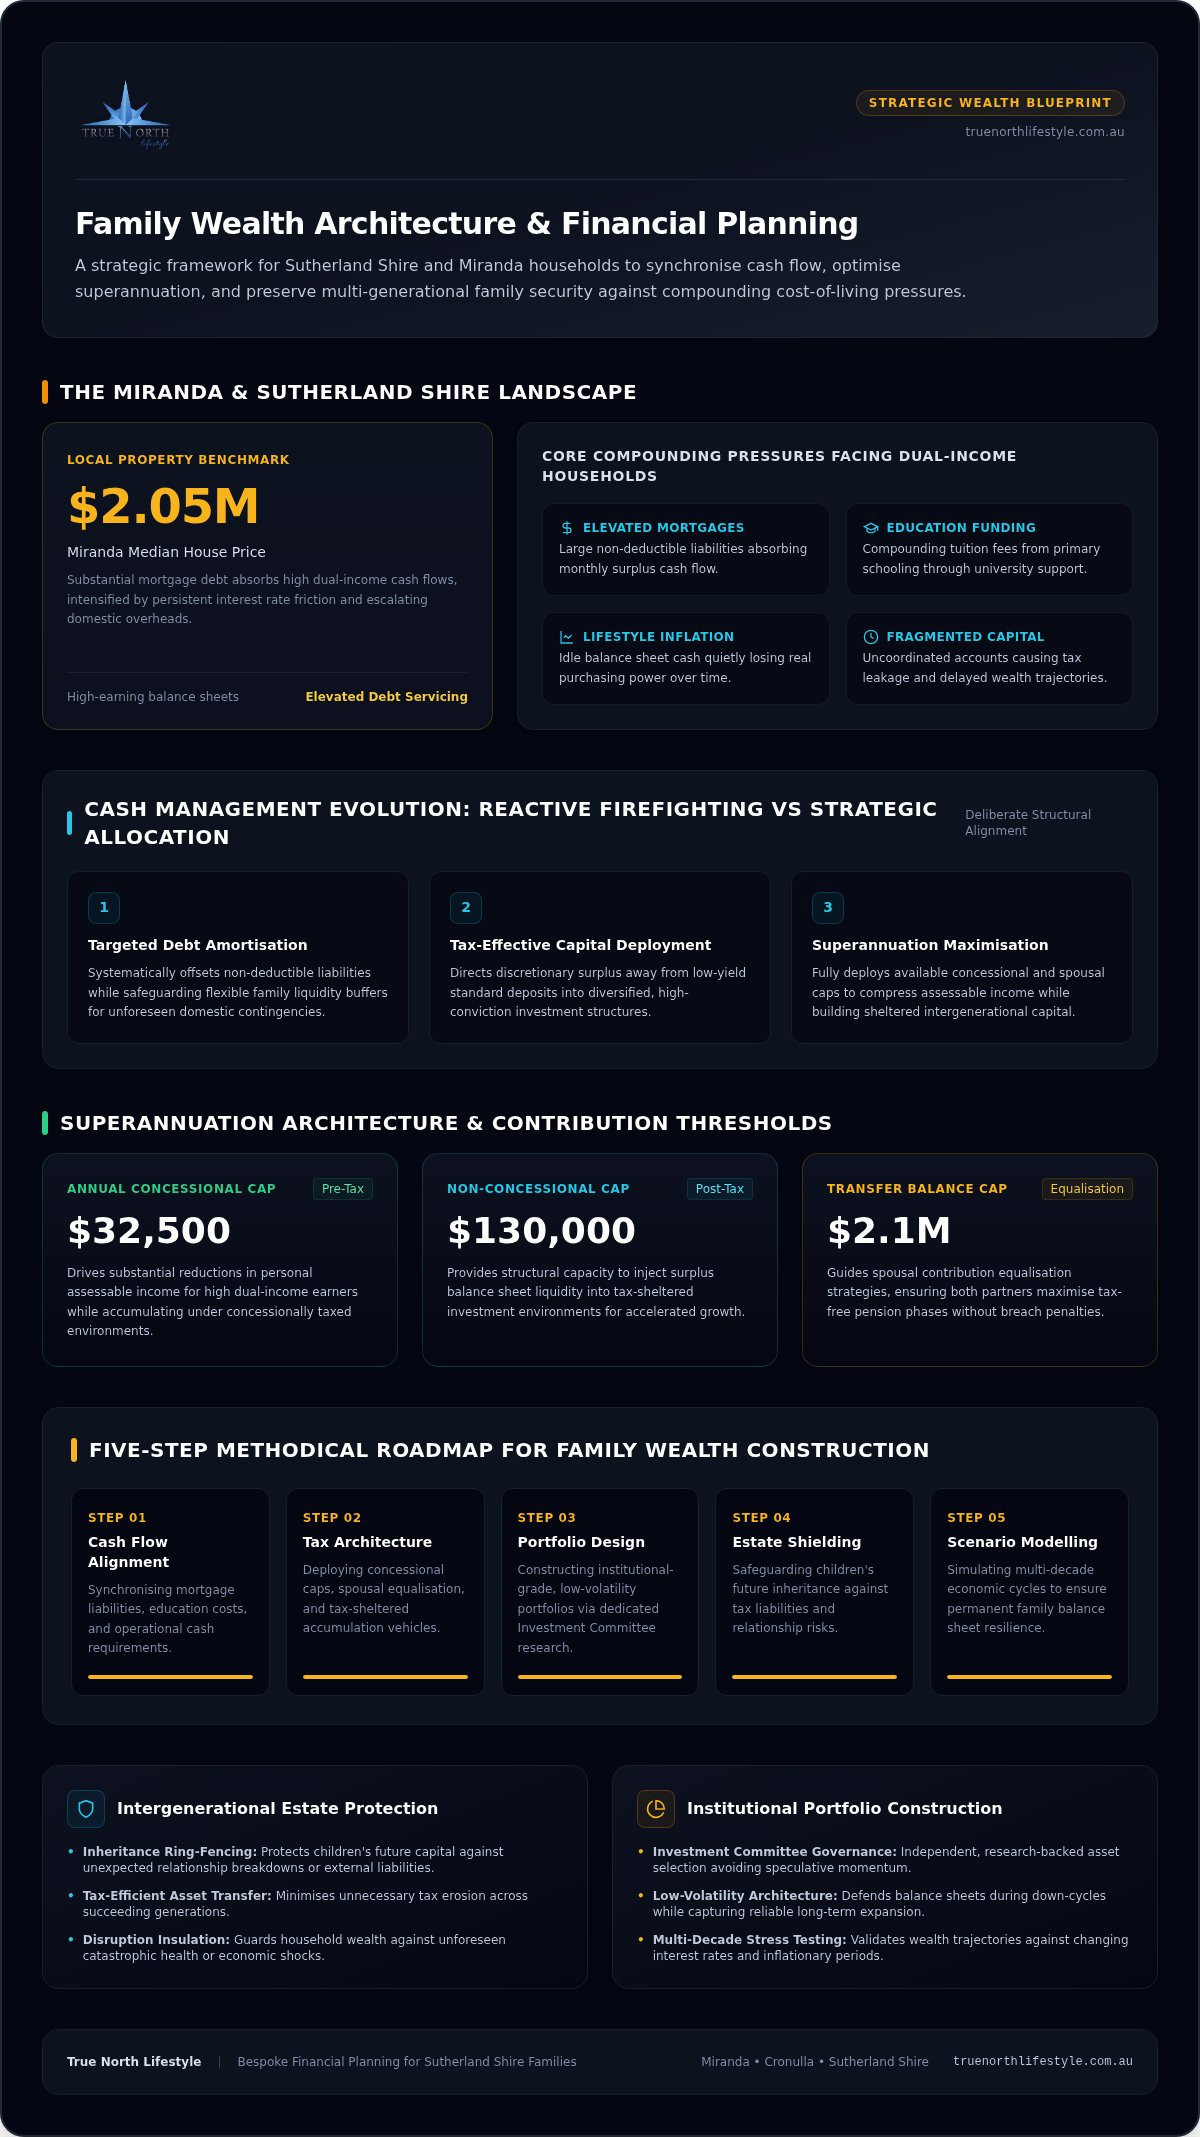
Five Steps to Constructing Your Family Financial Plan in 2026
Clarity requires a methodical process. Rather than relying on static checklists, a modern family roadmap demands dynamic, scenario-tested architecture. High-calibre financial planning for families Miranda households depend on follows a structured, five-stage progression designed to replace guesswork with empirical certainty.
- Balance Sheet & Cash Flow Mapping: Consolidating liabilities, spending habits, surplus capital, and tax brackets into one unified view.
- Multi-Decade Scenario Modelling: Stress-testing family balance sheets against changing interest rates, tuition horizons, and career transitions.
- Portfolio & Superannuation Realignment: Structuring tax-sheltered contributions and bespoke, low-volatility investment management.
- Defensive Structuring: Establishing appropriate personal risk coverage and family estate architectures to protect dependants.
- Dynamic Annual Governance: Calibrating strategies yearly against changing legislative caps and personal priorities.
Phase 1 to 3: Discovery, Modelling, and Portfolio Alignment
Rigorous planning begins with listening. Discovery captures both qualitative household ambitions and precise asset figures, ensuring the strategy reflects your genuine family priorities. Advanced cash flow modelling then pinpoints latent capital leakages without encroaching on your weekend lifestyle. Incorporating institutional-grade retirement planning Sydney principles at this stage ensures that accumulation targets remain on track decades before you actually decide to step away from full-time work.
Phase 4 to 5: Protective Execution and Dynamic Reviews
Action cements stability. Step four implements necessary life, trauma, and income protection policies inside tax-advantaged structures, shielding the family from earning disruptions without administrative burdens. Step five subjects the entire financial architecture to rigorous stress-testing against market pullbacks, persistent rate fluctuations, and unexpected health events. Setting an annual review cadence ensures contribution caps and ownership structures adapt as regulatory environments evolve. If you are ready to construct a clear, resilient financial blueprint for your household, schedule a consultation with True North Lifestyle today.
Why Miranda Families Choose True North Lifestyle as Their Financial Guide
Confidence stems from clarity. While many firms push transactional product sales or disconnected tax checklists, True North Lifestyle serves as a steady anchor for households seeking deliberate direction. We deliver bespoke, institutional-grade guidance built specifically around your family's distinct timeline, values, and commitments. Through purposeful financial planning for families Miranda clients gain an enduring partnership that replaces reactive stress with systematic, quiet certainty.
A Steady, Disciplined Approach to Wealth
Sound stewardship prioritises durability. Through our collaborative partnership with Resonant Asset Management, our clients benefit from the direct oversight of an internal Investment Committee. This institutional structure curates bespoke portfolios designed around capital preservation, risk containment, and steady compounding across economic cycles. Our physical presence in Miranda 2228 and the Sydney CBD ensures responsive, face-to-face counsel right when you need it, bridging technical precision with authentic local understanding.
Taking the First Step Toward Certainty
Gaining full oversight of your balance sheet transforms how you live today. A comprehensive family review removes ambient anxiety, providing absolute clarity on your journey toward long-term independence. To examine how structured contribution strategies and balanced portfolios preserve your wealth, explore our dedicated superannuation advice Sutherland Shire guide. When you are ready to anchor your household with structured financial planning for families Miranda advisors provide, book your confidential family consultation with our team today.
Chart a Confident Financial Course for Your Family
Lasting security isn't accidental. It requires deliberate alignment between current household cash flow, tax-sheltered superannuation, and robust intergenerational asset protections. By moving past reactive money management and adopting comprehensive financial planning for families Miranda parents can effectively neutralise high local living costs while insulating their children's future against economic volatility.
True North Lifestyle provides the disciplined guidance your family balance sheet deserves. Backed by our partnership with Resonant Asset Management and the research-driven oversight of our Investment Committee, we engineer bespoke portfolios designed for low volatility and steady capital growth. With an accessible advisory presence in Miranda 2228 and the Sydney CBD, our team helps replace uncertainty with quiet, lasting structure. Schedule a confidential family wealth consultation with True North Lifestyle today and take confident ownership of your family's financial journey.
Frequently Asked Questions
When should a family in Miranda consider engaging a professional financial planner?
Shire families typically engage advice when household cash flow becomes complex or surplus capital sits idle. Common catalysts include managing substantial property debt, coordinating multi-decade education expenses, or navigating dual career progression. Seeking tailored financial planning for families Miranda residents trust early prevents costly compounding oversights, replacing reactionary budgeting with a structured, long-term balance sheet strategy that secures your family's lifestyle.
How can financial planning help us balance high mortgage rates with private school fees?
We model your household cash flow against interest rate shifts and upcoming tuition milestones across the Sutherland Shire. Rather than forcing severe lifestyle sacrifices, strategic planning restructures liquidity buffers, optimises debt amortisation, and identifies latent tax efficiencies. This disciplined approach releases discretionary surplus, ensuring ongoing private schooling commitments don't cannibalise long-term wealth accumulation or retirement security.
Can True North Lifestyle assist with our family superannuation and retirement projections?
Yes, comprehensive superannuation optimisation and retirement modelling form the core of our advisory services. We model dual-income projections across decades, stress-testing different retirement timelines and contribution levels against shifting legislative caps. By implementing tailored spousal contributions and tax-sheltered super strategies, we help Miranda families build robust retirement reserves well ahead of their targeted transition age.
What is the difference between family budgeting and strategic financial planning?
Family budgeting focuses purely on tracking historical expenses and monthly cash outflows. Strategic financial planning, by contrast, takes a multi-decade architectural view of your entire balance sheet. It deliberately synchronises tax minimisation, superannuation growth, risk mitigation, and low-volatility portfolio management, ensuring current household earnings actively construct lasting generational wealth rather than merely paying monthly bills.
Does your advisory firm help with estate planning and protecting inheritances for our children?
We design the overarching estate planning strategy to protect your assets across generations. This includes structuring testamentary trust frameworks, reviewing binding death benefit nominations, and ring-fencing capital against potential commercial liabilities or relationship breakdowns. While we model the strategic transfer and continuity of family wealth, we partner directly with qualified estate lawyers who draft the formal legal deeds.
How do you coordinate family investments to minimise market volatility?
In partnership with Resonant Asset Management and our internal Investment Committee, we construct bespoke portfolios tailored to contain downside risk. Rather than speculating on market trends, our disciplined philosophy emphasises high-quality asset allocation, liquidity management, and capital preservation. This research-driven governance insulates family wealth from market corrections while delivering steady compounding returns to support future lifestyle milestones.
Do you provide mortgage broking or tax return preparation services for local families?
True North Lifestyle does not provide direct mortgage broking or tax return preparation services. Our focus remains strictly on holistic, strategic advisory, including long-term modelling, wealth preservation, and tax-minimisation strategies. We routinely collaborate alongside your existing mortgage broker and registered tax accountant, ensuring all debt structuring and annual tax filings integrate smoothly with your overarching family wealth roadmap.


