

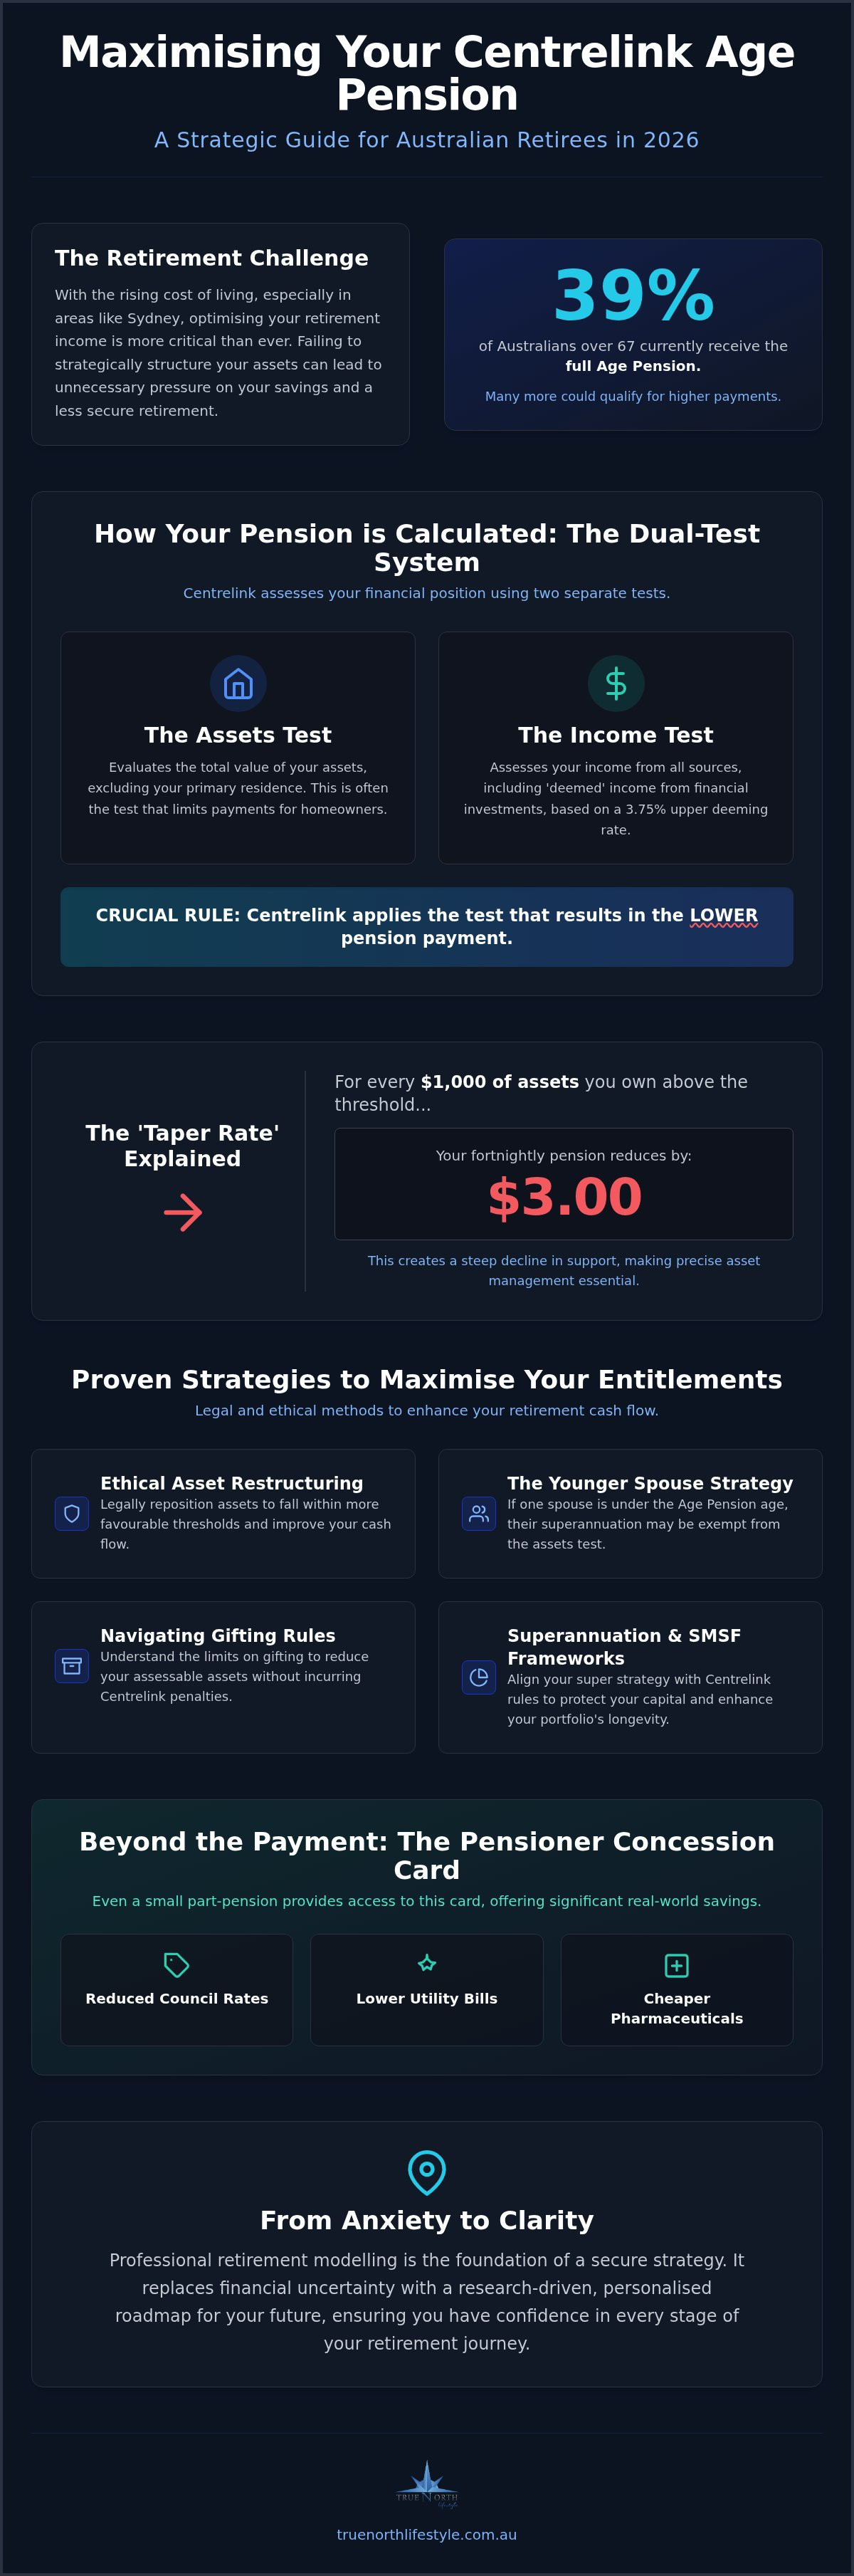
Strategy defines outcome. Roughly 39% of Australians over the age of 67 currently receive the full Age Pension, yet many more could qualify for higher payments through disciplined asset structuring. In a high-cost environment like Sydney, where the 2026 cost of living continues to rise, every fortnightly increase provides a vital buffer against financial uncertainty. You've spent decades building your wealth; however, failing to maximise Centrelink age pension through precise modelling can result in unnecessary pressure on your private capital.
Complexity creates anxiety. It's entirely natural to feel overwhelmed by the intricate web of deeming rates and asset tests that govern your entitlements. We recognise the frustration of managing complex taper rates while facing the persistent fear of outliving your hard-earned savings. This article provides a clear roadmap to legally and ethically restructure your assets to enhance your retirement cash flow and secure your peace of mind. You will discover a detailed breakdown of the September 2026 rate increases, the impact of the 3.75% upper deeming rate, and the specific strategies required to ensure your retirement strategy is fully optimised for the years ahead.
Key Takeaways
- Gain clarity on the 2026 economic landscape and how the rising cost of living in Sydney necessitates a proactive approach to your retirement cash flow.
- Master the mechanics of the dual-test system to identify specific, legal opportunities to maximise Centrelink age pension through ethical asset restructuring.
- Identify the hidden benefits of the younger spouse strategy and understand how to navigate gifting rules without incurring avoidable Centrelink penalties.
- Evaluate advanced superannuation and SMSF frameworks designed to enhance your portfolio's longevity while remaining compliant with the latest regulations.
- Understand why professional retirement modelling is the foundation of a secure strategy, replacing financial anxiety with a research-driven roadmap for your future.
Navigating the 2026 Centrelink Age Pension: Why Strategic Planning Matters
Retirement is a transition. It's a fundamental shift from the accumulation of wealth to the disciplined distribution of it. Within the broader framework of Australia's social security system, the Age Pension serves as much more than a simple safety net. It's a foundational pillar of a sophisticated financial plan, providing a reliable floor for your retirement income. Even for those with healthy superannuation balances, the ability to maximise Centrelink age pension entitlements can be the difference between a lifestyle of careful budgeting and one of genuine confidence.
Living in Sydney in 2026 presents specific pressures. Inflation has shifted the goalposts, and the cost of living in the Sutherland Shire continues to demand more from your liquid reserves. Many residents face the "Miranda Home Trap." They live in high-value primary residences that are rightfully excluded from the assets test, yet they find themselves just over the threshold for a part-pension due to their other investments. This creates a state of being asset-rich but cash-flow constrained. Moving from this state of anxiety to one of clarity requires a strategic approach that views the pension as an integrated component of your total wealth, rather than an isolated government benefit.
The Emotional Value of the Part-Pension
Certainty brings calm. For many retirees, the true value of qualifying for even a small part-pension lies in the Pensioner Concession Card. This card provides significant reductions on council rates, utility bills, and pharmaceutical costs, often providing more "real world" financial relief than the fortnightly payment itself. It functions as a permanent buffer against market volatility. When investment markets fluctuate, that guaranteed government support remains a steady anchor. It ensures that the small daily pleasures, like a morning coffee by the beach, remain part of your lifestyle without the weight of financial guilt.
The Interplay of Super and Centrelink
Structure dictates flow. Superannuation is not a static asset; it's a flexible tool that must be managed in direct conversation with Centrelink rules. The way you categorise and access your super can significantly influence your pension outcome. Obtaining specialised superannuation advice Australia wide is a critical step in the years leading up to your retirement date. By aligning your private portfolio with public entitlements, you can maximise Centrelink age pension while protecting your capital for the long term. This bespoke coordination allows you to establish a predictable, multi-layered income stream that supports your lifestyle through every stage of your retirement journey.
The Mechanics of Means Testing: Asset and Income Test Thresholds
Logic dictates the outcome. To maximise Centrelink age pension entitlements, you must first understand the dual-test architecture that the government employs. The system evaluates your financial position through two distinct lenses: the Assets Test and the Income Test. Crucially, the test that produces the lower payment rate is the one that Centrelink applies to your fortnightly distribution. While many Sutherland Shire residents pass the income test with ease, they often find their payments curtailed by the sheer value of their accumulated assets.
The "Taper Rate" is the primary mechanism that reduces your payment as your wealth grows. As of 2026, your fortnightly Age Pension is reduced by $3.00 for every $1,000 of assets you hold above the full pension threshold. This creates a steep decline in support for those whose portfolios sit just above the limit. Precision in retirement modelling is required to identify where your assets sit on this curve and whether restructuring could move you into a more favourable payment bracket.
The 2026 Asset Test Limits
Structure provides clarity. The thresholds for the Services Australia Age Pension are adjusted periodically to reflect economic shifts, and the 2026 limits define the current playing field. For a single homeowner, the full pension is available for assets up to $333,000, while the part pension cuts out entirely at $745,750. Couples who own their home can hold up to $499,000 for a full pension, with the upper limit for a part pension sitting at $1,121,000. It's vital to remember that "assets" include almost everything of value you own, from the vehicle in your driveway to the market value of your household contents and personal effects.
The Income Test and Deeming
Assumptions drive the calculation. Centrelink doesn't always look at the actual interest or dividends your bank account earns; instead, they use "deeming" to assume a set rate of return on your financial assets. In 2026, the lower deeming rate is 1.75% for initial thresholds, while the upper rate has reached 3.75% for assets above those limits. This can create a discrepancy between your actual cash flow and your assessable income. However, the Work Bonus remains a valuable tool, allowing you to earn up to $300 per fortnight from employment without it impacting your income test. Managing these variables requires bespoke investment advice Sydney retirees can use to ensure their portfolio remains both productive and pension-efficient.
Proven Strategies to Maximise Your Entitlements
Structure determines outcome. While the means-testing rules are rigid, the way you categorise your capital remains flexible. You can legally and ethically maximise Centrelink age pension payments by shifting wealth from assessable categories into exempt ones. This process isn't about hiding assets; it's about using the established rules to ensure your financial architecture is as efficient as possible. By making deliberate choices today, you can replace the anxiety of a diminishing balance with the quiet certainty of a structured income stream.
The Gifting Framework
Generosity requires boundaries. Many Sydney parents wish to assist their children with property deposits or education costs, but direct transfers can trigger "deprived asset" penalties if not managed correctly. Under current regulations, you can gift up to $10,000 in a single financial year, with a total cap of $30,000 over a rolling five-year period. Any amount exceeding these limits continues to be counted by Centrelink as your asset for five years from the date of the gift. Integrating these gifts into a broader wealth transfer strategy Australia wide ensures you support your family without compromising your own fortnightly cash flow.
The "Younger Spouse Strategy" is a significant, often overlooked advantage for couples with an age gap. If your partner is below Age Pension age, their superannuation held in the accumulation phase is generally not counted as an assessable asset by Centrelink. Shifting funds into their account can effectively "hide" capital from the means test until they reach pension age. Similarly, investing in your primary residence through renovations or upgrades converts assessable cash into an exempt lifestyle asset. This not only improves your quality of life in Miranda or the wider Shire but also reduces your asset count. Pre-paying funeral expenses or investing in funeral bonds serves a similar purpose, removing those funds from the means-testing view while providing emotional relief for your family.
Strategic Asset Reallocation
Precision creates stability. Certain financial products, such as lifetime annuities, receive preferential treatment under the Department of Social Services guidelines, where only a portion of the investment is assessable under the assets test. Another sophisticated approach is the "Superannuation Re-contribution Strategy," which involves withdrawing funds and re-contributing them as non-concessional amounts. This can potentially reduce future tax for your beneficiaries while re-aligning your pension eligibility. Finally, always value your personal assets, such as cars or household furniture, at their realistic resale value rather than their insured replacement value. This simple adjustment can often shave thousands off your assessable total and move you closer to a higher payment bracket.
Advanced Structuring: Superannuation and Lifestyle Considerations
Strategy evolves with complexity. While simple asset reallocation offers immediate relief, advanced financial frameworks provide long-term resilience. For those still active in the Sydney CBD, a Transition to Retirement (TTR) strategy can be a powerful tool. It allows you to access a portion of your super while continuing to work, effectively smoothing the path into full retirement. This approach, when combined with disciplined efforts to maximise Centrelink age pension, creates a robust income floor that adapts as your lifestyle needs shift. It's about maintaining momentum while preparing for a slower pace.
Self-Managed Super Funds (SMSFs) offer unparalleled control, yet they require meticulous oversight to remain pension-efficient. The way an SMSF holds assets, particularly in the 2026 landscape of account-based pensions, determines how much of your wealth is assessable. It's a delicate balance. You must ensure your estate planning strategy remains intact; a poorly structured pension plan can inadvertently create tax liabilities for your beneficiaries or complicate the transfer of wealth. Protecting your legacy is just as important as securing your current cash flow.
Superannuation Optimisation
Efficiency starts with structure. The composition of your superannuation accounts is often more critical than the total balance. For couples, "balancing the scales" by shifting contributions to the spouse with the lower balance can keep both individuals beneath the asset test thresholds for a longer duration. This coordination is a vital component of tax planning for retirement Australia wide, as it minimises the tax burden on your distributions while protecting your government entitlements. A bespoke approach ensures that no dollar is left vulnerable to unnecessary assessment.
Lifestyle Assets vs. Financial Assets
Lifestyle choices have financial consequences. In Sydney's competitive property market, the "Granny Flat interest" has emerged as a sophisticated method for asset reallocation. By paying for a life interest in a relative's home, you can effectively transfer assessable cash into a non-assessable residential right. Similarly, upgrading your family car or purchasing a new caravan can be a strategic move; you are converting liquid capital that Centrelink assesses into personal assets valued at their lower resale price. Before pursuing these paths, prioritising debt is essential. Paying down a mortgage on your primary residence is almost always the most effective first step, as equity in your home remains entirely exempt from the assets test. To ensure your structure is truly optimised, you can book a retirement modelling session with our team to project your long-term outcomes.
Securing Your Future: The Role of Professional Retirement Modelling
Structure replaces guesswork. While many retirees attempt to navigate the Centrelink portal independently, "DIY" planning often overlooks the subtle, cascading effects of asset reallocation on the taper rate. A single miscalculation regarding the valuation of personal effects or an incorrectly timed gift can result in thousands of dollars in lost entitlements over the course of a retirement. True North Lifestyle provides a research-driven methodology that moves beyond simple spreadsheets. We utilise sophisticated modelling to project your income decades into the future, ensuring your strategy remains resilient against shifting legislation and economic cycles.
Bespoke portfolio construction is the secondary pillar of a secure retirement. It is not enough to simply hold assets; you must hold them in a framework that aligns with current deeming rates and income thresholds. By strategically categorising your wealth, we can help you maximise Centrelink age pension payments while maintaining a low-volatility, income-focused portfolio. This level of technical depth allows you to step into a role of confident oversight, knowing the rigorous testing and heavy lifting have already been completed by a professional partner.
The Power of Longevity Projections
Clarity provides peace of mind. Our modelling allows you to explore various "what if" scenarios, such as the long-term impact of a significant home renovation or the consequences of a family gifting strategy. By visualising how these choices affect your capital longevity, you can make informed decisions without the persistent fear of outliving your savings. This is a core component of a comprehensive wealth preservation strategy. We help Miranda and Sydney residents find their "True North," replacing the inherent anxiety of retirement with a structured, well-defined path toward quiet certainty.
Next Steps for Sydney Retirees
Momentum requires action. A comprehensive financial health check is the first step toward securing your retirement cash flow and ensuring your portfolio is as efficient as possible. When you prepare for a consultation with a True North advisor in Miranda, gather your current superannuation statements, investment summaries, and a realistic estimate of your household assets. This data allows us to build a precise model tailored to your specific circumstances, providing you with a clear roadmap for the years ahead.
Organise a retirement modelling session with True North Lifestyle today to ensure your strategy is fully optimised for 2026 and your future is anchored in stability.
Anchoring Your Future in Certainty
Order brings peace. Navigating the 2026 financial landscape requires more than just a basic understanding of government thresholds; it demands a disciplined, research-driven approach to your entire portfolio. By understanding how to maximise Centrelink age pension entitlements through ethical asset restructuring and the younger spouse strategy, you replace the anxiety of fluctuating markets with a structured income floor. Whether you are managing the "Miranda Home Trap" or navigating complex deeming rates, the goal remains the same: ensuring your capital works as hard as possible to support your lifestyle.
True North Lifestyle acts as your steady navigator. With oversight from our in-house Investment Committee and specialised expertise in retirement cash flow modelling, we provide the technical depth required to simplify the complex. We serve the Sutherland Shire and Sydney CBD, offering the local knowledge and professional authority you need to protect your legacy. Don't leave your retirement to chance or outdated DIY methods. Secure your retirement clarity with a bespoke consultation at True North Lifestyle and step into the next chapter of your life with quiet certainty and a well-defined path.
Frequently Asked Questions
How much can I have in assets and still get the Age Pension in 2026?
As of late 2026, the asset limits for a part pension vary based on your living situation. A single homeowner can hold up to $745,750 in assessable assets, while a couple who own their home can hold up to $1,121,000. Non-homeowners have higher thresholds, reaching $1,012,750 for singles and $1,388,000 for couples. These figures are critical for those looking to maximise Centrelink age pension entitlements through strategic portfolio reallocation and disciplined modelling.
Does my family home count towards the Centrelink asset test?
Your principal place of residence is generally exempt from the assets test. This remains one of the most effective ways to protect your wealth while qualifying for government support. However, the land surrounding your home must be on the same title and be two hectares or less to maintain this full exemption. For residents in the Sutherland Shire with larger properties, specific rules apply that require careful modelling to ensure your home remains a protected asset.
What are the gifting rules for the Age Pension in Australia?
You can gift up to $10,000 in a single financial year without impacting your pension. There is also a total limit of $30,000 over a rolling five-year period. If you exceed these amounts, Centrelink treats the excess as a deprived asset for five years from the date of the gift. This means the money is still counted in your asset and income tests, even though you no longer have access to that capital.
How does the deeming rate work for my bank accounts and shares?
Deeming is the method Centrelink uses to assume a rate of return on your financial assets regardless of what they actually earn. In 2026, the lower deeming rate is 1.75% for assets up to specific thresholds. Amounts above these limits are deemed at 3.75%. This system simplifies the reporting process but requires a proactive approach to ensure your actual investment returns aren't being outpaced by the government's assumed rates of return.
Can I still work and receive the Age Pension?
You can certainly continue to work while receiving the Age Pension. Your employment income is assessed under the income test, which may reduce your fortnightly payment if you exceed the allowable thresholds. For a single person, the part pension continues until your fortnightly income reaches $2,701.40. Working in retirement provides both financial benefits and social engagement, provided you understand how your earnings interact with the broader means-testing framework and Sydney's cost of living.
What is the Work Bonus and how do I apply for it?
The Work Bonus is an incentive that allows you to keep more of your pension while working. It ignores the first $300 of your fortnightly employment income when calculating your pension rate. You don't need to apply for the Work Bonus; Centrelink applies it automatically when you report your income. Unused portions of the $300 bonus can accumulate in a work bonus income bank up to a maximum of $11,800 to offset future earnings.
Is it better to have my super in an industry fund or an SMSF for Centrelink?
Neither structure is inherently superior for Centrelink purposes; the choice depends on your need for control and the complexity of your assets. An industry fund offers simplicity and lower administrative oversight. Conversely, a Self-Managed Super Fund (SMSF) provides the flexibility to hold specific assets that might be structured more efficiently for the means test. Professional modelling is essential to determine which vehicle best helps you maximise Centrelink age pension outcomes over the long term.
How often do Centrelink pension rates change?
Age Pension rates are typically adjusted twice a year, in March and September, to keep pace with inflation and wage growth. The asset and income test thresholds for a full pension are updated annually on 1 July. These regular indexations ensure that your purchasing power is maintained, even as the cost of living in Sydney fluctuates. Staying informed about these dates allows you to adjust your retirement strategy with precision and a sense of quiet certainty.


