

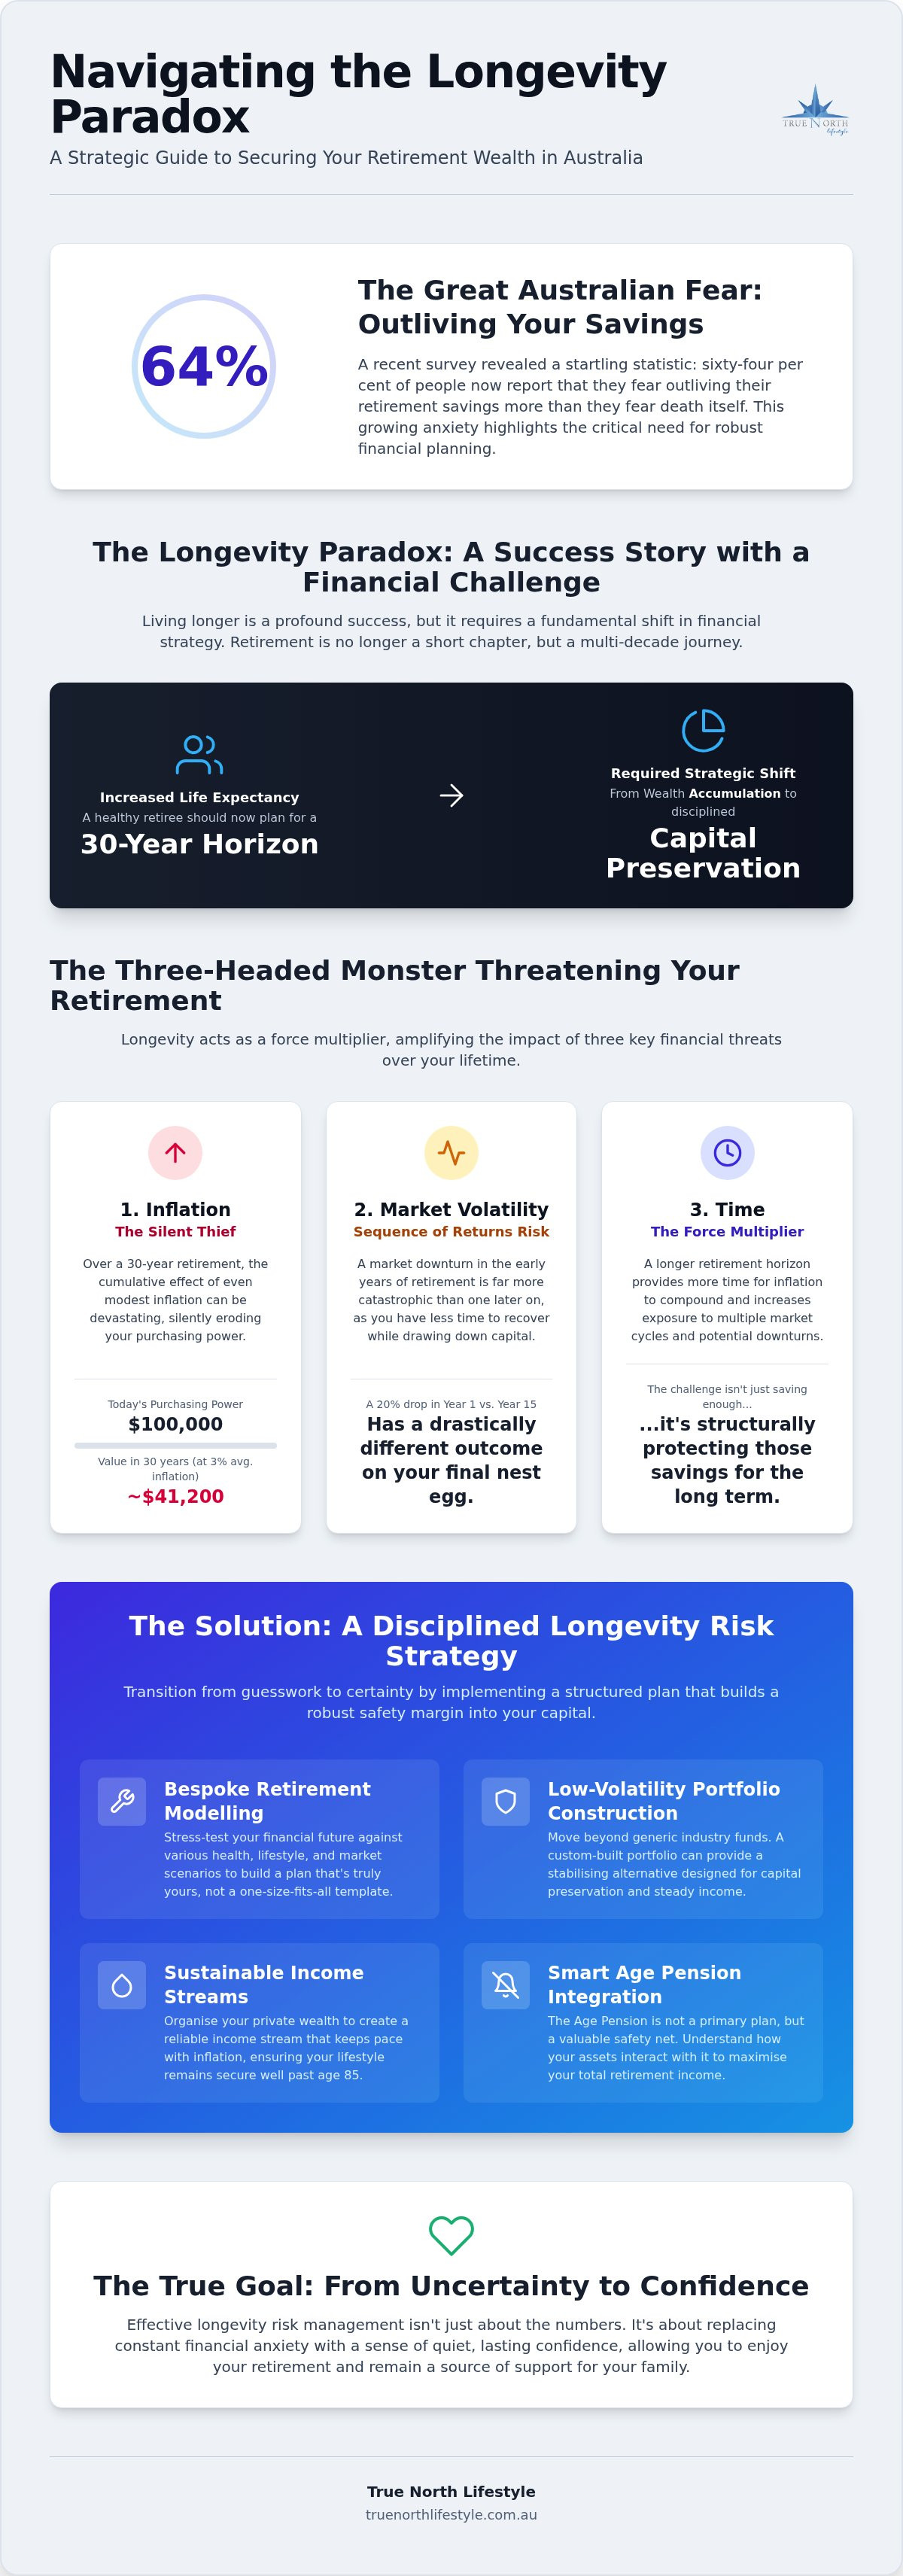
Sixty-four per cent of people now report that they fear outliving their retirement savings more than they fear death itself. It's a heavy emotional burden, particularly as the rising cost of living in Sydney puts pressure on even the most diligent savers. You likely feel the tension between wanting to enjoy your hard-earned wealth today and the deep-seated need to ensure you never become a financial weight on your children's shoulders.
Effective longevity risk management offers a path out of this anxiety by replacing guesswork with structural certainty. It is about building a robust safety margin into your capital through bespoke modelling and low-volatility investing. In this article, you will learn how to organise your private wealth to create a sustainable income stream that keeps pace with inflation. We provide clarity on how your assets interact with the Age Pension, ensuring your lifestyle remains secure well past age 85. By moving toward a disciplined, evidence-based strategy, you can transition from financial uncertainty to a state of quiet, lasting confidence.
Key Takeaways
- Reframe the "longevity paradox" as a personal success that requires a strategic shift from wealth accumulation to disciplined capital preservation.
- Discover how robust longevity risk management can neutralise the "three-headed monster" of inflation, market volatility, and sequence of returns risk.
- Compare the structural benefits of guaranteed income through annuities against the flexibility of account-based pensions in the current economic climate.
- Identify the essential inputs for professional retirement modelling to stress-test your financial future against various health and lifestyle scenarios.
- Learn how bespoke portfolio construction provides a stabilising alternative to the volatility often found in one-size-fits-all industry funds.
What is Longevity Risk and Why Does it Matter in 2026?
Longevity risk is often misunderstood. It is essentially the statistical probability that you will outlive your financial resources. In simpler terms, it's the risk of having too much life left at the end of your money. This concept, often termed What is Longevity Risk, has become the central focus of modern retirement planning. We call this the longevity paradox: while living longer is a profound medical success, it presents a significant financial challenge that requires a disciplined approach to capital preservation.
As we move through 2026, Australian Bureau of Statistics (ABS) data confirms that life expectancy continues to climb. A healthy individual retiring today should realistically prepare for a thirty-year horizon, with many reaching their mid-90s or beyond. Within this context, longevity risk management stands as one of the three pillars of a secure retirement, alongside managing market volatility and the eroding effects of inflation. It is no longer enough to simply save; you must structurally protect the purchasing power of those savings for the long term.
The Shifting Australian Retirement Landscape
Sydney's economic environment adds another layer of complexity. For retirees in areas like the Sutherland Shire, high inflation and rising service costs mean that traditional "rules of thumb" are failing. The old 4% withdrawal rule, once a gold standard, often doesn't account for the aggressive cost-of-living spikes we've seen recently. Relying on the Age Pension as a primary income source is increasingly unrealistic for those wishing to maintain a certain lifestyle. Instead, the pension should be viewed as a structural safety net that interacts with your private wealth. This makes professional retirement modelling essential for mapping out how your capital will actually behave over decades. Integrating a dedicated longevity risk management framework ensures that these external pressures don't compromise your long-term solvency.
The Emotional Impact of Financial Uncertainty
Numbers only tell half the story. The true value of a stabilising strategy lies in the mental peace it provides. Constant anxiety about "running out" can lead to unnecessary downsizing or a frugal existence that robs retirement of its joy. You've spent decades in an "accumulation" mindset, focused on growth and building a nest egg. Transitioning to "sustainable preservation" requires a psychological shift. By implementing a structured plan, you replace fear with a sense of quiet certainty. You aren't just managing money; you're protecting your future well-being and ensuring you remain a source of support for your family, rather than a burden.
The Three-Headed Monster: Inflation, Volatility, and Time
Retirement planning is not a static event. It's a dynamic, multi-decade journey where three distinct forces often collide to threaten your financial security. These forces, inflation, market volatility, and time, work in tandem to erode capital. Longevity risk acts as a force multiplier for every other financial threat in retirement. When you live longer, every market downturn has more time to do damage, and every price increase has more years to compound. Understanding these interactions is the first step toward effective longevity risk management.
Inflation: The Silent Thief of Purchasing Power
Prices never stand still. While a 3% or 4% inflation rate might seem manageable in a single year, its cumulative effect over a thirty-year retirement is devastating. For a retiree in Sydney, the cost of essential services, healthcare, and lifestyle amenities in 2040 will likely look vastly different than they do today. If your income remains flat while the cost of a medical appointment or a weekly grocery shop doubles, your standard of living must inevitably decline. According to in-depth research on longevity risk, many retirees underestimate this "silent thief" and gravitate toward "safe" assets like cash. However, cash often delivers negative real returns after inflation, meaning your "safe" investment is actually guaranteeing a loss of purchasing power over time. Maintaining real income growth requires a portfolio designed to outpace these rising costs.
Market Volatility and the Danger of Negative Sequences
Timing is everything. One of the most significant yet least understood dangers is Sequence of Returns Risk. This is the risk that a market crash occurs just as you begin drawing down your capital. A 20% drop in your first year of retirement is far more catastrophic than the same drop in your twentieth year. When you're forced to sell assets at depressed prices to fund your lifestyle, you deplete your portfolio's ability to recover when the market eventually turns. This creates a "death spiral" for your savings. To mitigate this, we utilise portfolio stress testing Australia to model how different market paths impact your long-term solvency. By prioritising a "smoother ride" through low-volatility construction, you can ensure that your income stream remains stable even when the broader market is turbulent. If you're concerned about how your current assets would weather a downturn, you might consider a bespoke portfolio review to identify potential vulnerabilities.
Longevity Risk Management Strategies: Comparing Your Options
Choosing the right structure for your retirement capital is a delicate balancing act between certainty and growth. Effective longevity risk management involves evaluating two primary vehicles: account-based pensions and lifetime annuities. An account-based pension keeps your capital market-linked, offering flexibility and potential for growth, yet it leaves the duration of your funds vulnerable to market performance. Conversely, lifetime annuities provide a guaranteed income stream regardless of how long you live or how the market behaves. In the current 2026 interest rate environment, these guaranteed products have regained some appeal, though they often come at the cost of capital access. This is why bespoke investment advice Sydney is critical; it helps you weigh these trade-offs against your personal goals.
An in-depth report on longevity risk highlights that many retirees struggle with the "annuity puzzle", which is the reluctance to trade a lump sum for a guaranteed stream. To solve this, a segmented "bucket strategy" can be highly effective. By allocating capital into short-term cash reserves, medium-term defensive assets, and long-term growth investments, you create a buffer against short-term volatility while maintaining the potential for capital appreciation. This structured approach ensures that you aren't forced to sell growth assets during a market dip just to fund your daily life.
Annuities vs. Market-Linked Pensions
The fundamental trade-off lies between certainty and control. While an annuity offers a "paycheque for life", a market-linked pension allows you to draw more or less as your needs change. Many clients find success with a hybrid approach. By using a portion of their superannuation to purchase a lifetime annuity that covers essential costs, such as Sydney property rates and health insurance, they create a secure floor. The remaining capital is then managed for growth, providing the funds for travel or discretionary lifestyle expenses. This choice also significantly impacts your estate planning strategy Australia, as annuities typically don't leave a residual balance for beneficiaries, unlike an account-based pension.
The Role of Low-Volatility Investing
In the third age of life, your investment priority must shift. Protecting your downside becomes far more valuable than chasing the highest possible upside. At True North, our in-house Investment Committee focuses on constructing portfolios that prioritise income and stability. We use a research-driven methodology to select assets that aim to deliver a smoother ride, reducing the emotional stress of market fluctuations. This approach allows for effective longevity risk management without completely sacrificing the ability to leave a meaningful legacy for the next generation. It's about building a portfolio that is robust enough to last a lifetime, yet flexible enough to adapt to your evolving personal journey.
Practical Steps: Retirement Modelling and Stress Testing
Clarity replaces anxiety. To achieve effective longevity risk management, you need more than just a vague estimate of your savings; you need a dynamic roadmap. Professional retirement modelling serves as this guide, translating complex data into a clear visual projection of your financial future. This process requires detailed inputs, including your current investment assets, superannuation balances, and desired lifestyle costs, alongside realistic health considerations. We don't just look at the "best-case" scenario. We use Monte Carlo simulations to stress-test your plan against 10,000 different market sequences, ensuring your capital survives even the most challenging economic environments. Regular reviews are essential to adjust for legislative shifts or personal life events, keeping your strategy aligned with reality.
Mapping Your Cash Flow Requirements
Sustainable spending is key. We begin by distinguishing between "essential" spending, such as Sydney property rates and utilities, and "lifestyle" spending like travel or hobbies. This distinction allows us to build a dedicated "buffer" for unexpected health or aged care costs that often arise later in life. By utilising retirement cash flow modelling, we can identify your specific sustainable withdrawal rate. This prevents the common mistake of over-withdrawing in the early years of retirement, which can irrevocably damage your long-term solvency. It's about finding the balance that lets you enjoy your wealth today without compromising your security at age 90.
Optimising Superannuation and Tax
Structure dictates outcome. Seeking expert superannuation advice Sutherland Shire can uncover strategic ways to boost your capital's longevity through tax optimisation. For instance, a re-contribution strategy can increase the tax-free component of your super, potentially saving your beneficiaries significant sums in the future. It's also vital to ensure your fund is "fit for purpose" for the drawdown phase. Many industry funds are designed for accumulation; they may lack the sophisticated income-focused features required when you transition to living off your assets. If you're ready to see how these projections apply to your own situation, you can request a retirement modelling consultation to begin your journey toward certainty.
Partnering with a Steady Navigator: The True North Approach
Clarity and confidence. These aren't just aspirations; they're the foundation of a sustainable retirement. At True North Lifestyle, we act as your steady navigator, guiding you through the intricacies of the Australian financial system. Our approach to longevity risk management is grounded in rigorous testing and a no-nonsense commitment to value. Unlike off-the-shelf solutions provided by many industry funds, our bespoke portfolio construction is led by an in-house Investment Committee. We focus on research-driven, low-volatility strategies that eschew speculative gambles in favour of proven outcomes. Having a local financial planner in Miranda means you have a partner who understands the specific pressures of the Sydney property market and local cost-of-living trends.
Beyond the Numbers: A Personalised Strategy
Your wealth is a tool for your life. We believe that a truly effective strategy must align your financial resources with your personal values and the legacy you wish to leave behind. This isn't a one-time transaction. The economic environment is constantly shifting, and a "set and forget" mentality is a dangerous strategy when planning for a thirty-year horizon. We maintain an ongoing advisory relationship to ensure your plan remains robust against legislative changes and life's inevitable surprises. For many clients, the transformation is profound. We have seen modelling transform a client's deep-seated anxiety about Sydney inflation into a state of quiet certainty, simply by providing a structured view of their future solvency.
Taking the First Step Toward Certainty
The path forward is clear. When you visit our Miranda or Sydney CBD offices for a retirement modelling consultation, you'll experience a process designed to simplify the complex. We do the heavy lifting, the rigorous testing, and the technical optimisation so that you don't have to. You step into a role of confident oversight, empowered by the knowledge that your lifestyle is protected. It's about replacing the "what-ifs" with a structured, well-defined path toward longevity. If you're ready to secure your future, organise a consultation with True North Lifestyle today and begin the transition toward a calm, protected retirement.
Securing Your Path to Lasting Confidence
Retirement should be a season of reward, not a period of persistent financial anxiety. By shifting your focus from simple accumulation to a disciplined strategy of structural preservation, you can neutralise the threats of inflation and market volatility. We've established that longevity risk management relies on more than just optimistic projections; it requires rigorous stress testing and bespoke portfolio construction tailored to the unique economic pressures of the Sutherland Shire. Whether you're balancing the Age Pension with private wealth or optimising your superannuation, the goal is a sustainable income that keeps pace with your life.
True North Lifestyle provides the professional oversight and research-driven methodology needed to simplify these complexities. As specialists in local retirement planning, our in-house Investment Committee ensures your capital is managed with a stabilising, calm approach that prioritises your personal values. You've done the hard work of building your wealth. Now, let us provide the steadfast navigation required to protect it for decades to come. Secure your financial future with a bespoke retirement model from True North Lifestyle. It's time to replace uncertainty with a well-defined path toward lasting peace of mind.
Frequently Asked Questions
What is the biggest risk to my retirement savings in Australia?
Longevity risk management addresses the primary threat to your financial security in Australia. It's the statistical probability that you will outlive your capital, leaving you without resources in your final years. In a high-cost environment like Sydney, this risk is compounded by inflation and market volatility. Managing this requires a structural shift from simple growth to wealth preservation, ensuring your assets are protected against multiple economic pressures simultaneously.
How long does the average Australian retirement last?
A typical retirement for Australians today can easily span thirty years or more. Current Australian Bureau of Statistics figures for 2026 show that many retirees should prepare to reach their mid-90s. This extended timeframe means your capital must work harder for longer. It's no longer a matter of surviving a decade; your portfolio must be robust enough to sustain your lifestyle through three decades of shifting market conditions and rising costs.
Can I rely solely on the Age Pension if my savings run out?
The Age Pension provides a basic safety net, but it's rarely enough to maintain a comfortable lifestyle in areas like Miranda or the Sutherland Shire. Relying solely on government support often means a drastic reduction in your standard of living. Effective longevity risk management involves using Centrelink structuring to ensure your private wealth and the pension work together. This creates a more resilient income stream that protects your independence as you age.
What is a sustainable withdrawal rate for a 30-year retirement?
There's no longer a universal "safe" percentage, as traditional benchmarks like the 4% rule don't account for modern Sydney inflation. A sustainable rate is highly personal and depends on your specific assets, tax position, and health. True North utilises bespoke retirement modelling to stress-test various withdrawal scenarios. This process identifies a rate that balances your current lifestyle needs with the absolute necessity of capital lasting your entire lifetime.
How does inflation affect my longevity risk?
Inflation acts as a silent thief that erodes the real value of your savings over time. Even a modest inflation rate can halve your purchasing power over a 25-year retirement. For retirees in Sydney, where service and healthcare costs often rise faster than the general CPI, this is a major component of longevity risk. You must ensure your portfolio includes assets designed to deliver real, inflation-adjusted growth to maintain your standard of living.
Is an annuity better than an account-based pension for managing longevity risk?
Neither is objectively "better" as they serve different purposes within a wealth strategy. An annuity offers a guaranteed "paycheque for life" which provides immense emotional certainty. An account-based pension offers the flexibility and growth potential needed to combat inflation. Many clients in the Sutherland Shire benefit from a hybrid approach, using annuities for essential expenses and market-linked pensions for discretionary spending and legacy goals.
What is sequence of returns risk and how do I avoid it?
Sequence of returns risk is the danger that a market downturn occurs just as you begin your retirement drawdowns. Withdrawing capital during a crash forces you to sell assets at low prices, which can permanently deplete your portfolio. You can mitigate this by adopting low-volatility investing strategies and maintaining a cash buffer. This "bucket" approach ensures you don't have to sell growth assets when the market is underperforming.
How often should I review my retirement longevity plan?
You should review your longevity plan at least once a year. Retirement isn't a static event, and your strategy must adapt to legislative changes, shifts in the Sydney property market, and personal health updates. Regular reviews with a professional allow you to recalibrate your modelling and ensure your withdrawal rates remain sustainable. This ongoing oversight provides the quiet confidence that your financial roadmap is always aligned with your current reality.


