

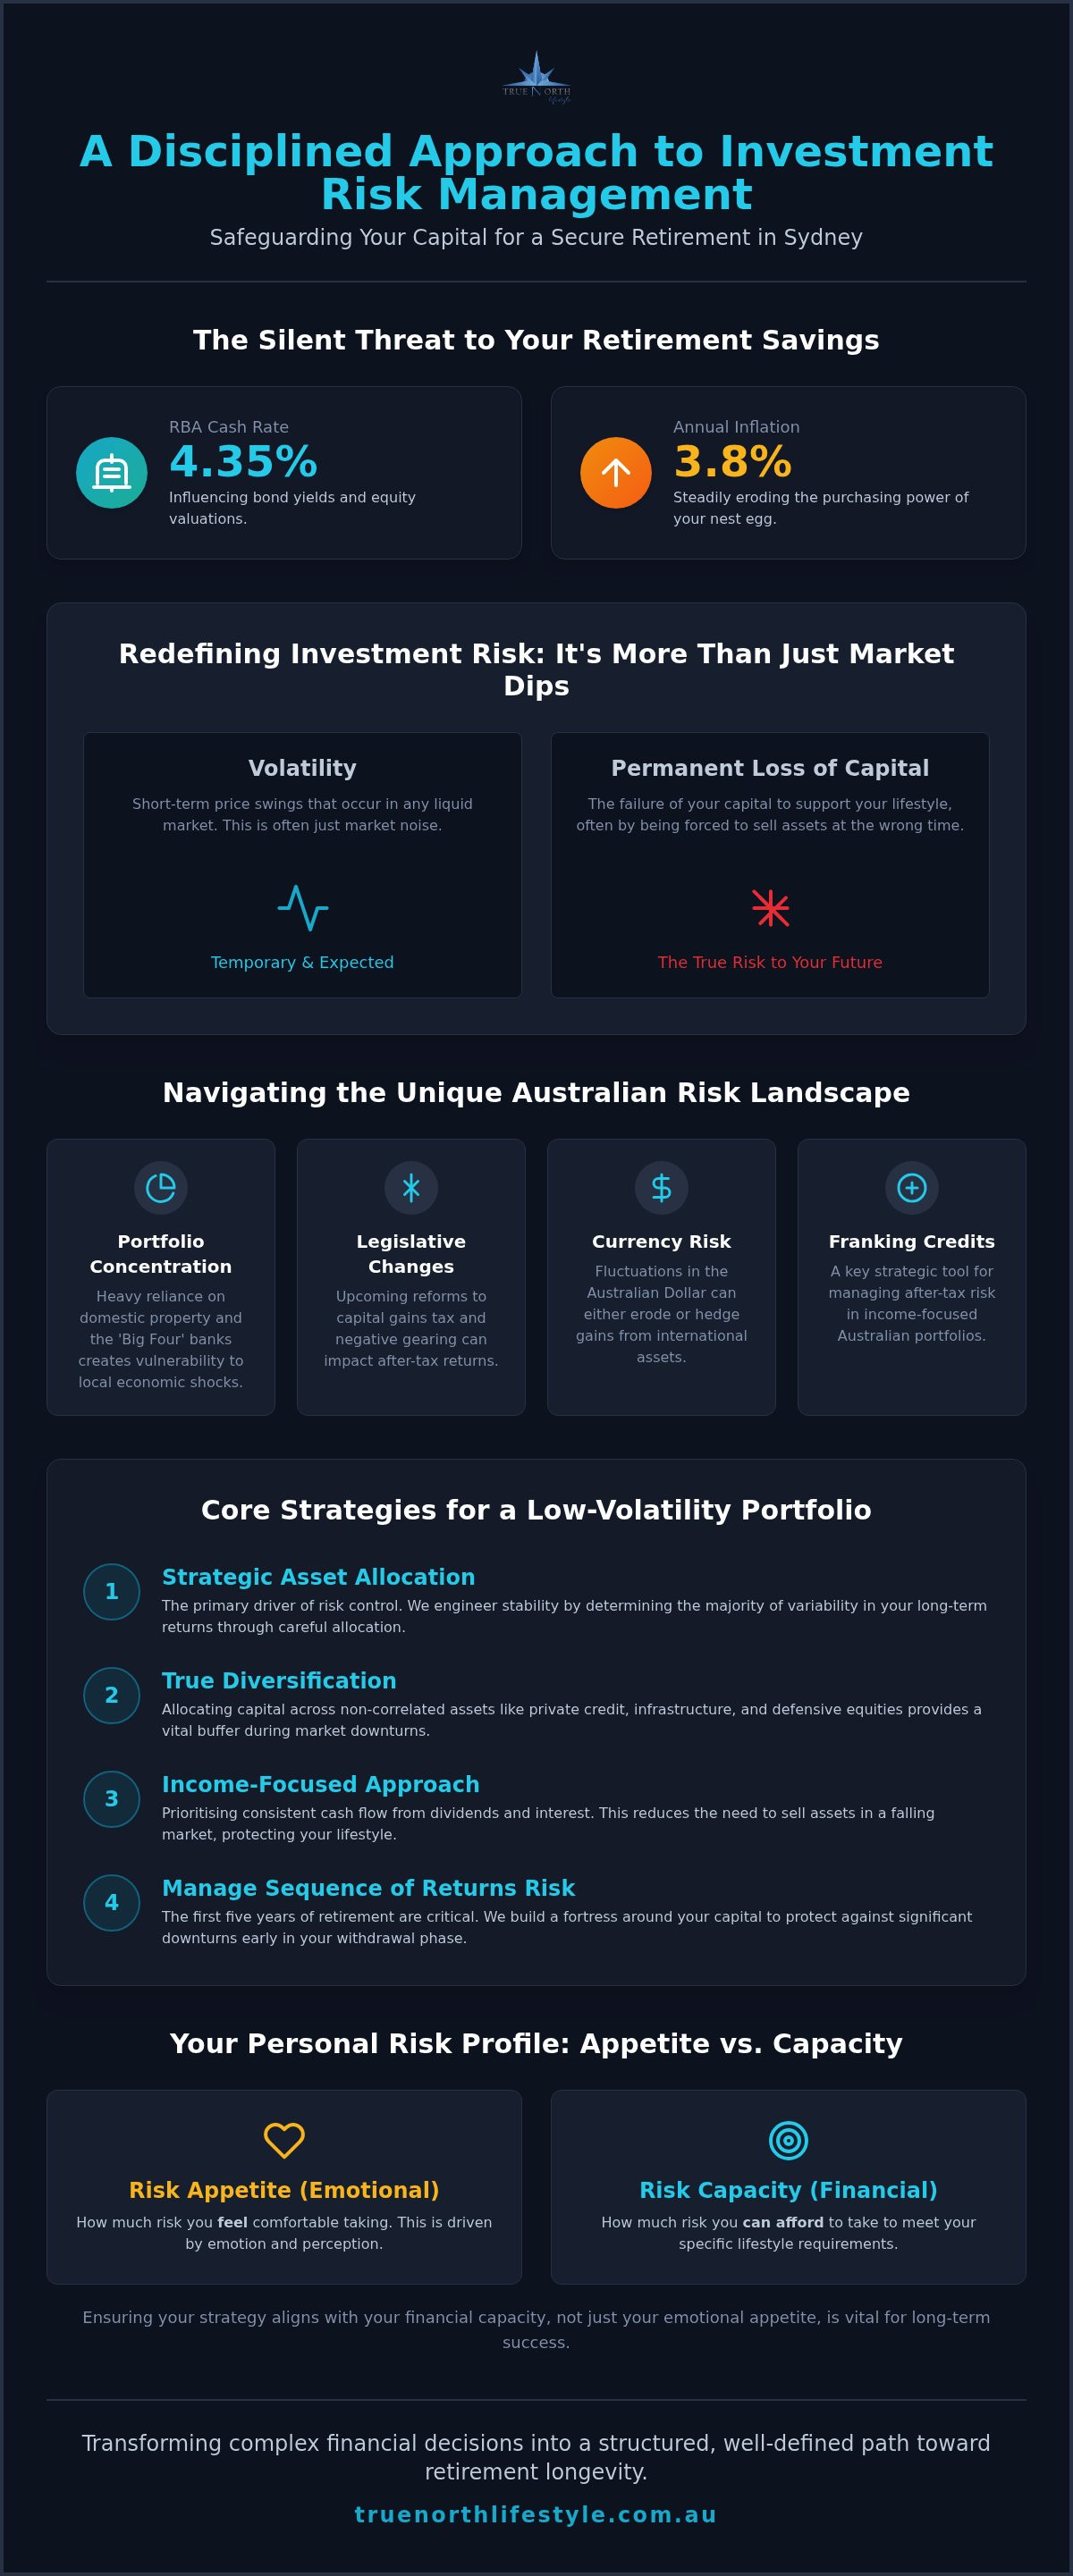
What if the greatest threat to your retirement isn't a sudden market crash, but the slow, silent erosion of your purchasing power? With the RBA holding the cash rate at 4.35% and annual inflation sitting at 3.8%, many Australians feel a persistent sense of unease. You've worked hard to build your nest egg, yet the complexity of modern markets can make your future feel increasingly fragile. Achieving genuine peace of mind requires more than just luck; it demands a disciplined approach to investment risk management Sydney.
Order replaces anxiety. We understand the weight of protecting your legacy against shifting tax landscapes and longevity risks. This article provides a clear roadmap for safeguarding your capital using research-driven Australian strategies. You will discover how to construct a low-volatility portfolio that supports your desired lifestyle while navigating the latest superannuation contribution caps and upcoming capital gains tax reforms. We will explore the methodology used to simplify complex financial decisions, ensuring your wealth remains a source of security rather than a cause for concern.
Key Takeaways
- Learn why effective investment risk management Sydney involves more than just avoiding losses, focusing instead on navigating inflation and shifting Australian legislative landscapes.
- Discover how strategic asset allocation and diversification across non-correlated assets work together to smooth your portfolio's performance during volatile market cycles.
- Identify the vital distinction between your emotional risk appetite and your actual risk capacity to ensure your wealth supports your specific lifestyle requirements in a high-cost environment.
- Master a four-step stress testing process to model historical market events, ensuring you retain the liquidity needed to avoid selling assets at a loss during a downturn.
- Explore how bespoke portfolio construction and professional oversight can transform complex financial decisions into a structured, well-defined path toward retirement longevity.
Defining Investment Risk Management for the Sydney Investor
Risk is often misunderstood as simply "losing money." In a professional context, risk represents the probability that your actual investment return will differ from what you expected. For those seeking investment risk management Sydney, this definition is the starting point for a stable future. True risk isn't just a temporary dip in your portfolio's value; it's the potential for your capital to fail in its primary mission: supporting your lifestyle through retirement. By applying established Financial Risk Management Principles, we can move from a state of reactive anxiety to one of proactive control.
Distinguishing between volatility and the permanent loss of capital is vital. Volatility describes the short-term price swings that occur in any liquid market. These are often noise. Permanent loss, however, occurs when an investment's value is destroyed or when you're forced to sell an asset at the wrong time to meet cash flow needs. Sydney investors face a unique challenge here. Many local portfolios are heavily concentrated in domestic residential property and the "Big Four" banking stocks. While these sectors have historically performed well, this lack of diversification creates a narrow path to success and leaves your wealth vulnerable to specific Australian economic shocks.
The Unique Australian Risk Landscape
Local conditions demand local expertise. The Reserve Bank of Australia (RBA) plays a pivotal role in your portfolio's health; as of August 2026, the cash rate remains at 4.35%, influencing everything from bond yields to equity valuations. Beyond interest rates, we must account for legislative risks, such as the upcoming 2027 reforms to capital gains tax and negative gearing. For the Sydney retiree, managing after-tax risk involves the strategic use of franking credits, which can provide a significant buffer for income-focused portfolios. We also monitor currency risk closely. If a significant portion of your wealth is held in international assets, fluctuations in the Australian Dollar can either erode your gains or provide a necessary hedge during domestic downturns.
Why Institutional Risk Tactics Matter for Private Portfolios
Passive strategies often fail when markets turn. Moving beyond a simple "buy and hold" mentality is essential for wealth preservation. At True North Lifestyle in Miranda, we believe private investors deserve the same level of rigour typically reserved for large institutions. Our approach to investment risk management Sydney involves active oversight and the use of sophisticated modelling to test how your portfolio might behave under various stress scenarios. By maintaining a research-driven Investment Committee and collaborating with Resonant Asset Management, we ensure that every strategic decision is grounded in deep data and real-world probability. This institutional-grade discipline allows you to step into a role of confident oversight, knowing the heavy lifting of risk mitigation is already done.
Core Strategies for Organising a Low-Volatility Portfolio
Stability is engineered. It isn't a byproduct of luck or market timing. Strategic asset allocation serves as the primary driver of risk control, determining the vast majority of the variability in your long-term returns. By prioritising a low-volatility framework, we ensure that your portfolio remains resilient even when the broader market experiences turbulence. This disciplined approach is the cornerstone of effective investment risk management Sydney, moving you away from reactive decision-making toward a state of quiet certainty.
True diversification requires more than just holding different stocks. It involves allocating capital across non-correlated asset classes, such as private credit, infrastructure, and defensive equities. These assets often move independently of the ASX 200, providing a vital buffer during downturns. We also focus on income-focused strategies, where dividends and interest payments provide a consistent cash flow. This reduces the necessity to liquidate assets in a falling market, effectively building a fortress around your lifestyle. While many investors focus on the "upside," we prioritise the structural integrity of the "downside."
Managing Sequence of Returns Risk
Timing is everything. The first five years of your retirement are the most critical period for your capital's longevity. A significant market dip during this window, combined with regular withdrawals, can permanently alter your wealth trajectory and increase the risk of outliving your savings. This is known as sequence of returns risk. To mitigate this, we use tiered cash buckets and liquid reserves to ensure you aren't forced to sell growth assets at the bottom of a cycle. While ASIC Investment Warnings often highlight the dangers of speculative products, the hidden risk of poor withdrawal timing is just as hazardous for retirees.
Bespoke Portfolio Construction
One size fits none. Off-the-shelf portfolios frequently fail because they don't account for your personal longevity requirements or specific tax position. At True North Lifestyle, we specialise in bespoke construction that aligns your risk levels with your broader wealth preservation strategies. We balance the necessity for growth to beat inflation with the absolute requirement for capital stability. This ensures your investment risk management Sydney strategy is as unique as your retirement goals. If you're ready to move toward a more structured path, our team can help you organise a bespoke portfolio review tailored to your lifestyle needs.
Risk vs. Reward: Tailoring Strategies for Sydney Retirees
Clarity brings confidence. Many Sydney residents confuse their emotional tolerance for market swings, known as risk appetite, with their financial ability to withstand a loss, which is their risk capacity. For effective investment risk management Sydney, we must align these two distinct factors. If your lifestyle in the Sutherland Shire requires a specific annual draw to cover high local living costs, your portfolio must be engineered to meet that need without exhausting the principal too early. We move beyond guesswork by using rigorous modelling to determine exactly how much volatility your retirement plan can actually afford.
Living in one of the world's most expensive cities creates a high hurdle for retirement capital. Property maintenance, private healthcare, and leisure costs in Sydney mean your required rate of return is likely higher than a retiree in a regional area. While it's tempting to move everything into "safe" cash when markets wobble, doing so can be the riskiest move of all. If your returns don't outpace the current 3.8% inflation rate, you're effectively losing wealth every single day. Choosing Your Investments wisely involves finding the "sweet spot" where growth assets protect your future purchasing power while defensive holdings secure your immediate needs.
The Inflation Hedge
Purchasing power is the true measure of wealth. Nominal assets, like term deposits or standard bonds, offer a fixed dollar amount but don't account for rising prices. Real assets, such as inflation-linked securities or high-quality equities, are designed to grow alongside the cost of living. Inflation acts as a silent tax that erodes the purchasing power of your retirement capital, potentially halving its real-world value over a twenty-year horizon if not properly hedged. In the 2026 economic environment, maintaining exposure to growth isn't a luxury; it's a fundamental requirement for longevity.
Centrelink and Legislative Risk
Financial security isn't just about market performance. It's about navigating the rules of the game. Changes to Age Pension asset tests or superannuation tax laws can have a "stroke-of-the-pen" impact on your net wealth. We mitigate this through proactive tax planning for retirement Australia, ensuring your structures remain resilient to legislative shifts. Professional oversight ensures you aren't caught off guard by regulatory updates or RBA policy changes, allowing you to focus on the human outcomes of your financial strategy rather than the technical minutiae.
Stress Testing Your Portfolio: A 4-Step Process for Clarity
Testing provides certainty. It's the difference between hoping your strategy works and knowing its breaking point. For high-net-worth individuals, investment risk management Sydney involves a rigorous four-step stress testing process designed to uncover hidden vulnerabilities before they become financial crises. We don't just look at where you are today; we look at how your wealth would behave if history repeated itself or if the economic environment shifted suddenly.
- Scenario Modelling: We run your current asset mix through historical filters, such as the 2008 Global Financial Crisis or the rapid volatility of the 2020 pandemic. This reveals the potential "drawdown" you might experience in a worst-case year.
- Liquidity Assessment: We verify that you have sufficient cash and liquid reserves to fund your lifestyle for at least two to three years. This ensures you aren't forced to sell quality growth assets at a loss during a temporary market dip.
- Concentration Scrutiny: Many Sydney portfolios are over-exposed to domestic banks and residential property. We identify these overlaps to ensure a single sector downturn doesn't derail your entire retirement plan.
- Interest Rate Sensitivity: While the RBA has held the cash rate at 4.35% as of August 2026, we model the impact of a sustained 2% increase. Understanding how your bond and equity valuations would react to higher-for-longer rates is vital for capital preservation.
The Role of Retirement Modelling
Projections build confidence. We use sophisticated retirement modelling to help you visualise your capital trajectory over decades, not just months. This process distinguishes between "average returns" and your actual sequence of returns, which is far more important when you're drawing a pension. By seeing how your wealth remains resilient even in "poor" market cycles, you gain the emotional discipline needed to ignore short-term noise and stay focused on your long-term goals. To see how your current strategy holds up under pressure, you can request a portfolio stress test with our Miranda-based team.
Ongoing Oversight and Rebalancing
Risk is dynamic. It isn't a one-off event you "solve" at a single meeting. Your portfolio requires continuous oversight to ensure it doesn't drift away from your target risk profile as different asset classes grow at different rates. Our Investment Committee monitors global triggers and domestic legislative shifts, providing the professional discipline needed to rebalance your holdings systematically. This methodical approach replaces the anxiety of guesswork with a structured, well-defined path toward financial longevity.
Navigating Uncertainty with True North Lifestyle in Miranda
Confidence requires a partner. At True North Lifestyle, we act as your "Steady Navigator," replacing the inherent anxiety of complex financial decisions with a sense of calm and order. Our philosophy is built on the belief that investment risk management Sydney should be as much about emotional reassurance as it is about technical precision. We've already done the heavy lifting, the rigorous testing, and the detailed modelling so that you don't have to. This allows you to step into a role of confident oversight, knowing your future is anchored in logic rather than luck.
Research drives our methodology. We don't rely on gut feel or market hype. Instead, we collaborate with Resonant Asset Management to access deep research insights and institutional-grade data. This partnership ensures that every bespoke portfolio we construct is grounded in real-world probability and evidence-based strategies. By working with a local bespoke investment advice Sydney specialist, you benefit from a team that truly understands the specific economic pressures and lifestyle expectations of residents in the Sutherland Shire. Professional authority meets empathetic care to ensure your wealth remains a source of security.
Clarity and Confidence in the Sutherland Shire
Order replaces chaos. Our Miranda office serves as a centre for retirement excellence, offering a sanctuary where complex financial problems are simplified. During your initial consultation, we move beyond the numbers to understand the human outcomes you desire. We'll review your current risk profile, identify potential vulnerabilities, and begin the process of moving your wealth from a state of anxiety to a state of quiet certainty. It's about creating a structured path that respects both your capital and your peace of mind.
Your Legacy, Protected
Wealth preservation extends beyond your own lifetime. We integrate investment risk management Sydney with your broader estate planning strategy to ensure that your wealth transfer is as stable and efficient as your retirement income. By managing tax implications and legislative risks today, we protect the legacy you intend to leave for the next generation. We invite you to book a comprehensive review of your current investment risk profile to ensure your portfolio is truly fit for purpose in this volatile market. Taking this first step is the most effective way to secure the lifestyle you've worked so hard to achieve.
Secure Your Financial Horizon
True security isn't found in predicting the next market swing. It's built through the disciplined application of investment risk management Sydney. Throughout this guide, we've explored how moving beyond a simple "buy and hold" mentality toward institutional-grade stress testing and bespoke portfolio construction can replace financial anxiety with quiet certainty. By aligning your risk capacity with the specific lifestyle costs of living in Sydney, you ensure your wealth remains a reliable anchor rather than a source of stress.
Our team brings decades of experience in wealth preservation to every consultation. We rely on research-driven Investment Committee oversight and sophisticated modelling to protect your capital against inflation and legislative shifts. You don't have to navigate these complexities alone. We invite you to Book a Strategic Risk Review with our Miranda team to gain absolute clarity on your current position. Taking this step allows you to move forward with a structured, well-defined path toward a stable retirement. Your legacy deserves the protection of a steady navigator.
Frequently Asked Questions
What is the difference between investment risk and volatility?
Volatility describes the temporary price swings seen in liquid markets. Investment risk, however, is the probability that you won't achieve your financial goals or will suffer a permanent loss of capital. While volatility can be unsettling, it's often just market noise. Genuine risk is the threat that your portfolio will fail to support your lifestyle in the long term. Distinguishing between the two is the first step toward emotional and financial stability.
How does inflation affect my investment risk in Australia?
Inflation acts as a silent tax on your purchasing power. With the annual CPI at 3.8% in August 2026, your investments must return more than this rate just to break even in real terms. If your returns are too low, your capital's real-world value shrinks every year. Managing this risk involves holding "real" assets that grow alongside prices, ensuring your retirement income keeps pace with Sydney's high cost of living.
Can I manage my own investment risk without a professional advisor?
You can manage your own wealth, but professional investment risk management Sydney provides a level of rigour that's difficult to replicate at home. We use institutional-grade modelling and research-driven oversight to identify vulnerabilities you might miss. Most self-managed investors struggle with emotional biases during market dips. Professional guidance replaces that anxiety with a structured process, ensuring your strategy remains logical and evidence-based regardless of the current market headlines.
What is sequence of returns risk and why does it matter for retirees?
Sequence of returns risk refers to the timing of market downturns. If a crash occurs in the first few years of your retirement while you're withdrawing funds, it can permanently deplete your capital base. This is far more damaging than a downturn occurring before you retire. Protecting your "pension pot" from this risk requires specific cash-bucket strategies and liquidity modelling to ensure you aren't forced to sell assets at a loss.
How often should I stress test my investment portfolio?
We recommend a comprehensive stress test at least once a year. Your portfolio's asset allocation naturally drifts as different markets grow at different rates, which can silently increase your risk level. You should also re-test your strategy whenever the RBA changes the cash rate significantly or if your personal lifestyle goals evolve. Regular oversight ensures your wealth preservation strategy remains aligned with the current economic reality and your long-term requirements.
Does a low-risk portfolio mean I will get lower returns?
A low-volatility portfolio focuses on capital preservation rather than aggressive growth. While you might sacrifice some "upside" during a bull market, you're better protected during a downturn. The goal is to achieve the highest possible return for the level of risk you're willing to take. For retirees, a stable, consistent return is often more valuable than a high, erratic one that causes sleepless nights and threatens your income security.
How do Sydney property prices impact my overall investment risk profile?
High Sydney property values often lead to "concentration risk" in local portfolios. If too much of your wealth is tied up in your home or investment units, you're vulnerable to a property market correction or interest rate shocks. Effective investment risk management Sydney involves diversifying away from this domestic bias. We look at your total net wealth to ensure you have sufficient exposure to liquid, non-property assets that can fund your retirement.
What role does diversification play in managing risk in 2026?
Diversification is your primary defence against uncertainty. In 2026, this means moving beyond a basic 60/40 stock and bond split. We look for non-correlated assets, such as private credit and infrastructure, which don't move in lockstep with the ASX 200. This structural diversity smooths your portfolio's performance, ensuring that a downturn in one specific sector or asset class doesn't have a catastrophic impact on your overall financial security and lifestyle.


