

A simple Will is often the most expensive document an Australian family ever inherits. Without a structured financial strategy, significant wealth frequently leaks away through avoidable taxes and administrative friction, leaving beneficiaries with far less than intended. Integrating estate planning with retirement planning Australia is the critical step that moves you beyond basic legal deeds and into a state of genuine financial security. You likely feel a deep responsibility to protect what you've built, yet the complexity of superannuation laws and shifting tax thresholds can make the path forward feel obscured.
We understand this uncertainty. Our approach seeks to replace that anxiety with a sense of calm and order. By aligning your long-term retirement modelling with a bespoke estate strategy, you'll ensure your partner is supported for life while minimising the tax burden for your children and grandchildren. This guide provides the clarity you need to harmonise these two pillars, preventing wealth leakage and ensuring a seamless, protected transition of your legacy.
Key Takeaways
- Beyond the simple Will. Most significant assets, such as superannuation and family trusts, don't automatically form part of your estate and require a coordinated strategy to ensure they reach the intended beneficiaries.
- Strategic alignment. Integrating estate planning with retirement planning Australia allows you to harmonise your lifestyle goals with your legacy, preventing wealth leakage and ensuring your financial architecture is resilient.
- The tax trap. Non-dependant beneficiaries may face up to 17% tax on superannuation death benefits, making tax-minimisation strategies an essential component of your long-term wealth preservation.
- Structured auditing. A thorough audit of both estate and non-estate assets provides the clarity needed to protect your partner for life and simplify the eventual transition of assets to the next generation.
- Bespoke modelling. Evidence-based retirement modelling and professional portfolio construction replace uncertainty with order, giving you the confidence that your legacy is managed with disciplined, research-driven oversight.
Beyond the Will: Why Integration is Key to Legacy Protection
A Will is a starting point, not a solution. Effective estate planning strategy is a multi-disciplinary architecture that brings together legal structures, financial modelling, and tax optimisation to protect your family's future. While many people view it as a one-off legal task, the reality of what is estate planning in a modern context is far more dynamic. It involves ensuring that every asset you've accumulated, from your family home to your investment portfolio, is aligned with your long-term vision. Integrating estate planning with retirement planning Australia allows you to move from a state of lingering anxiety about the "what ifs" to a position of quiet certainty. A strategic estate plan acts as a financial roadmap, ensuring your wealth reaches the right hands with minimal friction.
The High Cost of No Strategy: Wealth Leakage and Disputes
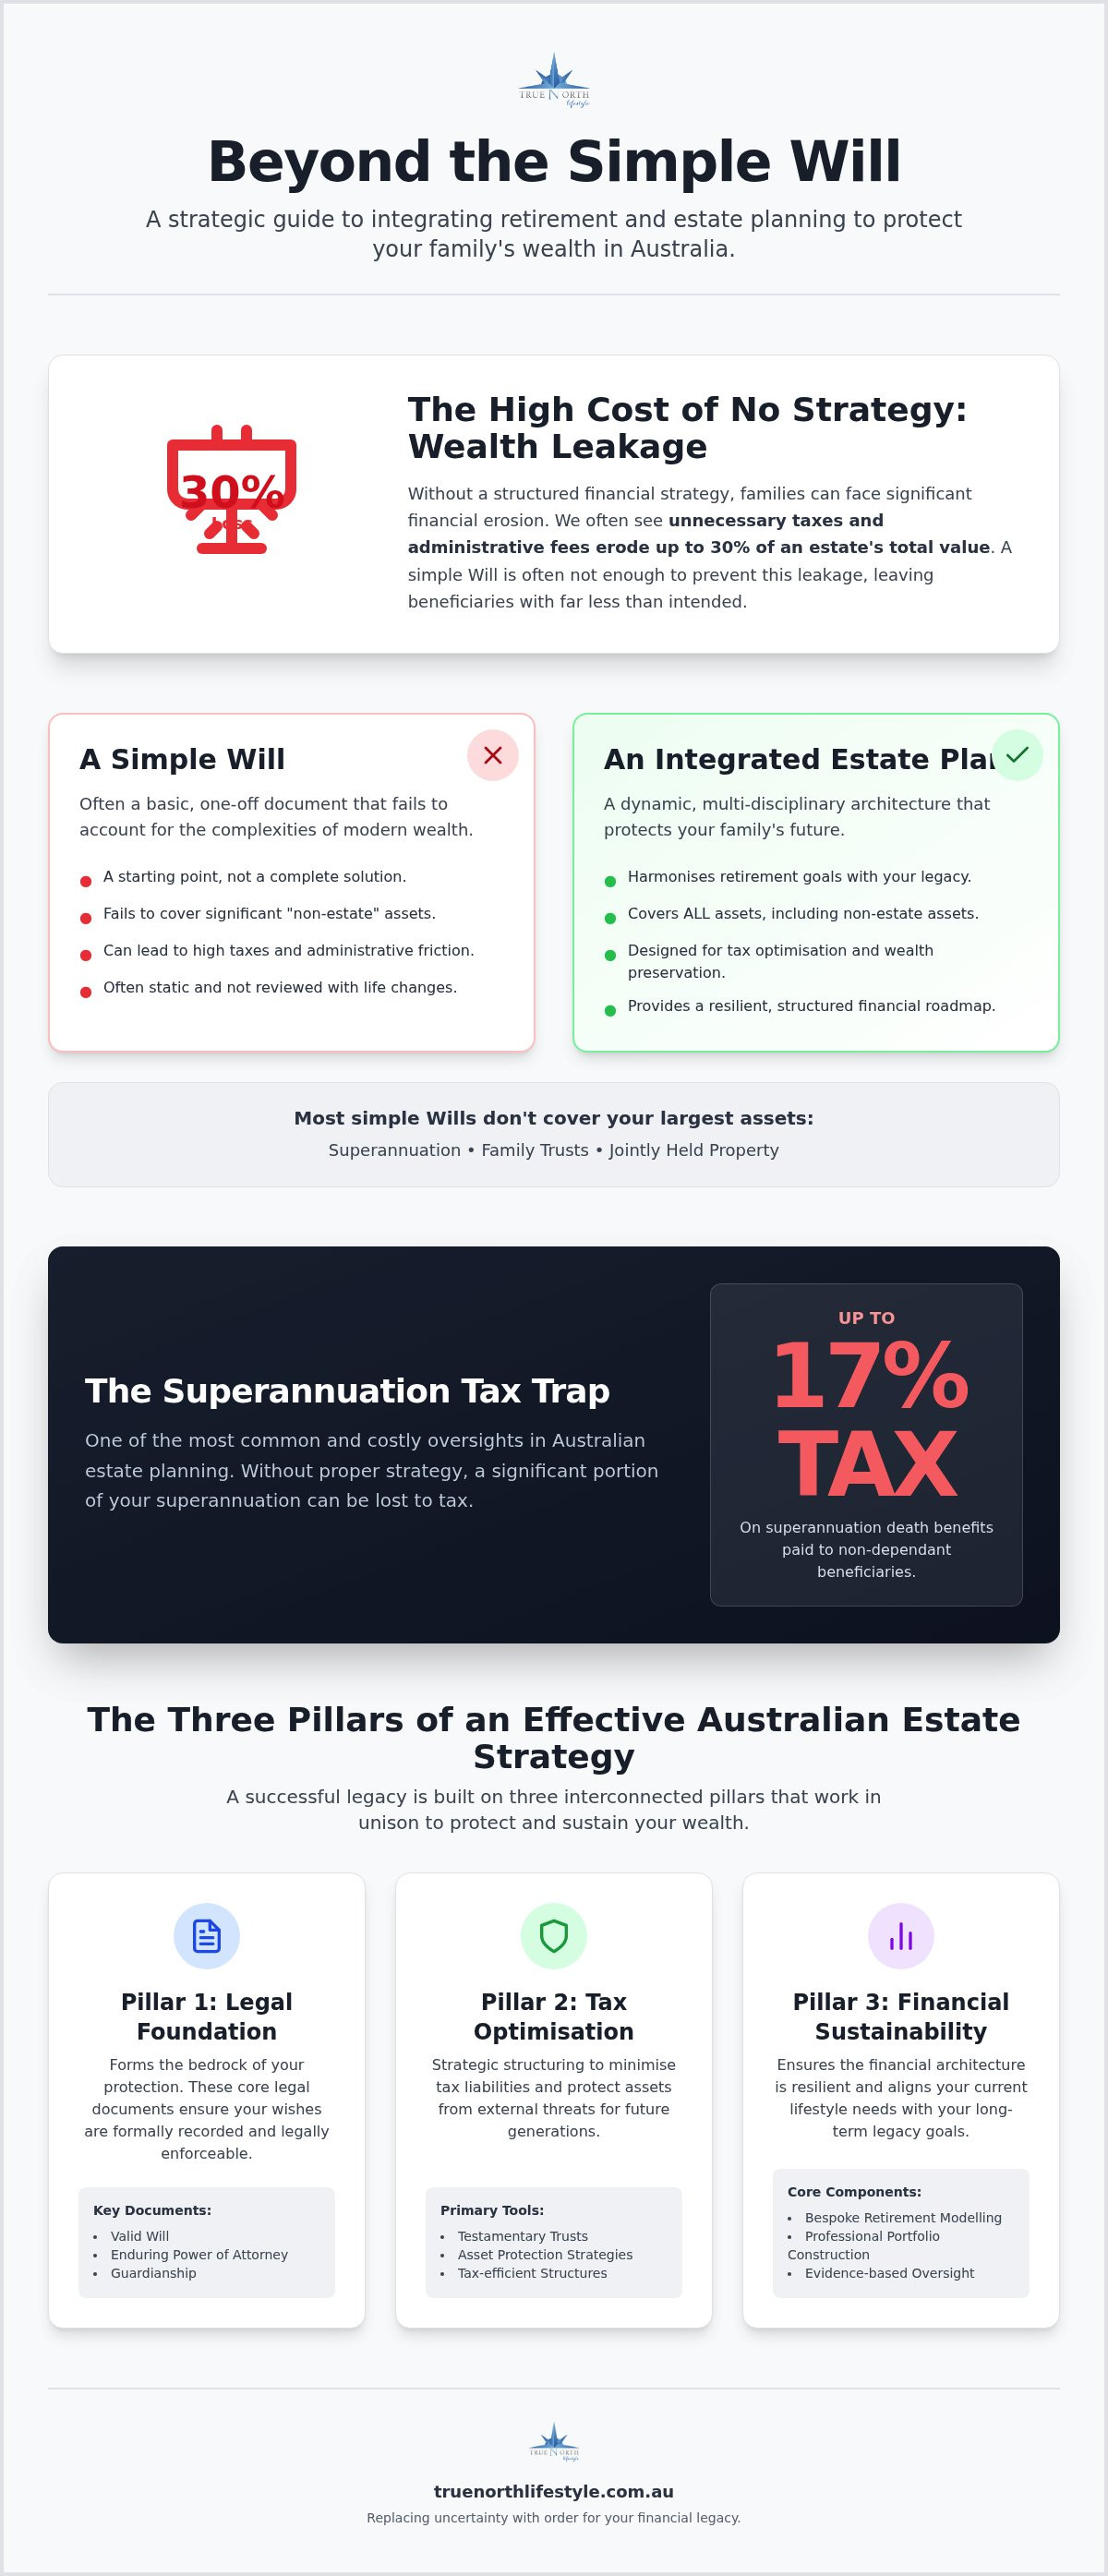
Wealth disappears quickly. When a strategy is absent or poorly constructed, families often face the dual burden of emotional distress and financial erosion. Disputes over inheritance don't just damage relationships; they can lead to protracted legal battles that consume the very assets intended for the next generation. We often see wealth leakage where unnecessary taxes and administrative fees erode up to 30% of an estate's total value. This is why robust wealth preservation strategies are indispensable. By identifying these risks early, you can structure your affairs to keep more of your hard-earned capital within the family circle.
Estate Planning vs. Simple Wills
Precision matters here. A standard, "off-the-shelf" Will is often a checkbox exercise that fails to account for the complexities of the Australian financial system. Many of your most valuable assets actually fall outside the scope of a traditional Will. Jointly held property, assets within family trusts, and your superannuation balance are considered non-estate assets. They require specific, separate directions to ensure they are distributed according to your wishes.
Success depends on integrating estate planning with retirement planning Australia to create a unified front. Instead of treating your retirement income and your legacy as separate silos, we model how they interact over decades. This bespoke approach ensures that as you draw down on your wealth for lifestyle needs, you're doing so in a way that remains tax-efficient for your eventual beneficiaries. Professional advice is the anchor here, coordinating these disparate elements into a single, cohesive plan that provides lasting stability.
The Three Pillars of an Effective Australian Estate Strategy
Stability requires structure. We view a successful legacy through three distinct but interconnected lenses: Legal Foundation, Tax Optimisation, and Financial Sustainability. Integrating estate planning with retirement planning Australia ensures these pillars don't operate in isolation. When they work in unison, they protect your wealth from erosion while providing a clear path for your family. This research-driven methodology moves you away from guesswork and into a position of confident oversight. It's about building a financial architecture that stands firm across generations.
Pillar 1: The Legal Foundation (Wills and Powers of Attorney)
Logic dictates the start. A valid Will, Enduring Power of Attorney, and Guardianship form the bedrock of your protection. These documents aren't static. They require regular review as life evolves, whether through divorce, the arrival of new grandchildren, or changes in legislation. While True North focuses on the overarching strategy and asset alignment, we work alongside your legal partners who handle the formal drafting of deeds. This ensures the "how" of your distribution matches the "what" of your financial reality. Without this legal scaffolding, even the best financial plan can be undermined by administrative delays or challenges.
Pillar 2: Tax Minimisation and Asset Protection
Protect what's yours. Testamentary Trusts are primary tools here, offering a layer of protection for beneficiaries against creditors or relationship breakdowns. By utilising tax planning for retirement Australia, you can significantly reduce the tax burden inherited by your heirs. Intergenerational wealth transfer should feel calm and orderly, not like a chaotic tax event. We structure your assets to ensure the transition to the next generation is as seamless as possible, using proven strategies to keep capital within the family circle rather than losing it to unnecessary leakage.
Pillar 3: Financial Modelling and Longevity
Balance is essential. Retirement modelling ensures you don't inadvertently compromise your own lifestyle by gifting too much too early. We manage longevity risk by stress-testing your portfolio against inflation and market volatility. This is where bespoke investment advice Sydney becomes vital. It provides the empirical data needed to ensure your estate remains viable for the next generation without leaving you short. Our investment committee focuses on building portfolios designed for stability, providing the income you need today while preserving the capital you wish to leave behind.
If you're ready to see how these pillars fit together for your specific situation, you can explore our strategic approach to legacy modelling and portfolio sustainability.
Superannuation and Death Benefits: The Silent Tax Trap
Superannuation is a distinct entity. It's a common misconception that your super balance is governed by your Will. In reality, your super exists in a separate legal structure; without specific intervention, it may not reach your intended heirs in the way you expect. Integrating estate planning with retirement planning Australia is essential to avoid the "silent tax trap" that often catches families off guard. For non-tax dependants, such as adult children who are no longer financially reliant on you, the taxable component of a superannuation death benefit is subject to a 15% tax plus the 2% Medicare levy. This 17% erosion of wealth can be a significant blow to a legacy if not managed proactively through a research-driven strategy.
Binding vs. Non-Binding Death Benefit Nominations
Clarity requires commitment. A non-binding nomination acts merely as a suggestion to the super fund's trustee, who ultimately retains discretion over who receives your balance. This leaves the door open for potential family disputes or distributions that contradict your actual wishes. Conversely, a binding nomination compels the trustee to follow your instructions exactly, provided the nomination is valid and current. This alignment is a cornerstone of your broader estate strategy. A Binding Death Benefit Nomination is the only way to ensure your superannuation follows your exact instructions. By securing this legal link, you replace the risk of trustee discretion with the quiet certainty of a defined outcome.
The Re-contribution Strategy: Reducing Beneficiary Tax
Strategy creates efficiency. One of the most effective wealth transfer strategies Australia offers is the re-contribution strategy. This involves withdrawing a portion of your superannuation, once you've met a condition of release, and re-contributing it as a non-concessional contribution. This process effectively converts the "taxable" portion of your balance into a "tax-free" component. For individuals aged between 60 and 75, this can save tens of thousands of dollars in death benefits tax for their adult children. It's a methodical way to optimise your balance while you're still in the retirement phase, ensuring more of your hard-earned wealth remains with your family.
Managing these technical nuances is part of the "heavy lifting" we do for our clients. If you're looking for superannuation advice Sutherland Shire families can trust, our team can help you audit your nominations and model the impact of tax-minimisation strategies. Integrating estate planning with retirement planning Australia ensures that your superannuation remains a tool for family prosperity rather than a source of unexpected tax liabilities.
Coordinating Your Strategy: A Roadmap for Sydney Families
Order begins with visibility. For families across the Sutherland Shire and Sydney CBD, the path to a protected legacy follows a logical, evidence-based progression. Integrating estate planning with retirement planning Australia isn't a single event; it's a methodical process of alignment. We recommend a four-step roadmap to move from uncertainty to structure. This disciplined approach ensures that your financial architecture is built on facts rather than assumptions.
- Step 1: Audit all assets. This includes estate assets like personal bank accounts and non-estate assets such as Sydney investment properties held in trusts or your SMSF balance.
- Step 2: Identify beneficiaries. Beyond naming names, consider their specific circumstances. For example, establishing a Special Disability Trust may be necessary to provide for a family member with high support needs.
- Step 3: Consult a strategic financial adviser. Use retirement modelling to project how your spending today impacts the legacy you leave in twenty years.
- Step 4: Brief a solicitor. Once the financial strategy is stress-tested, provide your legal partner with a clear brief to draft the necessary instruments based on the financial modelling.
The Role of the Modern Financial Adviser in Estate Planning
We act as the Authoritative Guide. While a solicitor drafts the deeds and an accountant manages the tax returns, the financial adviser coordinates the entire architecture. This central oversight ensures that no detail is lost between disciplines. Face-to-face consultations in our Miranda or Sydney CBD offices allow for nuanced, intergenerational discussions that simply cannot be replicated over a screen. We manage the heavy lifting of research and modelling, allowing you to focus on the emotional outcomes of your decisions. Our role is to provide the quiet certainty that your partner is looked after for life and your children are protected from avoidable friction.
Reviewing Your Strategy: When to Pivot
Discipline requires vigilance. A strategy that worked five years ago may now be obsolete due to life events or legislative shifts. You should trigger a review during significant milestones: the birth of a grandchild, a marriage, or substantial growth in your asset base. Legislative changes also demand a proactive response. For instance, the Division 296 tax, which applies a 15% tax on earnings for superannuation balances over $3 million, has fundamentally altered the landscape for high-net-worth individuals. Staying ahead of these changes ensures your financial order is never compromised by external volatility. If you're ready to begin this process, you can book a strategic consultation to audit your current position and start your legacy roadmap.
The True North Approach: Bespoke Legacy Modelling
True North Lifestyle acts as the Steady Navigator for your financial journey. We understand that the transition from wealth accumulation to legacy preservation is often fraught with complexity and emotional weight. Our role is to absorb that complexity through rigorous research and bespoke legacy modelling. By integrating estate planning with retirement planning Australia, we ensure your lifestyle today doesn't come at the expense of your family's future. We handle the technical projections and scenario-based thinking, allowing you to step into a role of confident oversight. Our approach replaces the inherent anxiety of estate decisions with a sense of calm and order, providing directness and honesty instead of corporate jargon.
Research-Driven Portfolios for Wealth Preservation
Stability is our priority. Our internal Investment Committee constructs portfolios with a disciplined focus on low volatility and consistent income generation. This isn't about chasing speculative gains; it's about strategic wealth preservation. Through retirement planning Sydney families can rely on, we balance your daily cash flow needs with the long-term objective of protecting capital for your heirs. This evidence-based process ensures the wealth you've built remains shielded from market turbulence, providing a reliable anchor in a fluctuating environment. We've already done the heavy lifting and the rigorous testing, so you can focus on the human outcomes of your strategy rather than the numbers.
Achieving Clarity and Confidence in Your Future
The ultimate outcome is peace of mind. A calm, orderly transition of wealth is only possible when every variable has been accounted for and stress-tested against real-world probabilities. Professional oversight means you don't have to worry about the shifting sands of tax legislation or market volatility. You can enjoy your retirement today, knowing your financial architecture is built to last. Integrating estate planning with retirement planning Australia is the final piece of your retirement modelling puzzle, ensuring your financial story concludes exactly as you intended.
Our methodology moves you away from the anxiety of the unknown toward a structured, well-defined path. We value trust and proven outcomes over flashy innovation, positioning ourselves as your long-term partner in wealth preservation. If you're ready to secure your legacy with quiet certainty, we invite you to book a consultation at our Miranda or Sydney CBD offices to begin your bespoke modelling process and gain the clarity you deserve.
Defining Your Legacy with Quiet Certainty
A legacy isn't built on legal documents alone; it's sustained through disciplined financial oversight. By integrating estate planning with retirement planning Australia, you ensure that your hard-earned assets are protected from unnecessary tax leakage and family friction. You've seen that a standard Will often leaves significant gaps, particularly regarding superannuation death benefits and the potential 17% tax on non-dependant beneficiaries. Our team of Miranda-based advisers is here to do the heavy lifting for you, utilising specialist retirement modelling and long-term projections to build a stable future for your loved ones.
This strategic alignment provides the reassurance that your partner is supported for life and your children's inheritance is preserved. It's about moving from a state of uncertainty to a position of confident oversight through our research-driven investment committee approach. Secure your legacy today with a bespoke estate planning strategy from True North Lifestyle. Your future deserves the clarity and order that only professional, evidence-based planning can provide.
Frequently Asked Questions
What is the difference between a Will and an estate plan in Australia?
A Will is a specific legal document, whereas an estate plan is a comprehensive financial architecture. While a Will dictates the distribution of estate assets, it cannot control non-estate assets like superannuation or family trusts. Integrating estate planning with retirement planning Australia ensures every asset is aligned with your lifestyle needs and legacy goals. This strategic approach replaces the anxiety of a simple checkbox exercise with the quiet certainty of a structured, multi-disciplinary roadmap.
Is superannuation part of my estate when I die?
No, superannuation is held in a trust and does not automatically form part of your deceased estate. Its distribution is governed by the fund's trust deed and any nominations you've made. To ensure your super reaches your intended beneficiaries, you must have a valid Binding Death Benefit Nomination. Without this, the trustee has the discretion to decide who receives your balance, which can lead to unintended tax consequences or family disputes.
How can I minimise the tax my children pay on their inheritance?
Tax-minimisation for beneficiaries often focuses on the taxable component of your superannuation. Adult children who aren't financial dependants currently face a 17% tax rate on this component. Strategies like the re-contribution method can convert these taxable amounts into tax-free components during your lifetime. Additionally, using testamentary trusts in your Will allows for more flexible, tax-effective income distribution to grandchildren, significantly reducing the overall tax burden on your family's future wealth.
What is a testamentary trust and do I need one?
A testamentary trust is a trust established within your Will that only becomes active upon your death. It acts as a protective shield for your assets, safeguarding them from a beneficiary's potential creditors or relationship breakdowns. It also offers significant tax advantages, particularly when distributing income to minor beneficiaries. While not every estate requires one, it's a sophisticated tool for families seeking long-term wealth preservation and robust intergenerational tax governance.
How often should I review my estate planning strategy?
You should review your strategy every three to five years or whenever a significant life event occurs. Milestones such as marriage, divorce, the birth of a grandchild, or receiving a substantial inheritance necessitate an audit. Legislative shifts, like the 2025 Division 296 tax on super balances over $3 million, also require a proactive stance. Regular reviews ensure your financial order is maintained and that your legacy remains resilient against external market or regulatory changes.
What happens if I die without a valid Will in NSW?
If you die without a valid Will in New South Wales, your assets are distributed according to the rigid formula of the Succession Act 2006. This intestacy process often fails to reflect your actual wishes and can lead to significant administrative delays and legal costs. It leaves the distribution of your life's work to a generic legal template, potentially leaving your partner or children in a complex and stressful financial position during an already difficult time.
Can my estate plan be challenged by family members?
Yes, in Australia, certain eligible persons can challenge an estate through a family provision claim if they believe they haven't been adequately provided for. While no plan is entirely immune, a strategic approach significantly reduces the risk. By documenting the reasoning behind your distributions and ensuring your retirement modelling supports your choices, you create a defensible position. Professional oversight brings a level of discipline that helps minimise the likelihood of protracted and expensive family disputes.
Do I need a solicitor or a financial planner for estate planning?
Both professionals play essential, distinct roles in a successful strategy. A financial planner acts as the Authoritative Guide, providing the strategic modelling, tax-minimisation logic, and asset alignment. They do the heavy lifting of research and projections. A solicitor then uses this strategic brief to draft the formal legal deeds. Integrating estate planning with retirement planning Australia requires this collaborative effort to ensure your financial reality and your legal intentions are perfectly harmonised.


