

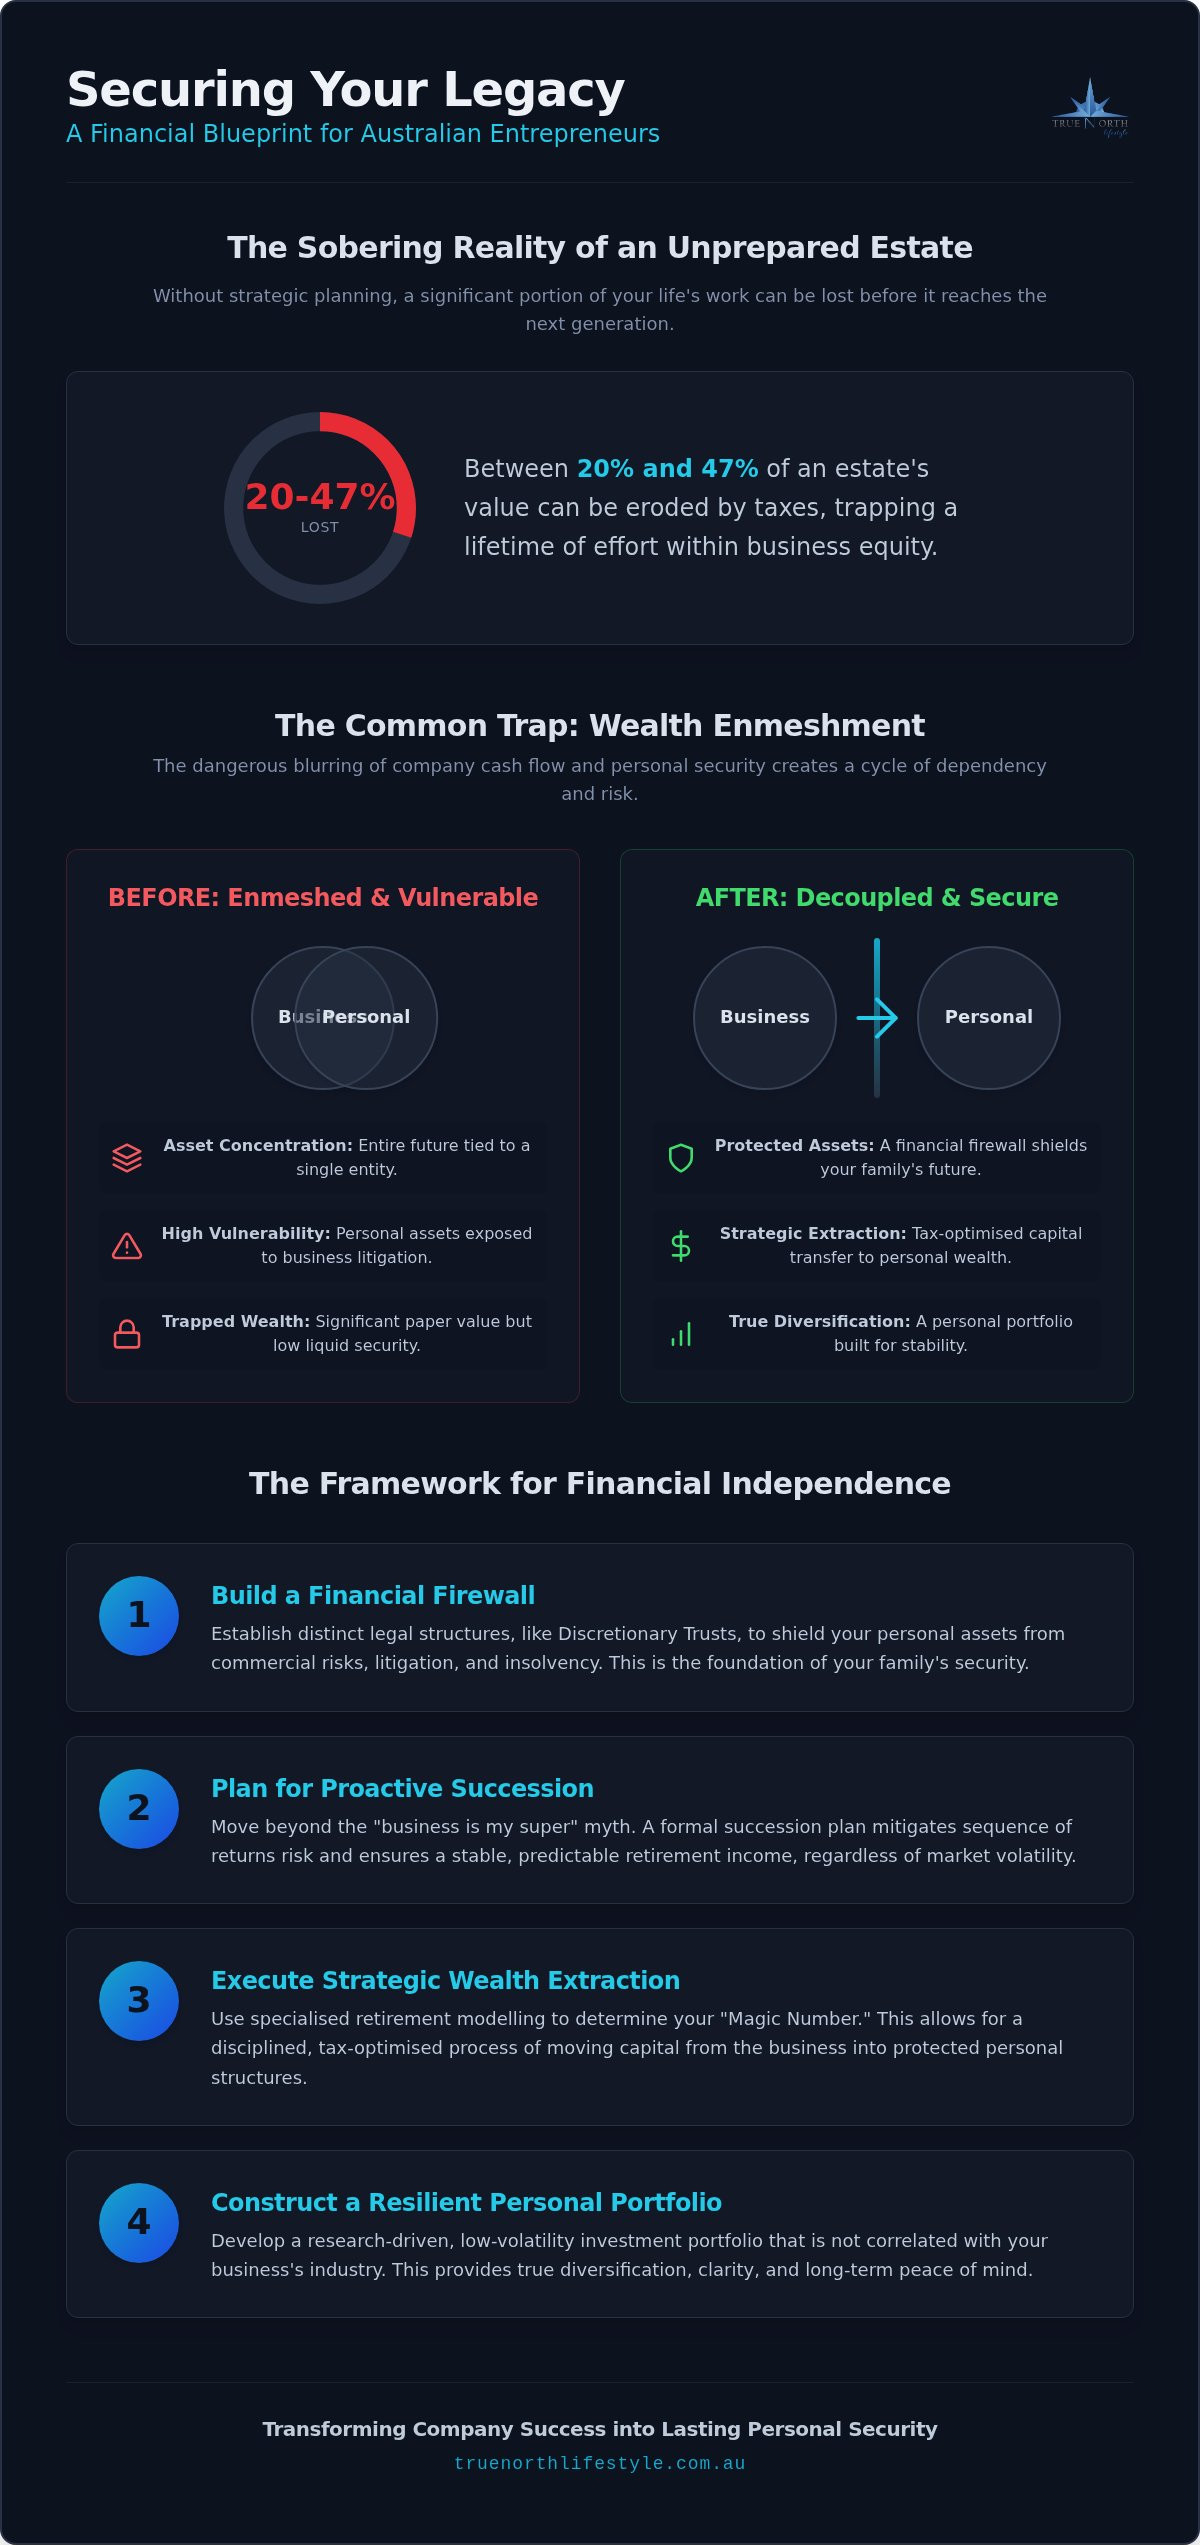
Between 20% and 47% of an unprepared estate can be eroded by taxes before wealth is successfully transferred to the next generation. For many Sydney entrepreneurs, this is a sobering reality where a lifetime of effort remains trapped within business equity, vulnerable to market shifts. You've likely felt the pressure of high personal tax bills and a persistent lack of time to manage your own investments while steering your company. It's a common paradox of success; the business that provides your lifestyle often represents your greatest financial risk.
This guide provides a structured path to decouple your personal future from your business operations. You'll discover how to implement the robust business succession planning Australia demands in 2026, focusing on tax-optimised wealth extraction and the clear separation of personal and commercial assets. We will examine how bespoke portfolio construction and strategic retirement modelling can provide the confidence to retire on your own terms, regardless of the external environment. By moving from uncertainty toward a well-defined legacy, you can finally transform company success into lasting personal security.
Key Takeaways
- Identify why coordinating personal and corporate assets is vital to avoiding the common trap where business success fails to translate into personal wealth.
- Learn how to construct a financial firewall using distinct legal structures to shield your family's future from commercial litigation and operational risks.
- Discover why proactive business succession planning Australia wide is essential to mitigate sequence of returns risk and ensure a stable retirement income.
- Understand the role of specialised retirement modelling in determining your "Magic Number" for tax-optimised wealth extraction from your company.
- Explore how a research-driven, low-volatility investment approach can provide Sydney business owners with the clarity and peace of mind they deserve.
Beyond the Balance Sheet: Why Business Owners Neglect Personal Wealth
Success can be deceptive. For many Sydney entrepreneurs, the very drive that builds a thriving company often leaves their personal financial life in a state of quiet disarray. True wealth management for a business owner isn't just about reading a profit and loss statement; it's the sophisticated coordination of personal and corporate assets to ensure they work in harmony rather than competition. Too often, we see the Shoemaker’s Boots syndrome in action. High-performing CEOs spend their days optimising client outcomes while their own personal portfolios remain stagnant, under-diversified, or entirely forgotten.
The core risk here is asset concentration. When your salary, your superannuation, and your eventual retirement capital are all tied to the same operational entity, you aren't just invested in a business; you're betting your entire future on a single market variable. Effective Succession planning requires a fundamental shift in perspective. It's about recognising that while the business is a vehicle for wealth creation, it shouldn't be the only warehouse for it. Without a Steady Navigator to guide this transition, owners often find themselves with significant paper wealth but very little liquid security.
The Emotional Burden of Business Enmeshment
Business stress rarely stays at the office. It permeates personal decision-making, often skewing a founder's risk appetite or causing them to delay essential personal investments. There's a persistent anxiety that stems from not knowing your true net worth outside of subjective company valuations. Wealth enmeshment is the dangerous blurring of company cash flow and personal security. This lack of clarity makes it difficult to plan for a future that exists independently of the company's daily performance, creating a cycle of dependency that is hard to break without external structure.
Moving from Business Growth to Wealth Preservation
Growth is an addictive metric, but there comes a point where the focus must shift toward preservation. This doesn't mean the business stops expanding; it means the owner begins a disciplined process of strategic capital extraction. With 2026 market volatility presenting new challenges, Sydney business owners need a more conservative personal buffer that sits entirely outside their commercial interests. Utilising bespoke investment advice Sydney allows for the construction of a portfolio that isn't correlated to your industry's specific risks. By implementing business succession planning Australia wide, you move from being a passenger to a pilot of your own long-term stability.
Building the Wall: Separating Business Assets from Personal Security
Structure creates safety. When you lead a business in Australia, your personal assets shouldn't be the collateral for your commercial risks. Establishing distinct legal and financial entities is the only way to build a genuine firewall against litigation or insolvency. This isn't just about paperwork; it's about ensuring that a single bad year or a legal dispute doesn't dismantle your family's future. Effective business succession planning Australia involves a coordinated effort between your financial advisor, accountant, and solicitor to ensure there are no cracks in your defensive wall.
Without this separation, your wealth is essentially a single-point failure. If the business faces a claim, every asset you've worked for could be vulnerable. To prevent this, we focus on moving capital from "at-risk" environments into protected structures. If you're unsure if your current setup is truly secure, a bespoke financial review can provide the clarity you need to move forward with confidence.
Asset Protection and Structural Integrity
Discretionary trusts are a cornerstone of this defence. They offer the flexibility to distribute income tax-effectively while keeping assets out of the direct line of fire. One of the most significant risks we see for Sydney entrepreneurs is the overuse of personal guarantees. These often bypass your corporate structure, exposing your family home to business creditors. Implementing robust wealth preservation strategies can help you identify these vulnerabilities before they become liabilities. Common weaknesses often include:
- Holding high-value personal assets in the same entity that employs staff or signs contracts.
- Failing to register security interests over money lent to the business from personal entities.
- Neglecting to review trust deeds to ensure they allow for modern intergenerational wealth transfer.
The Role of Superannuation in 2026
Superannuation remains the most tax-effective environment for wealth accumulation in Australia. As of the 2026-27 financial year, the Superannuation Guarantee (SG) rate is 12.0%. For owners, this isn't just a compliance cost; it's a strategic tool for capital extraction. By optimising contributions for yourself and your spouse, you can lower your personal and business tax burdens simultaneously. Seeking superannuation advice Sutherland Shire helps you navigate complex rules like the Division 296 tax, which adds a 15% tax on earnings for balances over $3 million. Strategic concessional contributions can help you stay below these thresholds while building a liquid retirement fund that is entirely independent of your company's balance sheet.
The Business is My Super Myth: Risks and Realities
The belief that a business sale will effortlessly fund a thirty-year retirement is one of the most pervasive myths in the Australian commercial landscape. Relying solely on this outcome is a high-risk strategy that ignores the unpredictable nature of market cycles. Sequence of returns risk is particularly brutal for business owners. If the economy dips exactly when you planned to exit, your valuation could plummet, forcing you to either delay retirement or accept a significantly lower lifestyle. This vulnerability highlights why business succession planning Australia wide must include a strategy for wealth that exists entirely outside your company's walls.
Equity is not cash. While your balance sheet might show millions in value, that wealth is functionally trapped until a transaction occurs. The illiquidity trap is the state of being paper rich but cash poor during a market downturn. Without liquid assets, you lack the agility to navigate personal financial needs or capitalise on new opportunities without putting further strain on the business operations. True security requires a transition from being "business-heavy" to having a diversified base of liquid capital.
The Valuation Gap: Expected vs Realised Sale Price
Internal expectations rarely align with market reality. Many business owners overvalue their companies by up to 50% because they factor in years of "sweat equity" that a buyer simply won't pay for. A major driver of this gap is key person dependency. If the business relies on your personal relationships or technical expertise to function, its value to an external party drops sharply. Effective business succession planning Australia focuses on making the business "sale-ready" by reducing this dependency, yet even then, a sale remains a single point of failure if it's your only retirement plan.
Diversifying with Bespoke Portfolios
True security comes from assets that don't move in lockstep with your specific industry. If you own a construction firm, your personal wealth shouldn't be heavily tied to property development; if you run a retail empire, you need stability elsewhere. We focus on building bespoke portfolios that prioritise low-volatility, income-producing assets. This creates a reliable stream of capital to replace your salary post-exit. By stress testing your personal wealth against a potential industry disruption or business failure, you ensure that your family's lifestyle remains protected. This methodical approach replaces the anxiety of a "big sale" with the quiet certainty of a structured, evidence-based investment path.
Strategic Wealth Extraction: Tax-Effective Models for Sydney Entrepreneurs
Extraction requires precision. For Sydney entrepreneurs, the transition from active salary to passive retirement income is often the most complex phase of their financial life. It isn't simply about selling; it's about determining your "Magic Number"-the exact amount of capital required to sustain your lifestyle independently. In the 2026 tax environment, this involves navigating shifted income tax brackets and the updated small business CGT concessions, where the aggregated turnover threshold for the 50% active asset reduction has increased to A$10 million. Effective business succession planning Australia wide must account for these thresholds to ensure you aren't overpaying during your exit.
Managing large capital gains after a business sale is a delicate balancing act. With the 2026-27 financial year bringing a reduction in personal tax rates, the timing of your extraction can significantly impact your net result. We focus on structured, multi-year extraction plans that utilise loss carry-back provisions and strategic superannuation contributions to smooth your tax profile. This methodical approach replaces the anxiety of a large tax bill with a structured, well-defined path toward personal liquidity.
Retirement Modelling and Long-Term Projections
True North Lifestyle utilises research-driven data to map future cash flow with surgical accuracy. This process moves beyond simple spreadsheets to provide a clear visualisation of your life in Miranda or the Sydney CBD. By establishing sustainable withdrawal rates, we help you understand exactly how much you can extract today without compromising your longevity. You can explore our specific approach to retirement planning Sydney to see how these projections provide the quiet certainty needed for a multi-year exit strategy.
Estate Planning and Intergenerational Legacy
Succession is about more than just the exit; it's about the legacy that follows. Ensuring your hard work benefits the next generation requires sophisticated wealth transfer strategies Australia. Testamentary trusts are essential here, acting as a shield for your family’s inheritance against external creditors or relationship breakdowns. With the 2026 transfer balance cap set at A$2.1 million, re-contribution strategies are vital to minimise tax on superannuation death benefits for non-tax-dependant beneficiaries. This ensures your wealth remains within the family rather than being eroded by avoidable tax liabilities. If you're ready to secure your family's future, a tailored retirement projection is the first step toward a tax-optimised transition.
Tailored Wealth Management with True North Lifestyle
Clarity replaces anxiety. For the Sydney business owner, the path from operational complexity to personal financial freedom requires more than just a generic investment strategy. It demands a partner who understands that your business is often your largest asset and your greatest source of risk. True North Lifestyle acts as your Steady Navigator, providing a structured, evidence-based process that moves you from uncertainty toward a well-defined legacy. Our methodology is built on a foundation of rigorous research and a commitment to "simplifying the complex," ensuring you can step into a role of confident oversight while we manage the technical depth.
Our process begins with the specialised retirement modelling discussed earlier, allowing us to project your long-term cash flow with surgical precision. This isn't a static document; it's a living roadmap that evolves with your business and the shifting Australian regulatory environment. By implementing business succession planning Australia wide, we help you decouple your lifestyle from your company's daily performance. This ongoing oversight ensures that your personal portfolio remains resilient against market volatility, providing the quiet certainty that your future is secure regardless of the commercial climate.
Our In-House Investment Committee
Independence is our greatest asset. Our in-house Investment Committee constructs bespoke portfolios designed specifically for wealth preservation and sustainable longevity. We don't believe in "off-the-shelf" solutions; instead, we build portfolios that are tailored to your specific risk profile and the industry in which you operate. If your business is in a high-volatility sector, your personal wealth should be its stabilising counterweight. This research-driven approach prioritises low-volatility, income-focused outcomes, ensuring that your family’s security is never compromised by aggressive or unproven strategies. Because we are independent, our interests are always aligned with yours, allowing us to make strategic decisions based solely on what is best for your long-term stability.
Consulting with Our Miranda and Sydney CBD Teams
Local expertise provides the context that digital platforms cannot. With offices in Miranda and the Sydney CBD, our teams are positioned to provide face-to-face strategic planning for complex business structures across the Sutherland Shire and Greater Sydney. We recognise that your financial life has many moving parts, which is why we work alongside your existing tax and legal professionals. This joined-up strategy ensures that our wealth preservation models integrate seamlessly with your corporate structures and estate plans. By coordinating these efforts, we eliminate the gaps that often lead to tax inefficiencies or asset exposure. If you're ready to build a wall between your business risks and your family's future, it's time to organise a strategy session with True North Lifestyle and secure the legacy you've worked so hard to create.
Securing Your Legacy Beyond the Business
Your business is a powerful vehicle for wealth creation, but it shouldn't be the only anchor for your family's future security. Moving from operational complexity to personal financial freedom requires a deliberate shift in strategy. By implementing the robust business succession planning Australia demands in 2026, you can effectively decouple your lifestyle from commercial risks and build a legacy that lasts. We've explored how separating assets and utilising tax-effective extraction models create the stability you deserve.
True North Lifestyle provides the quiet certainty needed to navigate these transitions. Our approach combines bespoke portfolio construction via our in-house Investment Committee with specialised retirement modelling for clients across the Sutherland Shire and Sydney CBD. As an independent, fee-for-service firm, our advice is focused solely on your lifestyle and long-term sustainability. You don't have to manage this complexity alone. We invite you to organise a strategic wealth consultation with True North Lifestyle today. Your future starts with a single, informed choice.
Frequently Asked Questions
How can I pay less tax as a business owner in Australia?
You can reduce your tax liability by utilising the A$30,000 concessional superannuation cap and accessing the small business CGT concessions. In 2026, the company tax rate for base rate entities remains at 25%. Effective tax-minimisation strategies also include loss carry-back provisions for companies with a turnover up to A$1 billion. Coordinating these measures with your personal income tax brackets ensures your business growth doesn't lead to an unsustainable personal tax bill.
Should I use my business to buy my investment property?
Holding an investment property within an operating business is generally discouraged due to asset protection risks. If your company faces litigation, the property could be vulnerable to creditors. Instead, many Sydney owners use discretionary trusts or SMSFs to purchase property, creating a legal firewall. This separation ensures your personal wealth isn't tied to the operational risks of the business, which is a core pillar of business succession planning Australia wide.
Is a Self-Managed Super Fund (SMSF) right for a business owner?
An SMSF can be highly effective for business owners seeking control over their retirement capital. It allows for bespoke portfolio construction and the ability to hold commercial business premises within the fund. However, it requires significant time and compliance oversight. For owners in Miranda and the Sutherland Shire, the decision depends on whether the added control outweighs the administrative burden and whether your balance sheet supports the costs of a private fund.
What is the best way to extract profit from my company for retirement?
The most effective extraction model involves a multi-year balance of fully franked dividends, salary, and concessional superannuation contributions. By using retirement modelling, we determine your Magic Number for capital extraction while staying within lower tax brackets. In 2026, the personal tax threshold for the 30% bracket is A$45,001 to A$135,000. Spreading profit extraction over several years helps avoid the 45% top marginal rate and preserves more capital for your personal portfolio.
How do I protect my personal assets if my business faces legal trouble?
Protection starts with ensuring your family home and personal investments are held in separate legal entities from your trading company. Using discretionary trusts and corporate trustees creates a barrier against commercial litigation. You should also audit your personal guarantees regularly, as these can bypass your corporate shield. Moving surplus cash out of the business and into a protected wealth preservation structure ensures that a commercial setback doesn't result in personal financial ruin.
When should I start retirement modelling if I plan to sell in 5 years?
You should begin modelling immediately, as a five-year window is the minimum required for an effective transition. This timeframe allows you to optimise your business structure and implement tax-effective extraction strategies. Early business succession planning Australia provides a realistic valuation of what you need from a sale versus what you currently have. It gives you the necessary time to build an independent investment buffer that isn't reliant on a single transaction date.
Can I use my business premises in my superannuation fund?
Yes, an SMSF can purchase your commercial business premises through the business real property exception. This allows your business to pay market-rate rent directly into your superannuation fund, which is generally taxed at a concessional rate of 15%. It's a powerful way to turn a business expense into a retirement asset. Owners in Sydney CBD often use this strategy to secure their operational base while simultaneously building a valuable asset for their personal future.
How much do I need to have outside my business to retire comfortably in Sydney?
A comfortable retirement in Sydney often requires a significant liquid buffer due to higher living costs and property expenses. While industry standards suggest a specific annual income, business owners should focus on a bespoke projection based on their desired lifestyle in Miranda or the CBD. We use long-term modelling to calculate the capital required to replace your current drawings. This ensures you can maintain your standard of living without needing to draw down on the business's working capital.


