

Is your retirement fund a passive savings account or a high-performance tax haven? Precision defines outcomes. For many Australians, the difference between a comfortable lifestyle and financial anxiety lies in the strategic rigour of their planning. It's natural to feel frustrated by complex tax legislation or the constant trade-off between marginal income rates and the 15% superannuation tax environment. You deserve to know your capital is protected. This guide offers a clear roadmap to navigate these complexities. By mastering superannuation contribution strategies Australia, you can reduce your personal tax burden and build a sustainable nest egg with quiet certainty. Clarity replaces anxiety.
We've done the heavy lifting to simplify the complex. We will preview the 2026 concessional caps, examine the power of catch-up contributions, and demonstrate how bespoke retirement modelling replaces guesswork with evidence-based projections. You'll discover how to align your contribution limits with your long-term legacy goals, ensuring you step into the next phase of life with total confidence. The path to wealth optimisation is built on structure, and the following chapters provide the stability you need to move forward with purpose.
Key Takeaways
- Identify why superannuation remains the most sophisticated tax-effective vehicle for wealth preservation within the 2026 economic landscape.
- Navigate the 2026 indexed contribution limits and implement superannuation contribution strategies Australia to maximise your retirement savings while minimising tax.
- Uncover advanced tactics like catch-up contributions and re-contribution strategies that can effectively transform taxable assets into a tax-free legacy for your heirs.
- Learn how to utilise the downsizer contribution "free hit" to inject significant capital into your superannuation without breaching standard annual caps.
- Understand why bespoke retirement modelling replaces generic calculators to provide a clear, evidence-based roadmap for your financial future.
Why Your Super Contribution Strategy Matters in the 2026 Economic Climate
Wealth preservation requires a deliberate architecture. In the 2026 economic environment, where interest rates and market volatility continue to fluctuate, superannuation remains the most robust tax-effective vehicle in Australia. It isn't just a savings account; it's a strategic fortress. Relying on passive accumulation is no longer sufficient for those approaching age 60. You need a transition from passive saving to strategic optimisation. This shift provides a psychological anchor. When the markets feel unpredictable, a structured plan offers quiet certainty. You aren't just hoping for a outcome; you're engineering one.
The Stabilising Power of Strategic Super
Clarity eliminates fear. Many pre-retirees in Sydney face a unique set of pressures, from high cost-of-living indexation to the complexities of longevity planning. A bespoke approach replaces the guesswork of generic online calculators with research-driven modelling. By implementing specific superannuation contribution strategies Australia, you move from a state of reactive anxiety to proactive oversight. Our Miranda-based team often sees how a tailored roadmap allows Sutherland Shire residents to visualise their retirement lifestyle with confidence, knowing their legacy is protected by a disciplined methodology. Professional advice replaces the "what if" with a clear "how-to."
Superannuation vs. Outside-Super Investments
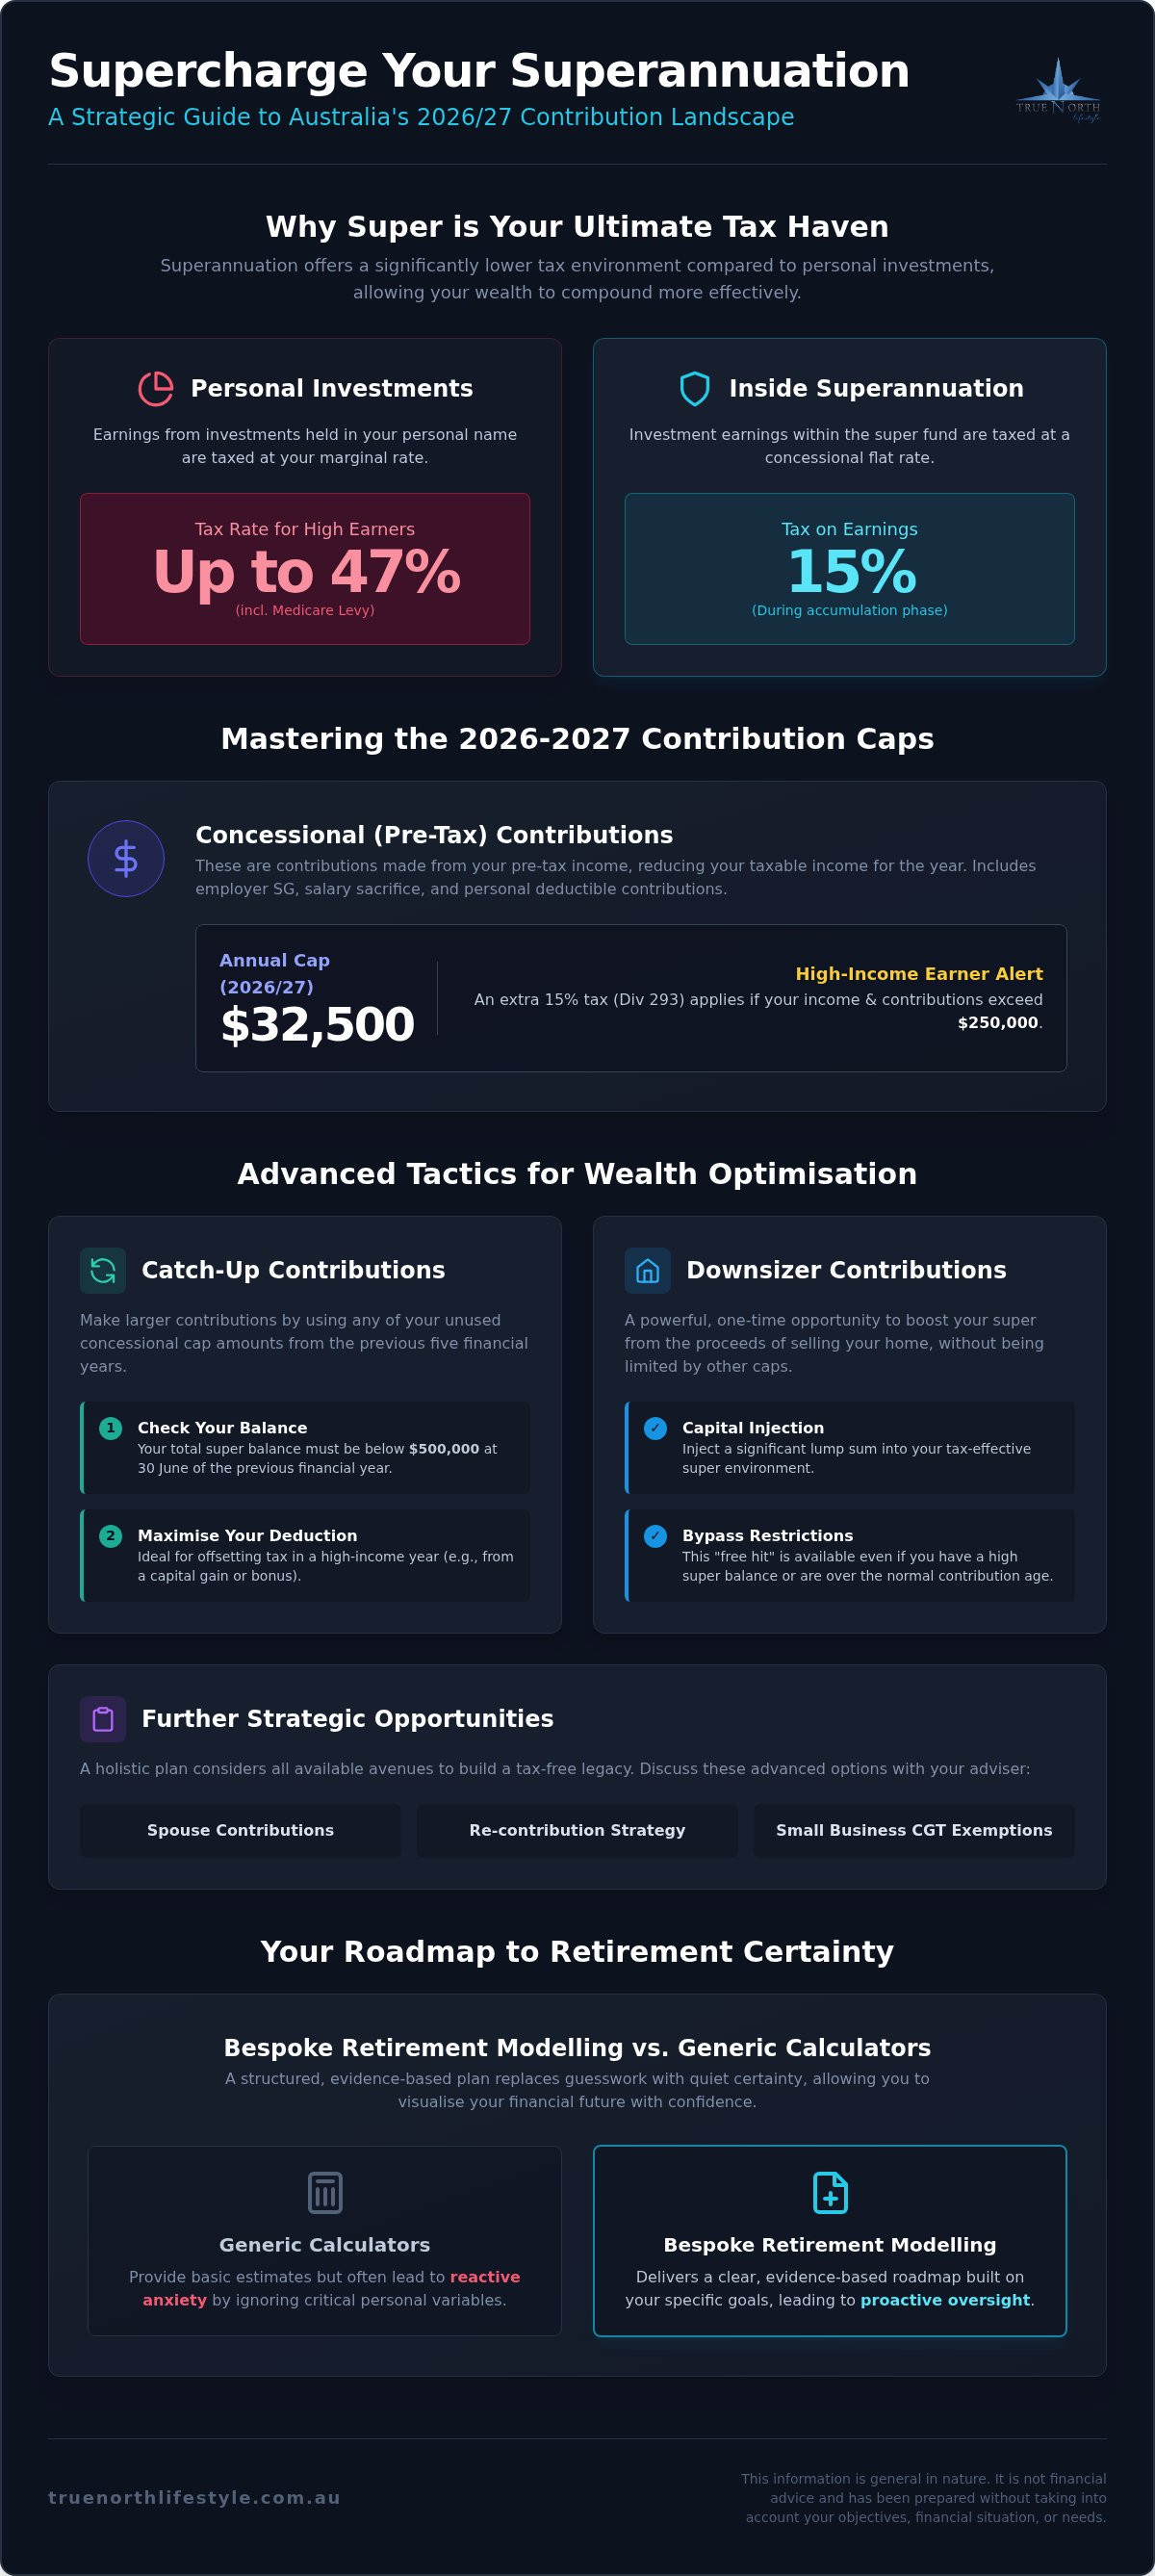
Numbers tell the story. While investments held in personal names are often subject to Sydney’s highest marginal tax brackets, the internal 15% tax rate on superannuation earnings is a significant advantage. Over a 10-year horizon, the power of compounding in this low-tax environment creates a widening gap between super and traditional portfolios. The difference is often measured in hundreds of thousands of dollars in preserved wealth.
- Tax Efficiency: Most high-income earners face a tax rate of 45% plus the Medicare levy on outside earnings, compared to just 15% inside super.
- The Tipping Point: There is a specific threshold where the tax savings of contributing to super outweigh the flexibility of holding cash or shares externally.
- Longevity Focus: Strategic contributions ensure your capital lasts as long as your lifestyle requires, shielding you from the risk of outliving your savings.
Identifying this tipping point requires precise modelling that accounts for your specific income, goals, and risk profile. It's about finding the balance between current liquidity and future security. By aligning your superannuation contribution strategies Australia with your broader wealth objectives, you ensure every dollar is working at its highest potential capacity.
Mastering Concessional and Non-Concessional Contribution Caps
Precision defines outcomes. For the 2026-2027 financial year, the Australian Taxation Office has indexed contribution caps, providing more room for strategic growth within the superannuation environment. Understanding the distinction between concessional (pre-tax) and non-concessional (after-tax) contributions is vital for anyone serious about wealth preservation. When implementing superannuation contribution strategies Australia, these caps serve as the boundaries of your tax-haven. A single miscalculation can lead to unnecessary penalties, yet many Sydney professionals miss out on significant savings by remaining too conservative with their limits. Clarity replaces the anxiety of the unknown.
Maximising Concessional Contributions
The concessional cap for 2026-2027 is now $32,500. This figure includes your employer's compulsory contributions and any salary sacrifice arrangements you've established. For business owners in the Sutherland Shire, personal deductible contributions offer a powerful way to reduce taxable income while fortifying your retirement fund. If your total super balance was below $500,000 at the end of the previous financial year, you may also access "carry-forward" amounts from the last five years. This allows for a substantial tax deduction in a high-income year, effectively smoothing your tax obligations. High earners in the Sydney CBD must remain mindful of Division 293 tax; this applies an additional 15% tax on contributions if your combined income and contributions exceed $250,000.
Strategic Non-Concessional Injections
Non-concessional contributions allow you to move larger sums into the low-tax super environment using after-tax funds. The annual cap is $130,000 for 2026-2027. However, the "bring-forward" rule allows eligible individuals under age 75 to contribute up to $390,000 by using three years of caps at once. This is a vital tool when rebalancing a bespoke investment portfolio after a liquidity event, such as an inheritance or the sale of an asset. You must monitor your Total Super Balance (TSB) closely. Once your balance approaches the $1.9 million threshold, your ability to access the full bring-forward period becomes restricted, eventually ceasing entirely when you reach the $2.1 million Transfer Balance Cap.
Professional superannuation review and optimisation ensures you navigate these thresholds without triggering ATO audits. Timing is everything. Making a large contribution just days too early or late can result in an accidental cap breach. We focus on the mathematical certainty of your plan, ensuring every injection is timed for maximum effect while keeping your long-term legacy protected. Structure provides the stability you need to move forward.
Advanced Tactics: Catch-up, Spouse, and the Re-contribution Strategy
Sophisticated planning requires moving beyond the basics. If you've experienced a high-income year, perhaps through a performance bonus or the sale of an asset, the "catch-up" concessional strategy is an invaluable tool. It allows individuals with a total super balance under $500,000 to access unused cap space from the previous five financial years. This results in a significant personal tax deduction, shielding your wealth during peak earning periods. It's about taking control. These superannuation contribution strategies Australia offer a level of mathematical certainty that simple saving cannot match. You move from a position of uncertainty to one of structured growth.
The Re-contribution Strategy Explained
Legacy planning is often overlooked in the rush to accumulate. Most superannuation balances consist of a "taxable" component that triggers a 15% tax, plus the Medicare levy, when passed to non-dependants like adult children. You can structurally eliminate this burden. By withdrawing funds once you meet a condition of release and re-contributing them as non-concessional funds, you convert that taxable portion into a tax-free component. This is a crucial move for Sydney families looking to protect their intergenerational wealth. The re-contribution strategy acts as a sophisticated legacy preservation tool by structurally eliminating future tax liabilities for your heirs. It's a methodical way to ensure your hard-earned capital stays with your family rather than the ATO.
Spouse Contributions and Balance Equalisation
Balance is strength. For couples, equalising superannuation accounts is a vital component of wealth optimisation. If one partner earns significantly less, a spouse contribution can trigger a tax offset of up to $540, provided their income is below $37,000. This phases out completely once their income reaches $40,000. Beyond immediate tax savings, equalisation ensures both individuals stay below the $1.9 million transfer balance cap. This allows a couple to collectively hold up to $3.8 million in the tax-free retirement phase. Seeking professional Superannuation Advice Sutherland Shire helps you navigate these thresholds with precision. You aren't just managing money; you're securing a shared future. By implementing these advanced superannuation contribution strategies Australia, you replace the anxiety of legislative change with a robust, enduring structure that protects both partners.
Downsizer Contributions and Small Business CGT Exemptions
Strategic injections change lives. For many Sutherland Shire residents, the family home is their most significant asset. The downsizer contribution allows you to unlock that equity without the constraints of standard caps. It is a "free hit". You can contribute up to $300,000 per person, or $600,000 for a couple, directly into your superannuation after selling your primary residence. This is a powerful addition to the broader superannuation contribution strategies Australia. It bypasses the usual age and work test restrictions, provided you are aged 55 or over in 2026. Structure creates freedom.
The Sydney Real Estate Advantage
Property values in Sydney remain a formidable tool for wealth preservation. To qualify, you must have owned your home for at least 10 years. It must be your primary residence. This strategy is particularly effective when integrated with retirement plans that account for Centrelink asset testing. While superannuation in the accumulation phase is generally exempt from the assets test, once you reach Age Pension age, these funds are assessed. Timing your sale and contribution requires precise modelling to ensure your pension eligibility is not inadvertently compromised. You deserve a plan that considers the whole picture.
CGT Exemptions for Business Owners
Miranda business owners have access to specific pathways. Small business CGT concessions can be transformative. If you've held a business asset for 15 years and are retiring, you may be able to ignore the capital gain entirely. Alternatively, the retirement exemption allows for a $500,000 lifetime limit to be moved into super. For the 2026-2027 financial year, the small business CGT cap is $1.935 million. This allows for a massive shift of wealth into a low-tax environment. Effective Tax Planning for Retirement Australia ensures you don't leave money on the table during a sale.
Our team specialises in bespoke retirement modelling to align these sale proceeds with your long-term income needs. We replace the stress of a business exit with a structured path to longevity. Every dollar from your business sale should be optimised for your future.
Integrating Contributions into a Bespoke Retirement Model
Strategy without structure is merely a list of options. While understanding the various superannuation contribution strategies Australia is essential, their true value is only realised when integrated into a comprehensive retirement model. A contribution plan shouldn't exist in isolation. It must be stress-tested against real-world variables such as persistent inflation, market volatility, and the specific risk of sequence of returns. Without this rigorous modelling, you may find yourself over-contributing and unnecessarily sacrificing current liquidity; or worse, under-contributing and risking a shortfall in your later years. Precision replaces guesswork. We ensure your capital is optimised for every stage of the journey.
The True North Lifestyle approach focuses on the mathematical certainty of your future. We look beyond the immediate tax savings of a contribution to see how that capital will behave over twenty or thirty years. By simulating different economic climates, we help you identify the "magic number" required to sustain your specific goals. This level of detail provides a sense of calm and order. You aren't just hoping your money lasts; you are moving forward with a plan that has already done the heavy lifting. Structure provides the stability you need to enjoy the fruits of your labour.
Beyond the Spreadsheet: Lifestyle Modelling
Wealth is a means to an end. Before setting contribution targets, it's vital to define what your desired retirement lifestyle in Sydney actually looks like. Whether it's frequent travel, supporting family, or maintaining a home in the Sutherland Shire, your cash flow needs will dictate your strategy. Bespoke Retirement Planning Sydney moves past generic templates to create a roadmap based on your personal "real-world" requirements. This clarity allows you to make informed choices today that protect your lifestyle tomorrow. We help you visualise the outcome before we finalise the inputs.
The Value of Professional Oversight
Legislation is never static. As your "Steady Navigator," we manage the complexities of changing tax laws and contribution caps so you don't have to. Our bespoke portfolio management complements your superannuation contribution strategies Australia, ensuring your underlying investments are as disciplined as your contribution plan. This holistic oversight is what separates a standard financial product from a tailored wealth preservation strategy. We invite you to take the next step toward quiet certainty. Contact our team to book a comprehensive superannuation review at our Miranda or Sydney CBD offices. Together, we can build a retirement that is as enduring as it is rewarding.
Secure Your Legacy with Precision Modelling
The 2026 landscape demands a shift from passive saving to strategic architecture. We've explored how indexed caps, re-contribution tactics, and downsizer injections can be synthesised into a robust wealth preservation plan. Implementing the right superannuation contribution strategies Australia is the foundation of a stable retirement. It ensures every dollar is working at its highest potential capacity while protecting your intergenerational legacy. Clarity replaces the anxiety of the unknown.
Our Miranda team provides the stabilising advice required for complex wealth transfers, supported by research-driven Investment Committee oversight. We specialise in Sutherland Shire retirement planning, replacing the uncertainty of generic calculators with bespoke modelling that reflects your real-world needs. You deserve a partner who has already done the heavy lifting and the rigorous testing. Structure provides the stability you need to move forward with purpose.
Ready to replace anxiety with clarity? Book a Superannuation Strategy Review with our Miranda Team to ensure your capital is protected for the long term. You've done the hard work; now it's time to ensure your plan does the rest.
Frequently Asked Questions
How much can I contribute to super as a concessional contribution in 2026?
For the 2026-2027 financial year, the concessional contribution cap is A$32,500. This limit includes all employer contributions, salary sacrifice amounts, and any personal contributions for which you intend to claim a tax deduction. If your total superannuation balance was below A$500,000 on 30 June of the previous year, you may be eligible to contribute more by utilising unused cap amounts from the previous five years through catch-up provisions.
What is the re-contribution strategy and how does it save tax?
The re-contribution strategy involves withdrawing a portion of your superannuation after meeting a condition of release and immediately contributing it back as a non-concessional payment. This process effectively converts "taxable" components of your fund into "tax-free" components. While it doesn't provide an immediate income tax deduction, it can significantly reduce the tax your adult children or non-dependant beneficiaries might pay on your death benefit, potentially saving them 17% in tax.
Can I still make super contributions if I am over 75?
Once you reach age 75, your ability to make voluntary contributions is restricted. Generally, super funds can only accept mandated employer contributions or downsizer contributions after this age. Voluntary concessional or non-concessional contributions must usually be received by the fund no later than 28 days after the end of the month in which you turn 75. Professional oversight is essential at this stage to ensure you don't trigger unnecessary ATO penalties.
How does the "bring-forward" rule work for non-concessional contributions?
The bring-forward rule allows eligible individuals under age 75 to access up to three years of non-concessional caps in a single financial year. In 2026, this means you could potentially contribute up to A$390,000. This is one of the most powerful superannuation contribution strategies Australia offers for those who have received an inheritance or sold a large asset. Your eligibility depends on your total super balance staying below specific indexed thresholds.
What happens if I exceed my superannuation contribution caps?
Exceeding your caps results in the ATO issuing a determination and applying additional tax. For concessional breaches, the excess amount is included in your assessable income and taxed at your marginal rate, less a 15% tax offset. For non-concessional breaches, you can elect to withdraw the excess and associated earnings; failing to do so may result in the excess being taxed at the top marginal rate of 47%. Precision in timing is vital.
Is a downsizer contribution worth it for a Sydney property sale?
In the high-value Sydney property market, a downsizer contribution is often a vital wealth preservation tool. It allows you to inject up to A$300,000 per person into super from the sale of your primary residence without it counting toward your standard caps. For Miranda residents aged 55 or over, this "free hit" provides a unique opportunity to move significant equity into a low-tax environment, fortifying your long-term retirement cash flow modelling.
How do I claim a tax deduction for personal super contributions?
To claim a deduction, you must lodge a "Notice of Intent to Claim" form with your superannuation fund before you file your tax return or by the end of the following financial year. Once your fund sends you a written acknowledgement, you can include the deduction on your personal tax return. This strategy is particularly effective for Sutherland Shire business owners looking to reduce their taxable income while building a sustainable retirement nest egg.
What is the Division 293 tax and does it apply to me?
Division 293 is an additional 15% tax applied to the concessional contributions of high-income earners. It applies if your combined income and concessional contributions exceed A$250,000. While this effectively doubles the tax on your contributions to 30%, it remains a tax-effective strategy compared to the top marginal rate of 45% plus the Medicare levy. We help clients model these impacts to ensure their superannuation contribution strategies Australia remain optimised for their specific income level.


