

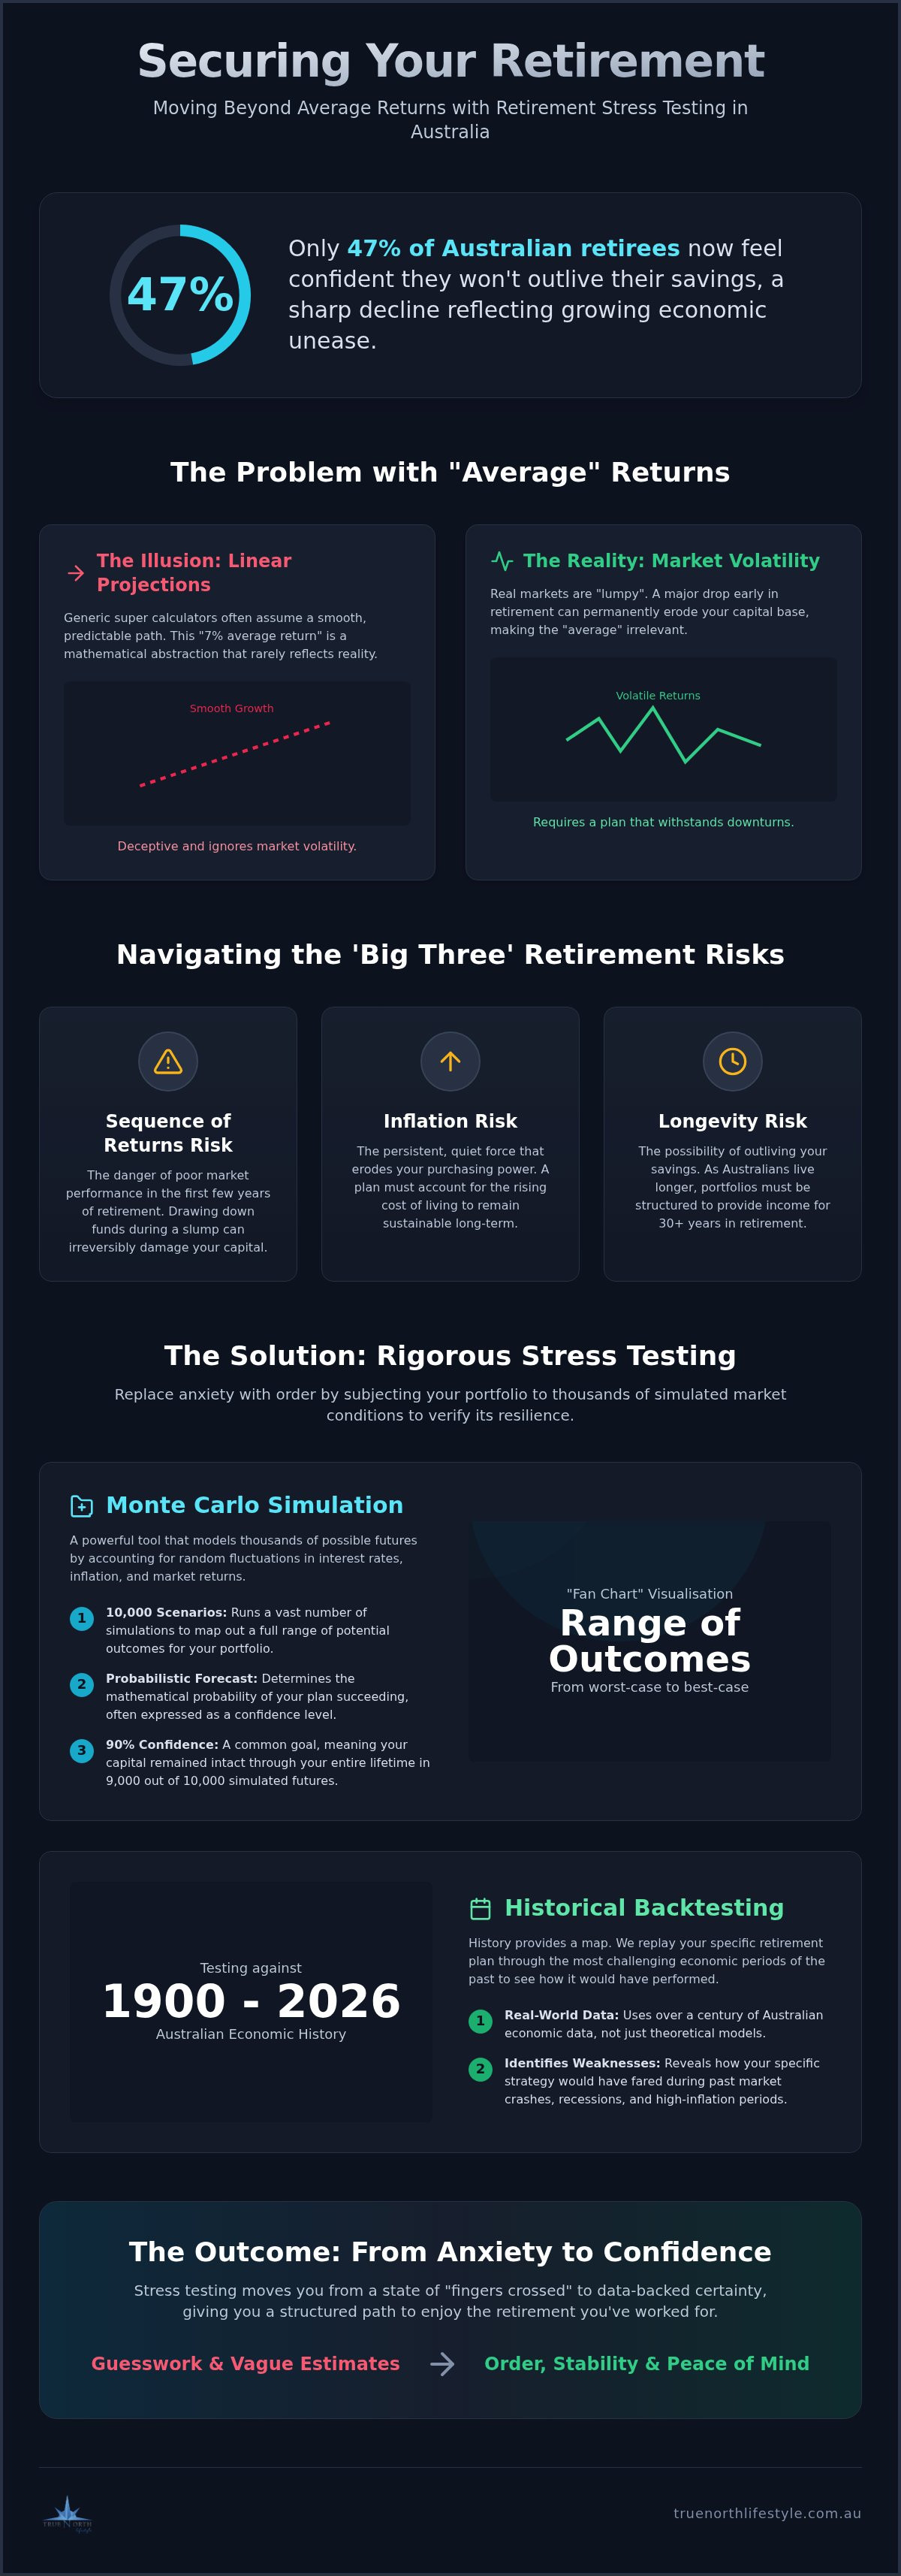
Only 47% of Australian retirees now feel confident they won't outlive their savings. This represents a sharp decline from the previous year, reflecting a growing unease as we navigate the unique economic pressures of 2026. You've likely felt this same tension while reviewing your superannuation statements. It's difficult to find peace of mind when conflicting projections leave you wondering if your lifestyle is truly sustainable. Professional retirement stress testing Australia provides the logical grounding you need to move past this uncertainty. It replaces vague estimates with a rigorous, research-driven assessment of your financial resilience.
Certainty replaces doubt. In this guide, we'll demonstrate how advanced stochastic modelling can shield your nest egg from market volatility and the specific threat of sequence of returns risk. You'll learn how to build a plan that accounts for the most challenging Australian economic scenarios, ensuring your capital is preserved for the long term. We'll explore the transition from financial anxiety to a structured path, giving you the confidence to spend your superannuation exactly as you intended. This is about moving beyond guesswork toward a future defined by order and stability.
Key Takeaways
- Move beyond the trap of "average returns" by understanding why a rigorous audit of your financial sustainability is essential for long-term peace of mind.
- Gain mathematical clarity through retirement stress testing Australia, using historical backtesting and stochastic modelling to prepare for "worst-case" economic scenarios.
- Protect your purchasing power against inflation and sequence of returns risk by identifying the specific vulnerabilities within your current superannuation structure.
- Discover how to organise your wealth into "buckets" and apply dynamic withdrawal rules to ensure your lifestyle remains sustainable through every market cycle.
- Learn how bespoke portfolio construction and expert investment oversight can replace financial anxiety with a structured, low-volatility path toward your retirement goals.
Beyond the Averages: Why Retirement Stress Testing is Essential for Australians
Stability is paramount. Most Australians rely on generic superannuation calculators that assume a smooth, upward trajectory. However, retirement stress testing Australia is a far more sophisticated audit of your financial sustainability. It involves subjecting your portfolio to thousands of simulated market conditions to see if your lifestyle survives the "worst-case" years. This process replaces the inherent anxiety of the unknown with a sense of calm and order. It's about ensuring your plan works in reality, not just on a best-case spreadsheet.
The industry often speaks of a "7% average return." This is a mathematical abstraction that rarely occurs in practice. If you experience a 20% market drop in the first three years of your retirement, that "average" becomes irrelevant. Your capital base is permanently eroded because you were drawing down funds during the slump. Multi-scenario modelling allows us to look beyond these averages to see how your specific portfolio behaves when the "lumpy" reality of the markets arrives.
The Problem with Linear Projections
Linear models are deceptive. They suggest a predictable path that ignores the volatile nature of real-world markets. When you're in the accumulation phase, volatility can be a tool; in retirement, it's a significant threat. Various retirement planning models demonstrate that the sequence of your returns matters just as much as the total amount. Additionally, inflation isn't a static figure. It's a persistent force that quietly erodes purchasing power. A plan that looks "safe" on a spreadsheet can quickly derail when the cost of living in Australia outpaces your portfolio's yield. Stress testing identifies these cracks before they become crises.
The Emotional Value of Clarity
Numbers provide the logic, but the final outcome is emotional. For retirees in high-cost cities like Sydney, the fear of "running out of puff" often leads to unnecessary frugality. You've worked hard to build your nest egg; you should be able to enjoy it. Stress testing establishes a clear "floor" for essential costs and a "ceiling" for discretionary lifestyle spending. It moves you from a state of "fingers crossed" to data-backed confidence. Having a Steady Navigator to do the heavy lifting allows you to step into a role of confident oversight. You can spend your super as intended, knowing your plan has already survived the rigorous testing required for long-term stability.
The Mechanics of Resilience: Understanding Monte Carlo and Historical Backtesting
Confidence is earned. While a single-line projection offers a tidy image, it fails to account for the chaotic nature of financial markets. Professional retirement stress testing Australia utilises two primary engines of resilience: Monte Carlo simulations and historical backtesting. These aren't just mathematical exercises; they're the foundation of a strategy that can withstand the unpredictable. By stress-testing your assumptions, we move from a state of hope to a position of quiet certainty.
Monte Carlo: Modelling 10,000 Possible Futures
Think of this as a stress test for every version of the future. Monte Carlo simulation is a tool used to capture the chaos of real-world markets by running thousands of potential scenarios. It accounts for random fluctuations in interest rates, inflation, and market returns to see how they impact your longevity. The result is often displayed as a "fan chart," showing the range of potential outcomes for your bank balance over thirty or forty years. When we speak of a "90% confidence level," we mean that in 9,000 out of 10,000 scenarios, your capital remained intact throughout your lifetime. This provides a mathematical buffer against the unknown, allowing you to understand the probability of success before you commit to a lifestyle change.
Historical Backtesting: Learning from the Past
History provides a map. While the future won't perfectly mirror the past, historical backtesting allows us to replay your specific plan through the most challenging periods of Australian economic history. We look at data spanning from 1900 to 2026, testing how your strategy would have fared during the 1973 oil crisis or the 2008 Global Financial Crisis. By identifying "fail points" in these high-stress environments, we can refine your investment strategy today. This is particularly vital when planning for retirement in the current 2026 landscape, where inflation and interest rate shifts often mirror historical cycles. Understanding how your portfolio would have survived the stagflation of the 1970s gives you the perspective needed to navigate today's volatility.
These tools transform a "fingers crossed" approach into a disciplined, evidence-based strategy. By understanding the mathematical probability of your capital lasting, you can make informed decisions about your spending and risk tolerance. If you're seeking a partner to perform this rigorous analysis, our team provides bespoke retirement modelling that prioritises your long-term stability and wealth preservation.
Navigating the 'Big Three' Risks: Sequence, Inflation, and Longevity
Stability requires foresight. While we cannot control global market cycles or the rising cost of living, we can certainly control how we prepare for their impact. For most Australians, the anxiety surrounding retirement stems from three primary sources: the timing of market downturns, the erosion of purchasing power, and the mathematical challenge of outliving their capital. Addressing these concerns requires more than a simple superannuation projection. It demands a research-driven strategy that prioritises resilience over raw growth. Through rigorous retirement stress testing Australia, we can identify exactly how these risks interact with your specific lifestyle goals.
Sequence of Returns: Timing is Everything
The first decade of retirement is often referred to as The Retirement Risk Zone. This is the period when your portfolio is most vulnerable to market volatility. If the share market experiences a significant downturn shortly after you stop working, the impact can be catastrophic. You are forced to sell assets at depressed prices to fund your daily expenses, which triggers a "reverse compounding" effect. Your capital base shrinks so significantly that it may never recover, even if the market eventually rebounds. We help you build specific buffers to ensure you never have to liquidate growth investments during a slump, providing a stabilising anchor in a fluctuating environment.
Inflation and Longevity: The Long-Term Grind
Purchasing power matters. In a high-cost city like Sydney, inflation isn't just a headline figure; it's a direct threat to your lifestyle. As the cost of healthcare and aged care in New South Wales continues to rise, your income stream must grow in tandem with the Consumer Price Index (CPI). We also have to account for longevity risk, which is the very real possibility of you living to 100. This means your capital must sustain you for thirty or even forty years. Our wealth preservation strategies focus on maintaining your "real" wealth, ensuring your lifestyle remains sustainable. By modelling these long-term pressures, we provide a structured path that replaces uncertainty with data-backed confidence.
True North’s approach is fundamentally about protection. We understand that a successful retirement isn't just about the highest possible return; it's about the highest possible certainty. By stress-testing your plan against these "Big Three" risks, we ensure that your financial foundation remains firm regardless of external economic shifts. This disciplined methodology allow you to step into a role of confident oversight, knowing the heavy lifting of risk mitigation has already been completed.
Building a Weatherproof Plan: Practical Strategies for Portfolio Stability
Structure brings peace. Once you've utilised retirement stress testing Australia to map your vulnerabilities, the next step is constructing a portfolio that remains resilient regardless of the economic weather. This isn't about chasing the highest possible return; it's about building a framework that protects your lifestyle. By organising your wealth into distinct categories, you can manage short-term needs without compromising long-term growth. This methodical approach replaces the anxiety of market fluctuations with a sense of disciplined control.
The Cash Buffer and Asset Bucketing
For a Sydney retiree, liquidity is the first line of defence. We typically recommend holding one to three years of living expenses in a "cash bucket" to ensure you aren't forced to sell assets during a market correction. The rest of your portfolio is divided into defensive income assets and long-term growth components. This three-bucket structure prevents panic selling because you know your immediate needs are met. It allows your growth assets the time they need to recover from volatility without interrupting your income stream. It's a simple way to simplify the complex reality of market cycles.
Dynamic withdrawal rules further enhance this stability. Rather than taking a fixed percentage every year, you adjust your spending based on pre-defined market "guardrails." When markets perform well, you may choose to fund a special holiday or renovation; when they dip, you slightly reduce discretionary spending. This flexibility, combined with an asset allocation focused on low-volatility income, ensures your capital lasts as long as you do. It's about having a plan that accounts for every version of the future.
Superannuation and Tax Optimisation
Efficiency is key. Within the 2026 environment, utilising transition to retirement (TTR) strategies can be a powerful way to bolster your super while still working. For those seeking superannuation advice Sutherland Shire, we focus on reducing capital gains tax (CGT) and maximising the value of franking credits. These small technical adjustments can have a significant impact on your net position over thirty years. They ensure that more of your hard-earned wealth stays in your pocket rather than being lost to inefficiency. If you're ready to move toward a more structured financial future, our team can help you optimise your superannuation and portfolio today.
Clarity Through Complexity: True North’s Bespoke Retirement Modelling
Data alone is insufficient. While automated reports and online calculators provide raw numbers, they often lack the human context of your lived experience and personal aspirations. At True North Lifestyle, we believe that retirement stress testing Australia should be more than a mathematical exercise; it should be a bridge between technical complexity and lifestyle clarity. We combine research-driven data with your unique goals to create a strategy that feels both protective and empowering. This is the difference between a generic projection and a bespoke roadmap designed for your specific future.
Our Research-Driven Investment Philosophy
Preservation is our priority. Our in-house Investment Committee provides rigorous oversight, focusing on the construction of low-volatility, income-focused portfolios that prioritise wealth preservation above all else. We eschew "off-the-shelf" investment products in favour of bespoke portfolio construction, ensuring every asset serves a distinct purpose within your broader plan. This strategic depth allows us to integrate complex external factors into your modelling, ensuring a holistic view of your financial health. Our process typically incorporates several critical layers of planning:
- Centrelink Structuring: We optimise asset and income test positions to ensure you receive your entitled benefits under the 2026 deeming rates.
- Estate Planning Strategy: We ensure your wealth is preserved not just for your lifetime, but for the legacy you wish to leave behind.
- Tax-Minimisation: Every strategy is refined to protect your net returns from unnecessary erosion, keeping more of your capital working for you.
Your Journey to Financial Longevity
Order replaces anxiety. When you consult with our advisers in Miranda or the Sydney CBD, the process begins with a thorough investigation into your current position and your future needs. We don't just hand you a computer-generated report; we walk you through the various scenarios, explaining the logic behind every recommendation. This professional second opinion provides the quiet certainty needed to make informed choices without feeling overwhelmed by the technical details. It's about giving you the confidence to step into retirement with a plan that has already survived the heavy lifting of rigorous testing.
You can move forward with a sense of disciplined control, knowing your financial foundation is secure against the unpredictability of the markets. If you're ready to transition from uncertainty to a structured, well-defined path, we are here to guide you. Secure your future with a bespoke retirement stress test and discover the peace of mind that comes from true financial resilience.
Securing Your Financial Legacy Through Strategic Resilience
Confidence replaces anxiety. You've seen how retirement stress testing Australia moves your plan from a series of hopeful projections to a rigorous, data-backed strategy. By accounting for the volatile sequence of returns and the persistent erosion of inflation, you can finally enjoy the lifestyle you've worked so hard to build. True North Lifestyle provides the logical grounding and emotional reassurance needed to make these complex decisions with quiet certainty. We focus on transforming uncertainty into a structured, well-defined path.
Our in-house Investment Committee does the heavy lifting, ensuring your portfolio is built for stability and wealth preservation. As specialists in Sutherland Shire retirement planning, we offer a stabilising, fee-for-service advice model that prioritises your long-term success over generic products. It's time to step into a role of confident oversight and secure your capital for the decades ahead. You deserve the peace of mind that comes from knowing your plan is built to survive every version of the future.
Book a bespoke retirement modelling session with our Sydney advisers and take the first step toward a more resilient financial future. Your journey deserves a plan that has already survived the test of reality.
Frequently Asked Questions
What exactly is retirement stress testing?
Retirement stress testing Australia is a rigorous audit of your financial sustainability. It involves simulating thousands of market scenarios to determine if your capital can withstand extreme economic pressures, such as a sharp market downturn or persistent inflation. Unlike a standard linear projection, this process identifies the specific "fail points" in your strategy. It provides you with the mathematical certainty needed to spend your superannuation with confidence, knowing your lifestyle is protected.
How often should I stress-test my Australian retirement plan?
You should ideally stress-test your plan annually or whenever a significant lifestyle or legislative change occurs. In the 2026 landscape, shifts in Age Pension asset thresholds or deeming rates can alter your long-term projections. Regular testing ensures your strategy remains aligned with current market conditions in Sydney. It allows you to make proactive adjustments before a minor fluctuation becomes a structural threat to your longevity, maintaining your path toward financial order.
What is a "good" probability of success in a Monte Carlo simulation?
A "good" probability of success typically sits between 85% and 95%. This means that in 9,000 out of 10,000 simulated futures, your capital remains intact throughout your entire retirement. While a 100% score might suggest you are being overly frugal, a score below 75% indicates a need for strategic adjustments. Our goal is to find the "sweet spot" that allows you to enjoy your wealth without the constant fear of outliving it.
Does stress testing account for changes in the Age Pension rules?
Yes, professional modelling specifically incorporates the latest Centrelink thresholds and Age Pension rates. For example, as of 20 September 2026, the single homeowner asset test threshold is $333,000 for a full pension. We integrate these verified figures into your stress test to see how your income stream interacts with government support. This holistic view is essential for Sydney retirees who need to balance private superannuation with public entitlements effectively.
What is sequence of returns risk and why does it matter in 2026?
Sequence of returns risk is the danger of experiencing poor market performance during the early years of your retirement. If the market dips while you are withdrawing funds, your capital base can shrink catastrophically. In 2026, with only 47% of Australians feeling confident about their savings, this risk is particularly relevant. Stress testing identifies these vulnerabilities early, allowing our Investment Committee to construct low-volatility portfolios that shield you from the "reverse compounding" effect.
Can I perform retirement stress testing myself with a free calculator?
Free online calculators are generally linear tools that rely on "average" returns, which don't exist in the real world. They lack the technical depth to perform complex Monte Carlo simulations or account for the bespoke tax-minimisation strategies required in New South Wales. While they offer a basic starting point, they cannot replace the sophisticated, research-driven modelling provided by a professional adviser. True North Lifestyle provides the rigorous testing needed for genuine mathematical clarity.
How does inflation impact my retirement stress test results?
Inflation acts as a silent tax on your purchasing power. In a high-cost city like Sydney, even moderate inflation can significantly increase your healthcare and lifestyle expenses over thirty years. A robust stress test models your income stream against various Consumer Price Index (CPI) scenarios. This ensures that your spending power remains stable even as the cost of living rises, protecting you from the gradual erosion of your hard-earned nest egg.
What happens if my stress test shows my money might run out?
If a stress test identifies a potential shortfall, we work with you to adjust the variables. This might involve refining your asset allocation to focus on income-producing assets or implementing dynamic withdrawal rules. We might also explore tax-minimisation strategies or Centrelink structuring to bolster your cash flow. The goal is to identify these issues now so you can make informed, methodical changes that secure your financial future in Miranda or the Sydney CBD.


