

What if the greatest risk to your retirement isn't a market dip, but a strategy that fails to account for the unique cost of a life well-lived in the Sutherland Shire? For many locals, the transition into 2026 has brought a complex mix of new superannuation tax thresholds and fluctuating global markets. It's natural to feel a sense of unease when your long-term security feels tied to shifting legislation rather than a concrete plan. Partnering with a dedicated financial planner Miranda NSW can transform this uncertainty into a structured path forward. You've worked hard to build a life near the Port Hacking or the Cronulla coastline; the fear of outliving your capital shouldn't cast a shadow over those years.
We specialise in replacing guesswork with precision through research-driven retirement modelling and bespoke investment strategies tailored to your specific goals. This article explores how we use advanced projections to provide the visual clarity you need to see your financial future with absolute confidence. You'll discover how we optimise your superannuation structures and tax positions to ensure you can enjoy the local lifestyle you love, underpinned by a roadmap that's as resilient as it is personal.
Key Takeaways
- Discover why balancing the unique cost of a Sutherland Shire lifestyle requires a local perspective on long-term capital preservation in 2026.
- Learn how dynamic retirement modelling replaces static spreadsheets with interactive cash flow projections that adapt to shifting market conditions.
- Identify opportunities to reduce tax on your superannuation for beneficiaries using advanced re-contribution strategies recommended by a financial planner Miranda NSW.
- Understand the importance of a low-volatility, income-focused investment philosophy in providing stability and consistent outcomes during your retirement years.
- Explore how a research-driven, collaborative process takes the heavy lifting off your shoulders to replace financial anxiety with quiet certainty.
Retirement in Miranda: Local Expertise Matters in 2026
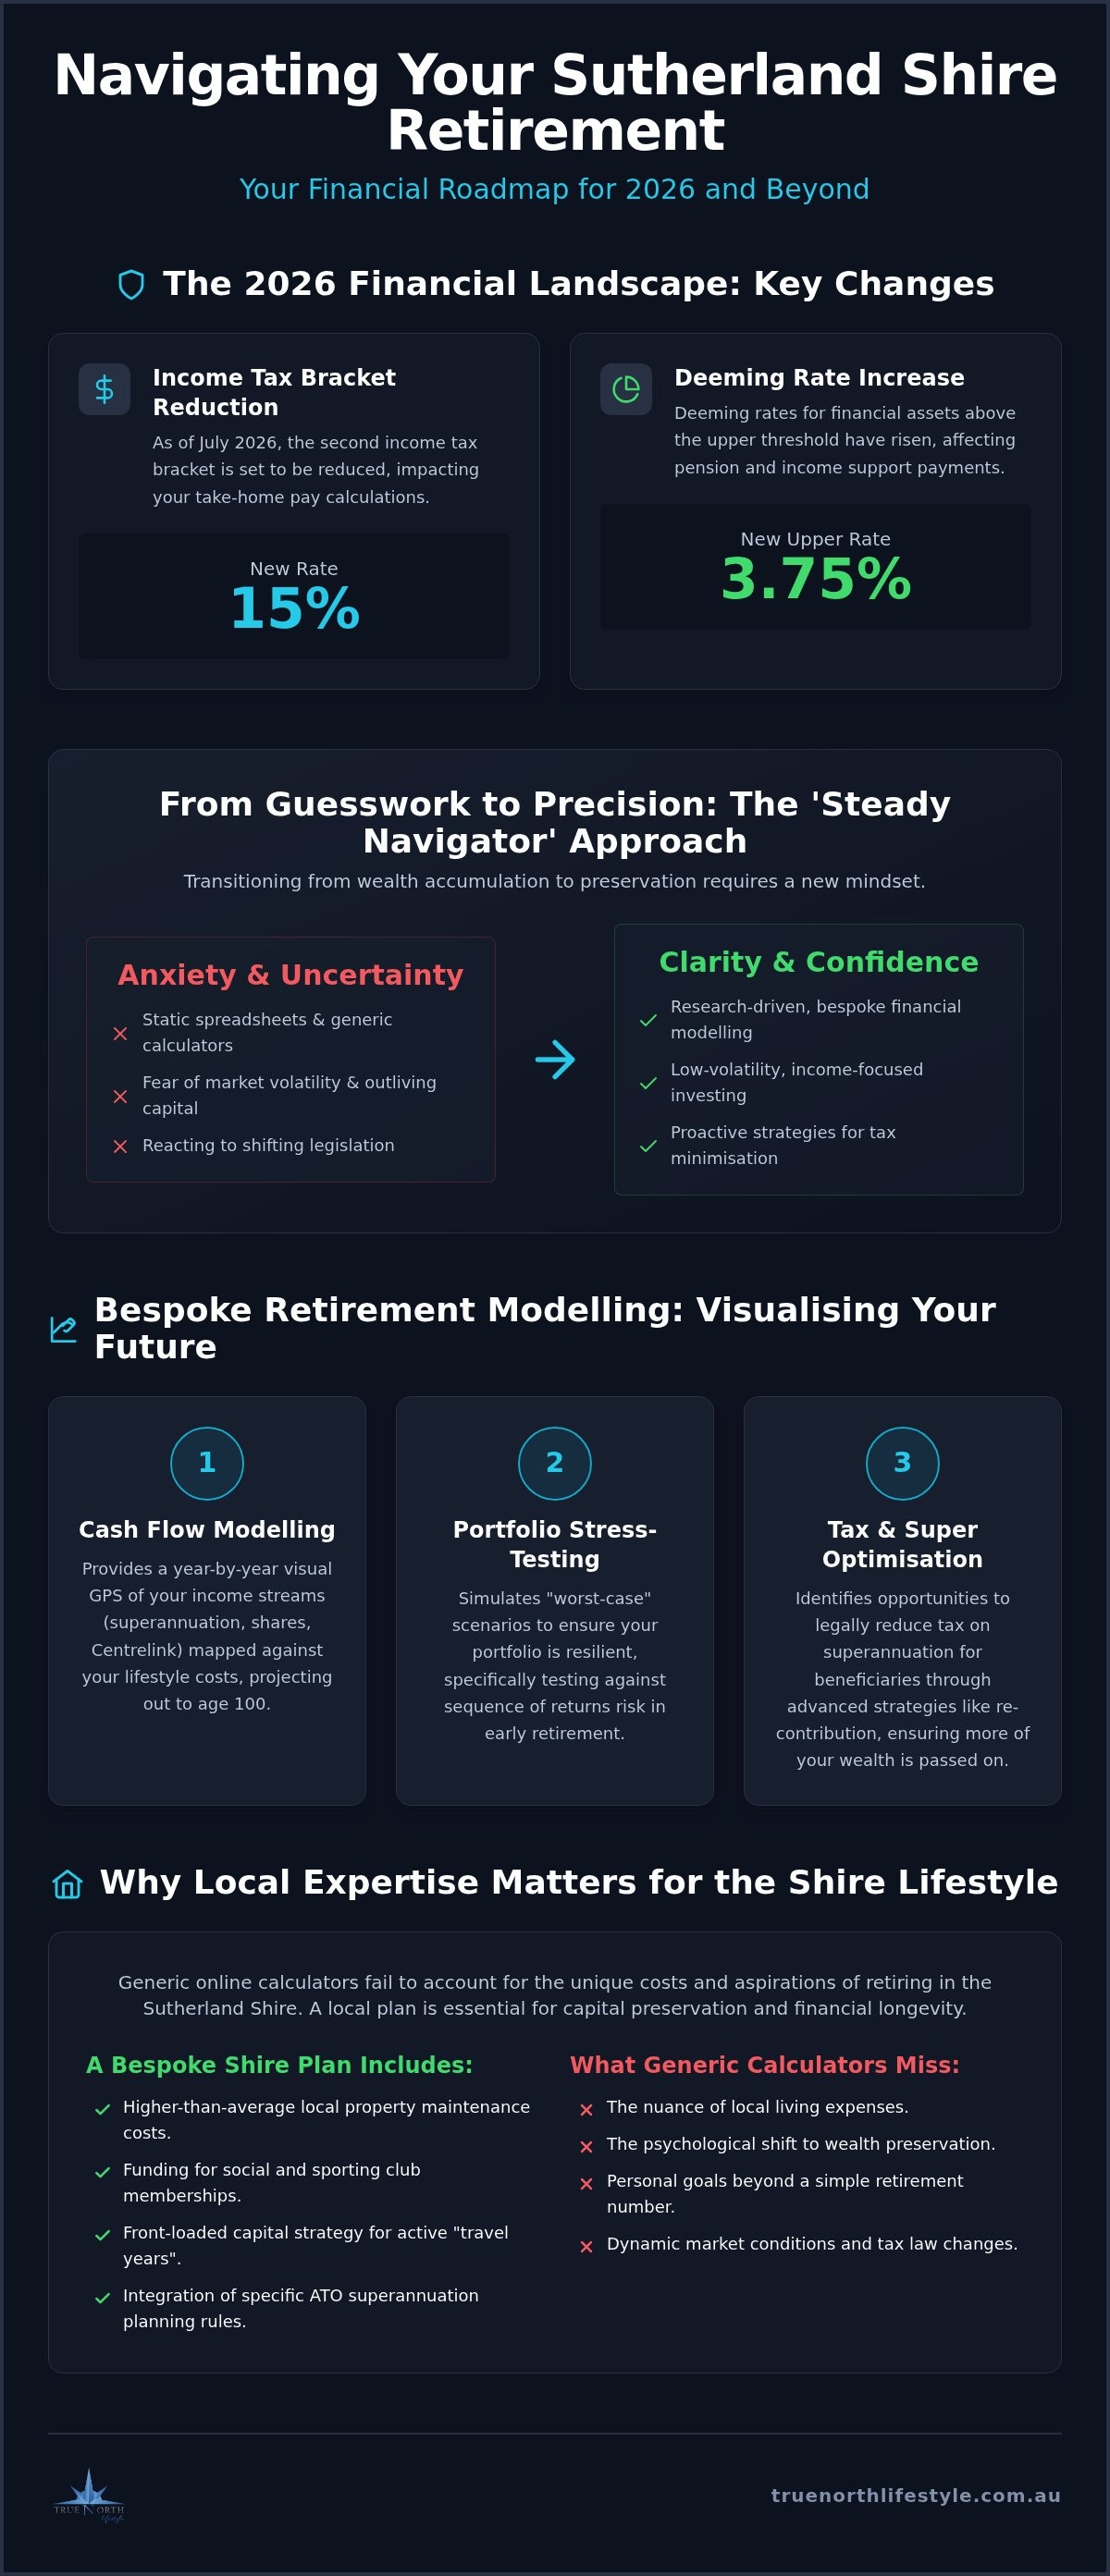
The 2026 financial environment presents a unique set of challenges for those approaching the end of their professional lives. We've seen the second income tax bracket reduced to 15% as of July 2026, while concurrently, deeming rates have risen to 3.75% for financial assets above the upper threshold. For residents here, navigating the superannuation system in Australia requires more than just a passive interest. It demands a proactive strategy grounded in current data. Securing a financial planner Miranda NSW ensures that your retirement roadmap isn't just a generic template, but a living document that accounts for the specific economic pulse of the Sutherland Shire.
The Shire Lifestyle and Financial Longevity
Lifestyle costs here are distinct. Maintaining a home in Miranda or the surrounding suburbs while funding an active retirement involves a different "number" than in other parts of the country. Generic online calculators often overlook the nuance of local living expenses, such as higher-than-average property maintenance or the desire to remain connected to the local social and sporting clubs that define Shire life. We focus on the "active years" first. These are the years where your health and mobility allow for travel and leisure, requiring a front-loaded capital strategy that ensures you don't have to compromise on your standard of living later. Planning for longevity means ensuring your capital lasts as long as you do, without sacrificing the local experiences that make our region special.
Stabilising Your Financial Future
The shift from earning a salary to living off your assets is often fraught with anxiety. It's an emotional transition. Moving from wealth accumulation to wealth preservation requires a psychological pivot that many find difficult to manage alone. Our "Steady Navigator" approach is designed to replace this uncertainty with a sense of calm and order. By using a research-driven methodology, a financial planner Miranda NSW can demonstrate, through rigorous testing, how your portfolio is built to withstand market volatility. We operate on a transparent, fee-for-service basis, establishing a foundation of trust where the human outcome is always the priority. This isn't about chasing the latest trend; it's about evidence-based logic that protects your capital for the long term. We provide the heavy lifting, allowing you to step into a role of confident oversight.
Bespoke Retirement Modelling: Moving Beyond Static Financial Plans
Clarity. Stability. Order. These are the foundations of a successful retirement, yet traditional financial plans often fall short by remaining static. A traditional plan is a snapshot in time; it's a fixed document that quickly becomes obsolete as markets shift and personal circumstances evolve. In contrast, bespoke retirement modelling is a dynamic, living process. By partnering with a financial planner Miranda NSW, you move away from guesswork and toward a research-driven projection of your financial future. This methodology doesn't just predict a number; it maps the human outcome of your wealth over several decades.
Cash Flow Modelling for Clarity
Visualising your future is the first step toward peace of mind. Cash flow modelling acts as the GPS for your financial life. This process allows you to see exactly how your various income streams, including superannuation, private share portfolios, and potential Centrelink entitlements, will fund your lifestyle year by year. It's about identifying the "gap" between your current assets and the cost of the Shire lifestyle you've worked so hard to achieve. We utilise detailed data, including ATO superannuation planning rules, to ensure your projections are grounded in current regulatory reality. When you can see your income mapped out until age 100, the inherent anxiety of the unknown begins to fade.
Stress-Testing and Portfolio Sustainability
Markets fluctuate. Inflation persists. To ensure your strategy is resilient, we subject your retirement model to rigorous stress-testing. We simulate "worst-case" economic scenarios, specifically looking at sequence of returns risk. This is the risk that a market downturn occurs in the early years of your retirement, which can have a disproportionate impact on the longevity of your capital. We also model the impact of rising living costs in 2026 to ensure your purchasing power is protected. By integrating specific wealth preservation strategies, we build a portfolio that is designed to survive volatility rather than just hope for the best. Our methodology involves mapping every decade of your journey, providing a structured path that adapts as you do. If you're seeking a partner to help you navigate these complexities, exploring a bespoke advisory relationship can help secure the certainty you need.
Strategic Superannuation and Tax Minimisation for Shire Residents
Efficiency is everything. In the 2026 financial year, the Superannuation Guarantee has reached 12%, yet many Shire residents continue to operate with contribution models designed for a previous decade. Maximising your net retirement income requires a move beyond simple accumulation. It demands a sophisticated understanding of how to structure your assets to withstand shifting thresholds. A financial planner Miranda NSW acts as a steady guide through these complexities, ensuring that your superannuation isn't just a growing balance, but a tax-efficient engine for your future. When evaluating your options, using a robust framework for choosing a financial planner helps ensure your strategic interests remain the absolute priority.
One of the most powerful, yet underutilised, tools for high-net-worth individuals is the re-contribution strategy. By withdrawing and then re-contributing funds back into your super as non-concessional payments, you can effectively convert the "taxable" component of your balance into a "tax-free" component. This is a critical wealth preservation tactic. It protects your beneficiaries from significant tax liabilities, often referred to as the "death tax", which can otherwise claim up to 17% of your superannuation when passed on to non-dependants. With the non-concessional cap now at $130,000 for the 2026-2027 period, the window for these strategic movements requires precise timing and expert oversight.
Superannuation Review and Optimisation
Structure dictates outcome. We begin by assessing whether an SMSF, a retail fund, or an industry fund provides the most logical foundation for your specific capital level. For many local professionals, the benefits of superannuation advice Sutherland Shire lie in the granular review of fee structures and investment performance that generic platforms often obscure. We ensure your fund is not just "performing," but is strictly aligned with your bespoke risk profile. This involves a research-driven analysis of underlying assets to eliminate unnecessary volatility while maintaining the growth required to fund your lifestyle.
Tax Planning and Centrelink Structuring
Your net income is what matters. Strategic tax planning involves more than just looking at your year-end figures; it requires proactive asset sell-down strategies to minimise Capital Gains Tax (CGT). Furthermore, even self-funded retirees can benefit from Centrelink modelling. With the upper deeming rate at 3.75% as of September 2026, structuring your assets correctly can sometimes unlock partial Age Pension entitlements or the Commonwealth Seniors Health Card. Integrating tax planning for retirement Australia into your annual review ensures that no part of your hard-earned wealth is lost to avoidable inefficiencies. We provide the logic and structure, allowing you to enjoy the Shire lifestyle with quiet certainty.
Choosing the Right Financial Planner in Miranda NSW: A Selection Framework
Selection involves logic. Trust requires evidence. When searching for a financial planner Miranda NSW, the framework you use to evaluate them is just as important as the advice they provide. Miranda currently hosts 30 ASIC-registered advisers, but their philosophies and ownership structures vary significantly. A privately owned firm provides a layer of protection against institutional bias. It ensures that the strategies recommended are driven by your needs, not a parent company's product list. You deserve a partner who has already done the heavy lifting, allowing you to step into a role of confident oversight.
The Importance of Bespoke Investment Advice
Generic portfolios often fail to manage downside risk effectively. They are built for the masses, not the individual. The role of an in-house Investment Committee is to construct stability through rigorous testing and research. This is why the bespoke investment advice Sydney clients receive is fundamentally different from standard managed funds. We focus on low-volatility, income-focused outcomes that protect your capital during market fluctuations. It's a disciplined approach that values proven outcomes over flashy innovation.
Fee Transparency and Professional Standards
Transparency is non-negotiable. Before committing, you should have a clear understanding of the difference between implementation fees and ongoing advisory fees. Fee-for-service is the gold standard for unbiased financial advice; it ensures the adviser's interests are perfectly aligned with yours. During an initial consultation, ask about their modelling tools and the frequency of strategic reviews. Verify their FAAA membership and professional indemnity insurance. These are the baseline requirements for a professional relationship built on quiet certainty.
A local presence matters. Having a financial planner Miranda NSW with a physical office in the 2228 postcode allows for face-to-face strategic reviews that build deeper understanding. These meetings provide a collaborative environment where we can refine your roadmap in real-time. If you value directness and honesty, you can book a consultation at our local office to see our research-driven modelling process in person.
The True North Lifestyle Experience: From Clarity to Confidence
Quiet certainty. This is the ultimate outcome of a well-constructed financial plan. Our collaborative process is designed to take the heavy lifting off your shoulders, moving you from a state of financial anxiety to one of structured order. As a dedicated financial planner Miranda NSW, we don't just provide a one-off report. We offer the 'Steady Navigator' promise: a commitment to directness, honesty, and a relentless focus on real-world probability. By grounding every decision in research-driven data, we ensure you can step into a role of confident oversight without feeling overwhelmed by technical complexity.
Your journey with us begins with a deep dive into your current position and your long-term aspirations. We look beyond the numbers to understand the human outcomes you desire for your future in the Sutherland Shire. During your initial Miranda consultation, you can expect a transparent discussion about your goals, our methodology, and how we use advanced modelling to map your path forward. It's a professional partnership where your peace of mind is the primary metric of success. We've already done the rigorous testing, allowing you to focus on the life you've worked hard to build.
Managing Your Legacy and Wealth Transfer
Protecting what you've built requires a forward-looking perspective on intergenerational wealth. We integrate comprehensive estate planning strategies into your core financial roadmap to ensure your legacy remains secure. This involves simplifying the often complex process of beneficiary nominations and the strategic use of testamentary trusts to protect your family's future. Implementing robust wealth transfer strategies Australia wide ensures that your capital is preserved and passed on according to your exact wishes, minimising potential disputes and tax inefficiencies for your loved ones. We provide the structural logic, so you can focus on the human connections.
Your Path to Financial Longevity
Financial longevity is about more than just surviving; it's about thriving throughout every decade of your retirement. The transition from uncertainty toward a well-defined path is a methodical progression that we manage together. We act as your anchor in a fluctuating environment, monitoring the 'True North' of your financial goals and adjusting your strategy as markets and regulations evolve. This ongoing partnership provides the stability you need to enjoy the local lifestyle without the constant stress of financial management. To begin your own modelling journey and secure your future, book a consultation at our Miranda office today.
Securing Your Vision for the Years Ahead
Retirement is not a destination; it's a continuing journey that requires a dynamic roadmap rather than a static document. By moving beyond simple accumulation toward research-driven modelling, you ensure your capital is resilient enough to fund your lifestyle in the Sutherland Shire through 2026 and beyond. We've explored how strategic tax structures and bespoke portfolio construction work together to replace financial anxiety with quiet certainty. As a privately owned financial planner Miranda NSW, we remain dedicated to providing the logic and structure you need to make informed choices with confidence.
Our in-house Investment Committee provides the rigorous oversight necessary to protect your wealth from unnecessary volatility. You deserve a partner who has already done the heavy lifting, allowing you to focus on the human outcomes of your financial success. Secure your financial future with a bespoke retirement model; book your consultation with True North Lifestyle today. Step into your retirement years with the clarity and peace of mind you've earned.
Frequently Asked Questions
How much does a financial planner in Miranda typically cost?
Professional fees for a financial planner Miranda NSW are typically structured as a combination of upfront strategic advice fees and ongoing management fees. The exact cost depends on the complexity of your situation, such as whether you require detailed retirement modelling or complex tax structuring. At True North Lifestyle, we operate on a transparent, fee-for-service basis. This ensures our interests are aligned with yours, providing clarity on the value of the advice before any implementation begins.
Do I need a financial planner if I only have an industry super fund?
Even with an industry super fund, professional advice is essential to ensure your fund aligns with your broader retirement goals and risk profile. An industry fund is a vehicle, but it doesn't provide the bespoke tax-minimisation or estate planning strategies required for high-net-worth individuals. We review your fund's performance and fee structures, integrating it into a comprehensive roadmap that accounts for your specific lifestyle costs in the Sutherland Shire and long-term capital preservation.
What is the difference between financial advice and retirement modelling?
Financial advice focuses on the strategic recommendations, such as which tax structures or superannuation funds to use, while retirement modelling provides the visual projection of your future cash flow. Modelling acts as a GPS for your finances, simulating how your assets will last over several decades under various market conditions. This research-driven approach allows you to see the tangible impact of different choices, replacing the anxiety of the unknown with a sense of quiet certainty.
Can a financial planner in Miranda help me with Centrelink entitlements?
Yes, we specialise in Centrelink structuring to help retirees maximise their entitlements. As of September 2026, the upper deeming rate has increased to 3.75%, which can significantly impact how your financial assets are assessed. By correctly structuring your portfolio, a financial planner Miranda NSW can often improve your eligibility for the Age Pension or the Commonwealth Seniors Health Card. We use detailed modelling to ensure your income streams are optimised within the current regulatory framework.
How often should I review my financial plan in 2026?
We recommend a comprehensive review at least once a year, or whenever significant legislative changes occur. With the 2026 reduction in income tax brackets and the Superannuation Guarantee reaching 12%, regular check-ins are vital to keep your strategy on track. These reviews allow us to adjust your bespoke retirement model for inflation and market fluctuations. Staying proactive ensures your "True North" remains aligned with your personal journey and the evolving Australian financial landscape.
What is a 'bespoke' investment portfolio and why does it matter for retirees?
A bespoke investment portfolio is a custom-constructed collection of assets built specifically for your risk tolerance and income needs. Unlike generic managed funds, these portfolios are designed by our in-house Investment Committee to focus on low volatility and wealth preservation. This matters for retirees because it helps manage sequence of returns risk, protecting your capital during market downturns. It's a disciplined, research-focused methodology that prioritises real-world probability and stable, long-term outcomes for your lifestyle.
Is True North Lifestyle an independent financial advisory firm?
True North Lifestyle is a privately owned financial advisory firm. This ownership structure is a critical differentiator, as it ensures our advice is free from institutional bias often found in bank-aligned or large corporate practices. We collaborate with Resonant Asset Management to build bespoke portfolios, but our primary focus is always on the human outcome for our clients. This independence allows us to act as a steady navigator, providing honest and direct strategic guidance.
What should I bring to my first appointment with a financial planner?
To get the most out of your initial consultation in Miranda, you should bring your latest superannuation statements, a summary of your investment assets, and your most recent tax returns. It's also helpful to have a rough outline of your current living expenses and a list of your primary retirement goals. This information allows us to begin the process of simplifying your complex financial situation and building a foundation for your bespoke retirement model.


