

What if the traditional nest egg you've been diligently growing is actually losing its purchasing power faster than you can replenish it? With underlying inflation sitting at 3.6 per cent and the official cash rate at 4.35 per cent, the financial ground beneath many Sydney families feels increasingly unstable. It is natural to feel a sense of unease. You've worked hard to reach this point, yet the complexity of the new Division 296 tax thresholds and shifting superannuation laws can make the future feel like a moving target.
We understand that you're looking for more than just generic advice; you're seeking a sense of calm and order. This guide provides a strategic roadmap for building wealth for retirement Australia in 2026. You will discover how to navigate these legislative shifts with research-driven strategies designed to build, protect, and optimise your capital for a stable, enduring retirement. We will preview the latest contribution caps, examine bespoke portfolio construction, and outline how sophisticated modelling can secure your family legacy while ensuring you never outlive your savings.
Key Takeaways
- Understand why synchronising your superannuation, bespoke portfolio, and tax structures is critical for building wealth for retirement Australia in today's shifting economy.
- Navigate the complexities of the Division 296 tax with specific strategies designed to protect high-value balances above the A$3 million threshold.
- Evaluate whether an SMSF or an industry fund offers the right balance of control and convenience for your unique financial objectives.
- Discover how dynamic retirement modelling provides the necessary certainty to maintain your lifestyle without the fear of outliving your capital.
- Learn how institutional-grade research can be applied to your personal wealth to ensure your family legacy remains secure against inflation.
Navigating the 2026 Landscape of Australian Wealth Accumulation
Accumulating wealth in 2026 is no longer a simple matter of time and compound interest. The economic environment has shifted, marked by persistent inflation and a cash rate that demands a more disciplined approach to capital management. For many families in Sydney, the process of building wealth for retirement Australia carries a significant emotional weight. It isn't just about the numbers on a balance sheet; it's about the security of a lifetime's work and the fear that shifting regulations might erode that foundation. We advocate for Strategic Stability over aggressive speculation, recognising that a one-size-fits-all model inevitably fails when faced with complex tax laws and volatile global markets.
The Steady Navigator Philosophy
Clarity replaces chaos. Our core philosophy is built on replacing the inherent anxiety of financial decision-making with a structured, logical framework. We move away from the "accidental wealth" often seen in rising property markets and transition toward intentional, modelled outcomes. This requires a research-driven methodology that doesn't just look at past performance but models future probabilities. By collaborating with Resonant Asset Management, we bring institutional-grade investment oversight to your personal portfolio. This disciplined structure allows you to step into a role of confident oversight, knowing the heavy lifting of testing and verification has already been completed.
Why 2026 is a Pivotal Year for Investors
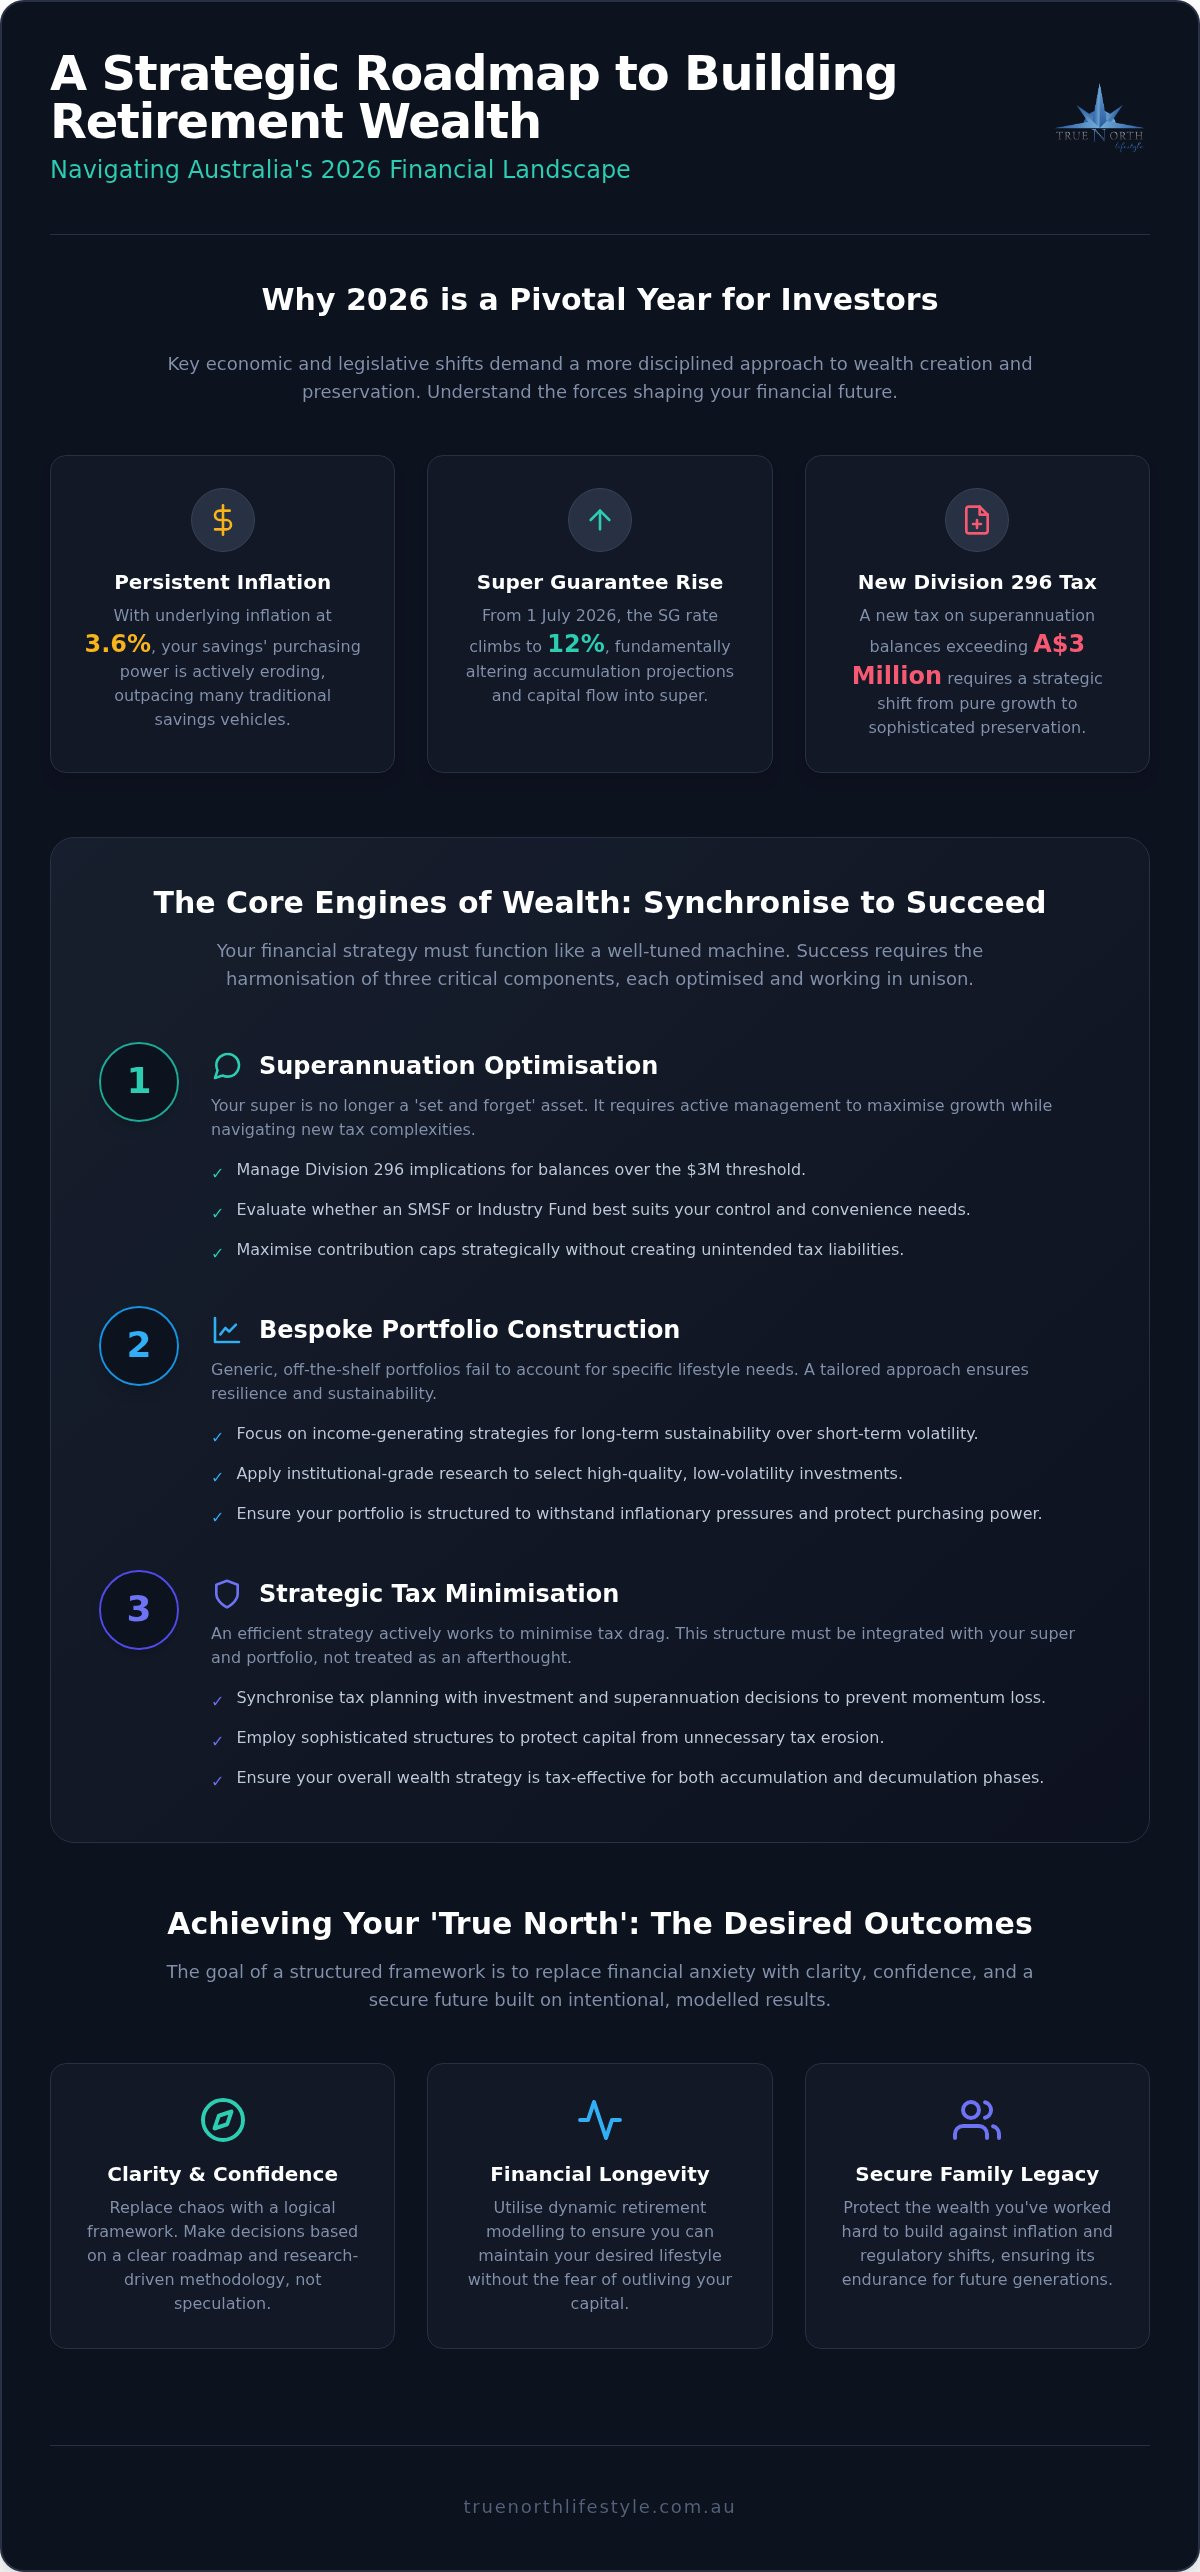
Significant structural changes are currently reshaping the path to financial independence. From 1 July 2026, the Superannuation in Australia system sees the Superannuation Guarantee rate climb to 12 per cent, fundamentally altering accumulation projections for every working professional. However, this increase in capital brings new challenges. With the introduction of the Division 296 tax on balances exceeding A$3 million, high-net-worth individuals must undergo a psychological shift from pure growth to sophisticated preservation. Building wealth for retirement Australia now requires identifying the "True North" of your financial goals, ensuring your strategy is bespoke enough to handle tax-minimisation while protecting the family legacy you've worked so hard to build.
The Core Engine Rooms of Wealth: Super, Portfolios, and Tax
Efficiency requires harmony. To succeed in building wealth for retirement Australia, your financial strategy must function like a well-tuned machine where superannuation, investment portfolios, and tax structures act as synchronised engine rooms. If one underperforms or operates in isolation, the entire vehicle loses momentum. We focus on research-driven asset selection to identify high-quality, low-volatility investments that can withstand inflationary pressures. This disciplined approach, backed by institutional-grade data, ensures your capital isn't just growing, but is protected against the erosion of purchasing power through strategic diversification across these core sectors.
Superannuation Optimisation and Review
Review your foundations. With the Superannuation Guarantee rate now at 12 per cent, the volume of capital entering the system is significant, but so are the regulatory risks. We assess fund performance against 2026 benchmarks while carefully managing the implications of the Division 296 tax on balances exceeding A$3 million. Integrating these variables into a cohesive superannuation advice Sutherland Shire strategy allows you to maximise contribution caps without inadvertently creating a tax liability that outweighs the benefits of growth.
Bespoke Portfolio Construction
Bespoke beats generic. Off-the-shelf portfolios frequently fail Sydney investors because they don't account for specific lifestyle requirements or the nuances of the local market. Our in-house Investment Committee provides rigorous oversight, focusing on income-focussed strategies that prioritise long-term sustainability over short-term volatility. While the Australian government's guide to retirement planning offers a helpful baseline for general needs, a tailored portfolio construction ensures your specific risk profile is modelled with precision. If you're unsure if your current mix is resilient enough, a portfolio sustainability model can provide the clarity you need.
Strategic Tax Minimisation
Stop the leakage. Tax is often the single largest drag on wealth accumulation, yet it's frequently the most overlooked. Effective tax planning for retirement Australia involves using sophisticated structures like family trusts or investment bonds to shield earnings. We work to reduce Capital Gains Tax (CGT) drag, ensuring more of your returns remain invested to benefit from compounding. By optimising your tax position, we turn a passive expense into an active contributor to your retirement longevity, ensuring you're building wealth for retirement Australia in the most efficient manner possible.
SMSFs vs. Industry Funds: Choosing Your Growth Vehicle
The choice of vehicle is a fundamental structural decision. It determines how much control you exert over your assets and the administrative burden you're willing to carry. For those building wealth for retirement Australia, the tension between a Self-Managed Super Fund (SMSF) and a high-performing industry fund often comes down to lifestyle-aligned modelling. It isn't just about fees; it's about which structure best serves your long-term vision for intergenerational wealth transfer and asset protection. Each vehicle has its own distinct set of costs and benefits in the 2026 landscape, requiring a logical framework to decide which path aligns with your personal objectives.
The Case for Self-Managed Super Funds (SMSFs)
Unmatched control awaits. For many Sydney investors, the primary appeal of an SMSF lies in the ability to hold direct property or idiosyncratic assets that are unavailable in traditional funds. This structure offers superior estate planning flexibility, allowing for bespoke death benefit nominations that can significantly reduce tax leakage for adult children beneficiaries. However, the 2026 regulatory landscape demands rigorous attention. Compliance and audit requirements have become more stringent, meaning you must weigh the benefits of control against the time required for diligent oversight. For balances approaching the A$3 million Division 296 threshold, the ability to implement specific re-contribution strategies within an SMSF can be a powerful tool for wealth preservation and managing your total superannuation balance.
When Industry or Retail Funds Make Sense
Simplicity offers peace. Industry or retail funds often provide a more efficient path for those who prefer a hands-off approach to wealth accumulation. These vehicles grant access to unlisted infrastructure and institutional-grade assets that are difficult for individual SMSFs to replicate. The administrative overhead is significantly lower; you're freed from the complexities of annual audits and the legal responsibilities of being a trustee. We often find that wrapping bespoke advice and strategic portfolio construction around a standard fund structure provides the optimal balance. It allows you to benefit from institutional stability while still maintaining a tailored approach to building wealth for retirement Australia. This route is frequently the most cost-effective for busy professionals who value their time as much as their capital growth and prefer a simplified, high-level oversight role.
Managing Advanced Tax Challenges: Division 296 and Re-contribution
Complexity demands precision. As you progress in building wealth for retirement Australia, you must confront the latest legislative hurdles that target high-value assets. Division 296 is a 15 per cent additional tax on earnings for individuals with a Total Superannuation Balance exceeding A$3 million. This tax, effective from 1 July 2026, changes the mathematical reality of wealth preservation. It requires a move from simple accumulation to a more defensive, modelled posture. We specialise in identifying these risks early, ensuring that your hard-earned capital isn't unnecessarily depleted by avoidable tax leakage.
Modelling the Impact of Division 296
Data drives decisions. Understanding your exposure starts with rigorous modelling of your projected superannuation earnings. The calculation for Division 296 includes both realised and unrealised gains, a factor that can create significant liquidity challenges within the super environment. You need a clear plan for how these tax liabilities will be settled without forcing the sale of illiquid assets at an inopportune time. We compare the long-term outcomes of strategic withdrawals against the cost of paying the tax, providing a structured path forward. For those with significant balances, our Division 296 impact modelling provides the technical depth needed to make informed choices.
The Re-contribution Strategy for Couples
Balance creates stability. For couples, one of the most effective building wealth for retirement Australia techniques involves equalising superannuation balances. By strategically withdrawing and re-contributing funds, you can aim to keep both individual balances below the A$3 million threshold, effectively doubling your tax-efficient capacity. This process also allows you to convert taxable components into tax-free components. This is a critical element of wealth preservation strategies, as it directly reduces the tax burden on adult children who may eventually inherit your super. When integrated into broader wealth transfer strategies Australia, re-contribution ensures your family legacy is protected from the 17 per cent tax often applied to the taxable component of inherited funds. It is a methodical way to turn a complex regulation into an opportunity for long-term efficiency.
Securing Longevity through Bespoke Retirement Modelling
Certainty is a choice. While the earlier stages of building wealth for retirement Australia focus on accumulation and tax efficiency, the final pillar is ensuring that wealth translates into a sustainable, lifelong income. We view retirement planning Sydney as a dynamic, evolving process rather than a static event. It requires sophisticated cash flow modelling to replace the anxiety of the unknown with a sense of calm and order. By projecting your financial future across multiple decades, we help you understand exactly how your assets will support your lifestyle, providing the confidence to spend your capital without the fear of outliving your savings.
Longevity risk is a real-world concern. With many Australians now spending 30 years or more in retirement, your strategy must be resilient enough to withstand market fluctuations and inflationary pressures. True North Lifestyle acts as your partner in this journey, providing bespoke projections that go beyond simple spreadsheets. We look at the human outcome of your financial strategy, ensuring your family legacy and personal comfort are perfectly aligned through every stage of your life.
Long-Term Projections vs. Generic Calculators
Static calculators often fail. Most online tools rely on straight-line growth assumptions that ignore "sequence-of-returns" risk, which can be devastating if a market downturn occurs in the early years of your retirement. Our methodology involves stress-testing your portfolio against various economic scenarios to ensure it remains sustainable. We also incorporate complex variables like Centrelink Age Pension entitlements and asset tests. This is critical for those born after 1 January 1957 who face an eligibility age of 67, as even small changes in asset values can impact pension outcomes. This level of detail ensures your roadmap for building wealth for retirement Australia is grounded in evidence rather than optimism.
Achieving Clarity in the Sutherland Shire
Local context matters. Sydney families often have unique lifestyle expectations and property-related wealth that require a tailored approach. Whether you're based in Miranda or the Sydney CBD, our strategies are designed to reflect the reality of your local environment and the costs associated with it. We operate on a fee-for-service basis to ensure our advice remains objective and focussed solely on your outcomes. This transparency is the cornerstone of trust, allowing you to step into retirement with a well-defined path and a reliable anchor in a fluctuating world. If you're ready to move from uncertainty toward a structured plan, book a consultation with our Miranda advisers today to begin your bespoke modelling process.
Charting Your Path toward Financial Longevity
Clarity replaces confusion. We've explored how the 2026 economic landscape demands a shift from accidental accumulation to intentional, research-driven growth. Success in building wealth for retirement Australia now hinges on the seamless synchronisation of your superannuation, bespoke portfolios, and tax structures. By addressing advanced challenges like Division 296 early, you protect your capital from unnecessary leakage and ensure your family legacy remains secure.
You don't have to navigate these complexities alone. True North Lifestyle offers the steady guidance required to turn technical modelling into a stable lifestyle reality. Our team provides specialist Division 296 tax modelling and research-driven bespoke portfolio construction, backed by deep expertise in Miranda and the Sydney CBD. It's time to move beyond generic projections and embrace a plan designed specifically for your "True North."
Achieve clarity with a bespoke wealth strategy from True North Lifestyle and step into your future with quiet certainty. Your retirement should be a period of reward, not worry.
Frequently Asked Questions
What is the best wealth accumulation strategy for Australians in 2026?
The most effective strategy involves synchronising superannuation, bespoke portfolio construction, and tax-minimisation into a single, cohesive roadmap. In 2026, this means moving beyond generic assets toward institutional-grade research and low-volatility investments. By aligning these core engine rooms, you can ensure that building wealth for retirement Australia remains efficient even during periods of persistent inflation. This structured approach replaces the anxiety of guesswork with a logical, research-driven path to financial independence.
How does the new Division 296 tax affect my superannuation strategy?
Division 296 introduces an additional 15 per cent tax on earnings for individuals with total superannuation balances exceeding A$3 million from 1 July 2026. This change fundamentally alters the tax-efficiency of high-value accounts, requiring sophisticated modelling to manage liquidity and potential withdrawals. We help Sydney families identify if they are at risk and implement strategies to mitigate the impact, ensuring your wealth preservation goals aren't compromised by these new legislative thresholds.
Can I still use a re-contribution strategy to reduce my tax bill?
Yes, the re-contribution strategy remains a powerful tool for reducing the taxable component of your superannuation. By withdrawing funds and re-contributing them as non-concessional payments, you convert taxable assets into tax-free components for your heirs. This is a vital part of wealth preservation, as it can significantly lower the 17 per cent tax often applied when adult children inherit super. It is especially useful for couples equalising balances below the A$3 million threshold.
Is an SMSF better than an industry fund for wealth creation?
Neither is universally better; the choice depends on your desire for control versus administrative simplicity. An SMSF offers the ability to hold direct property and provides greater estate planning flexibility, but it carries higher compliance and audit burdens. Conversely, an industry fund offers lower overheads and access to unlisted infrastructure. We provide an objective framework to help you choose the vehicle that best supports your personal journey of building wealth for retirement Australia.
How much do I need to invest to retire comfortably in Sydney?
A comfortable retirement in Sydney is highly subjective and depends on your specific lifestyle expectations in areas like Miranda or the CBD. Generic calculators often fail to account for local cost-of-living pressures or sequence-of-returns risk. We use bespoke retirement modelling to determine your unique number based on detailed cash flow projections. This process ensures your capital is structured to last 30 years or more, providing the certainty you need to maintain your desired standard of living.
What are the most effective tax minimisation strategies for high earners?
High earners can utilise several structures including family trusts, investment bonds, and maximised superannuation contributions. For the 2026/27 financial year, the concessional contribution cap is A$32,500, offering a significant opportunity for pre-tax growth. Combining these with sophisticated estate planning strategies helps reduce tax leakage and protects your family legacy. Our focus is on creating a bespoke tax position that optimises your earnings while remaining fully compliant with the latest Australian Taxation Office regulations.
How does retirement modelling differ from a standard financial plan?
Retirement modelling is a dynamic, cash flow-based process that differs from a static financial plan by stress-testing your assets against various market scenarios. While a standard plan might offer a one-off snapshot, modelling provides a multi-decade projection that accounts for inflation, Centrelink asset tests, and longevity risk. This approach allows you to visualise how your spending impacts your capital over time, replacing financial uncertainty with a clear, well-defined path for your future.
What is the current Superannuation Guarantee rate in 2026?
The Superannuation Guarantee (SG) rate is 12 per cent for the 2026/27 financial year. This rate climbed to its current level on 1 July 2026, representing the final scheduled increase in the current legislative cycle. This higher rate increases the volume of capital entering the superannuation system, making it more important than ever to review your fund's performance and fee structures. Ensuring your super is optimised for this higher contribution level is essential for long-term growth.


