

Could a modest increase in your savings actually leave you worse off every fortnight? A confronting reality. Many retirees in the Sutherland Shire find themselves ensnared in the pension trap, where slight shifts in asset values trigger disproportionate cuts to their essential retirement income. You've worked hard to build your nest egg, yet the complexity of deeming rates and superannuation rules often makes the future feel fragile rather than fixed.
Securing professional Centrelink age pension advice Miranda allows you to replace this lingering anxiety with a sense of order. We believe your retirement should be defined by stability, not by the stress of managing Services Australia's bureaucracy. By applying sophisticated retirement modelling and bespoke asset structuring, we help you maximise your lawful entitlements while ensuring your capital remains resilient against market fluctuations.
Proven strategic outcomes. This article outlines how to align your portfolio with current regulations to achieve long-term clarity. You'll discover how to optimise your income streams, giving you the confidence to enjoy your Miranda lifestyle with the knowledge that your financial foundation is secure and your entitlements are fully realised.
Key Takeaways
- Understand how Sutherland Shire property values influence your homeowner status and your capacity to claim the full pension.
- Access specialised Centrelink age pension advice Miranda to structure your assets lawfully and avoid the common pitfalls of the "pension trap."
- Explore how superannuation optimisation and deeming rate strategies can improve your cash flow without compromising your long-term capital.
- Streamline the application process by mastering the documentation requirements for the Miranda Service Centre and the myGov digital portal.
- Use bespoke retirement modelling to project your income thirty years into the future, ensuring your lifestyle remains sustainable and secure.
Navigating the Centrelink Maze: Why Miranda Retirees Need a Strategy
The Age Pension remains the foundational pillar of the Australian retirement system, providing a reliable income floor for millions of citizens. Understanding the Australian Age Pension history reveals a steady shift from a simple safety net to a highly regulated financial instrument that requires active management. For those living in the Sutherland Shire, high local property values create a unique paradox; you may reside in a high-value asset that is exempt from the assets test, yet find your liquid wealth creates a "pension trap" where even small savings increases lead to sharp payment reductions.
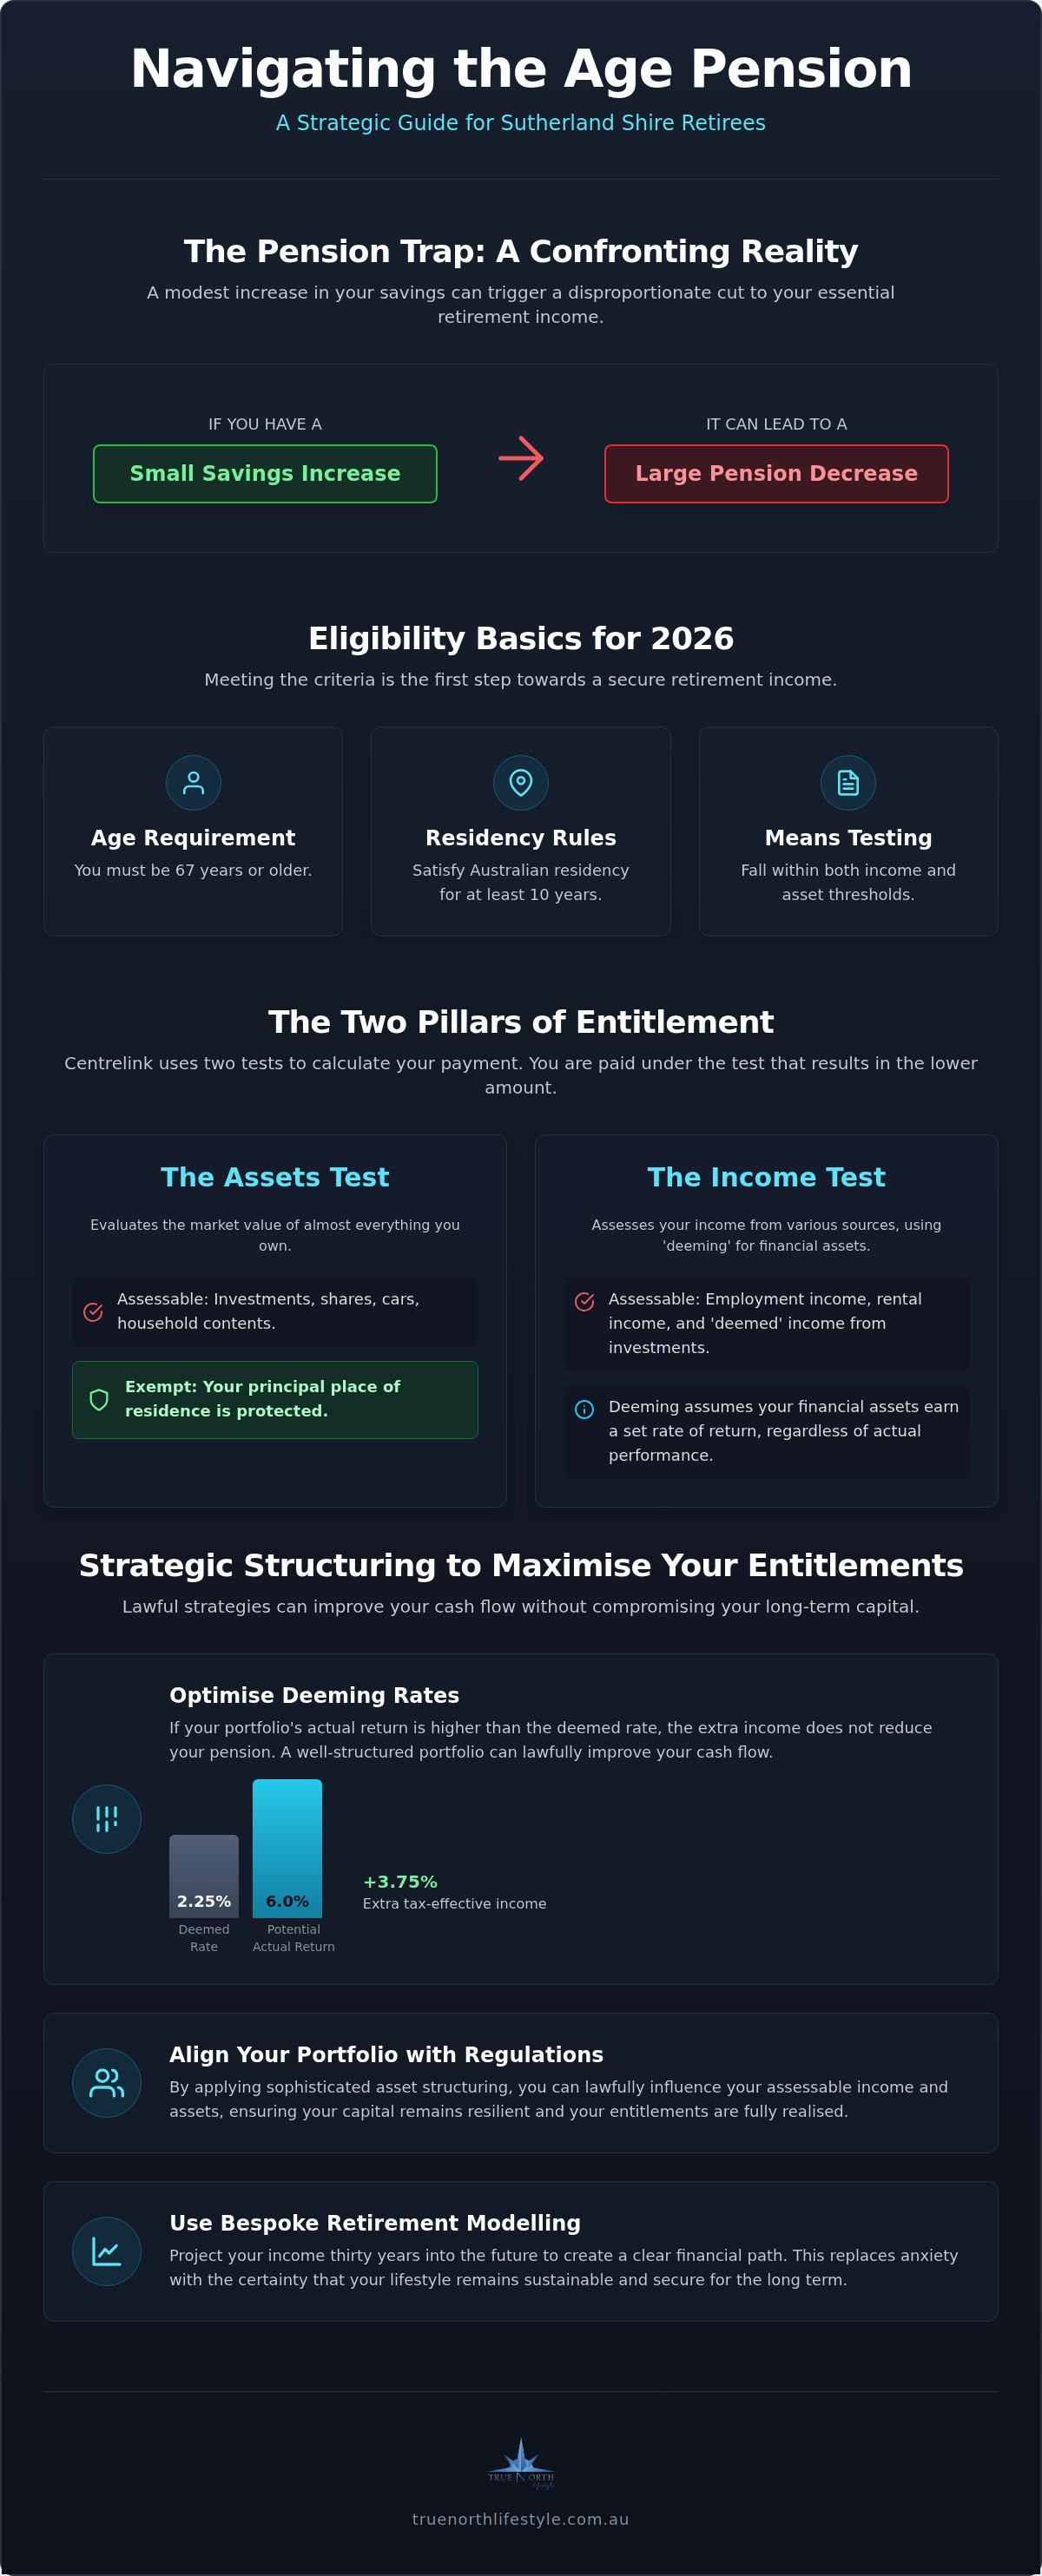
Moving from confusion to a structured financial path requires a "Steady Navigator." Instead of reacting to Centrelink letters with alarm, you can adopt a proactive stance that treats the pension as a strategic component of your total cash flow. To be eligible for the Age Pension in 2026, Miranda residents must typically be aged 67 or older, satisfy Australian residency rules for at least ten years, and fall within the specific income and asset thresholds defined by federal legislation.
The Emotional Weight of Retirement Planning
Retirement should be a period of liberation, yet many feel a heavy sense of anxiety regarding their long-term solvency. Replacing this worry with the quiet certainty of professional retirement modelling is a transformative step. Attempting a "do it yourself" approach with Services Australia often results in missed entitlements or compliance errors that are difficult to rectify. Engaging with local Centrelink age pension advice Miranda ensures you have a professional partner who manages the interface with bureaucracy on your behalf, allowing you to focus on your lifestyle rather than complex paperwork.
In addition to financial clarity, many retirees find value in holistic guidance; SN Consultancy And Support Services provides professional and compassionate consultancy to help individuals and families navigate the broader aspects of life transitions.
Eligibility Basics for the 2026 Financial Year
Legislative frameworks are constantly shifting, and the 2026 financial year brings its own set of updated thresholds and deeming rates. Beyond the basic age requirement of 67, you must carefully time your application to align with your cessation of work and superannuation access. True North Lifestyle simplifies these complex hurdles through rigorous testing of different financial scenarios. We help you understand exactly where you sit within the current regulations, ensuring your transition into the lifestyle phase of your life is seamless and well-supported.
The Two Pillars of Entitlement: Assets and Income Tests Explained
The Age Pension is not a universal entitlement. It is a calculated benefit. Services Australia employs two rigorous filters to determine your payment: the assets test and the income test. To understand the Age Pension eligibility requirements, one must first grasp the "lower of the two" rule. If one test results in a higher payment than the other, Centrelink will always pay the lower amount. This mechanical application of rules often catches retirees off guard, making professional Centrelink age pension advice Miranda a necessity for those who value financial certainty.
Precision in your reporting is paramount. The assets test evaluates the market value of everything you own, from investment properties and shares to your cars and household contents. While your principal place of residence is famously exempt, almost every other financial holding is assessable. A lopsided balance sheet can inadvertently trigger a sharp reduction in your fortnightly income. By utilizing bespoke portfolio construction, we can influence your assessable income levels, ensuring your wealth is structured to work with the system rather than against it.
Deeming Rates and Your Investment Portfolio
Deeming rates are a simplified assumption. Centrelink assumes your financial assets earn a specific rate of return, regardless of their actual performance. While this simplifies their paperwork, it places the burden of performance on you. Securing bespoke investment advice Sydney allows you to build a portfolio that seeks to exceed these rates. If your actual returns are higher than the deemed rate, the extra income does not reduce your pension. It is a lawful way to improve your cash flow through strategic construction, especially when navigating a high-inflation environment.
The Homeowner Advantage in the Sutherland Shire
Your Miranda residence is more than a home; it is a strategic asset. Because the family home is exempt from the assets test, it acts as a primary shield for your wealth. This is particularly relevant in the Sutherland Shire, where property values have remained resilient. However, the pension trap often appears during a downsize. When you unlock equity from your home, that capital transitions from an exempt asset to an assessable one. Managing this transition requires a disciplined approach to ensure your retirement capital lasts as long as you do. A clear path begins with a structured plan. If you are concerned about how your assets are currently viewed by Services Australia, exploring a tailored wealth strategy can help you reclaim a sense of control over your retirement.
Strategic Centrelink Structuring: Maximising Your Lawful Entitlements
Strategic wealth placement. Lawful asset shielding. Many retirees view the pension rules as an immovable wall, yet they're actually a framework for intelligent financial design. One of the most effective methods for couples with an age gap is the "Spouse Strategy." By shifting assessable assets into the superannuation account of a younger spouse who hasn't yet reached pension age, those funds generally remain exempt from the older partner’s assessment. This approach highlights why seeking specialised superannuation advice Sutherland Shire is a cornerstone of effective Centrelink age pension advice Miranda.
Precision matters when managing your balance sheet. Gifting assets to family members is a common desire, but you must stay within the strict limits of $10,000 in a single financial year or $30,000 over a rolling five-year period. Exceeding these figures triggers the "deprived asset" rule under the Centrelink assets test rules, where the value continues to count against you for five years. For those seeking guaranteed income, modern lifetime annuities and income streams offer unique assessment advantages under the 2026 rules, often allowing a portion of the investment to be sheltered from the assets test entirely.
Wealth Preservation through Smarter Structuring
Longevity risk management ensures your structured assets last through your 90s. Effective tax planning for retirement Australia works in tandem with these pension goals. Consider a Miranda couple who recently utilised a "Re-contribution Strategy." By withdrawing superannuation and re-contributing it as non-concessional funds, they lowered their future tax liabilities while simultaneously optimising their position for the pension. This dual-layered approach replaces the anxiety of "running out" with the quiet certainty of a tested financial model.
The Commonwealth Seniors Health Card (CSHC)
The CSHC is often more valuable than the pension itself for self-funded retirees. Even if you don't qualify for a fortnightly payment, the CSHC provides significant relief through PBS discounts and local council rate concessions in Miranda. In 2026, the income test thresholds remain generous, allowing many Shire residents to access these benefits. It's a vital safety net that preserves your lifestyle capital by reducing the everyday costs of healthcare and utilities, ensuring your retirement remains as comfortable as you planned.
The Practical Path: Applying for the Pension in Miranda
Turning strategy into reality. The application process for the Age Pension is often where the most well-constructed plans face their sternest test. To ensure a seamless transition, you must follow a disciplined, step-by-step methodology that leaves no room for administrative error. Your journey begins with gathering precise "Source of Wealth" documentation and current asset valuations. While your Miranda home remains exempt, every other investment must be declared with absolute accuracy to avoid delays or unnecessary payment reductions.
Capturing every dollar. Once your documentation is in order, you can navigate the myGov and Centrelink digital link or choose to visit the Miranda Service Centre in person. A critical, often overlooked step is managing the "Intent to Claim." This simple action locks in your application date, ensuring that any eligible back-payments are captured from the moment you first signal your desire to apply. For retirees with market-linked portfolios, your reporting obligations don't end with the first payment; you must provide regular updates to reflect the fluctuating value of your holdings to maintain your correct entitlement level.
Avoiding the friction. Many Sutherland Shire residents find the bureaucratic interface overwhelming and prone to technical glitches. Seeking professional Centrelink age pension advice Miranda allows you to step into a role of confident oversight while we handle the heavy lifting of the application process, ensuring your data is presented clearly and accurately from the outset.
Common Pitfalls in the Application Process
Failing to update asset values is a frequent error that costs retirees thousands. If you report an old, higher valuation for an investment that has since declined, you're essentially volunteering for a lower pension payment. Similarly, poorly timed financial gifts can trigger "Deprivation of Assets" penalties that last for five years, even if the money was given with the best intentions. True North Lifestyle acts as a stabilising intermediary, vetting your data before it reaches Services Australia to ensure total compliance and maximum entitlement.
Local Resources for Miranda Residents
The Miranda Centrelink office is located at the corner of Kiora Road and Urunga Parade, providing a physical touchpoint for those who prefer face-to-face interaction. However, a local specialist in retirement planning Sydney offers a level of bespoke modelling that a generic government phone line simply cannot match. Before our first consultation in our Miranda office, ensure you have your latest superannuation statements, bank balances, and a list of any significant financial gifts made in the last five years ready for review. This preparation allows us to provide the most accurate Centrelink age pension advice Miranda based on your current financial standing.
Beyond the Pension: Integrating Centrelink into a Bespoke Lifestyle
The transition from the accumulation phase to the lifestyle phase represents a significant psychological shift. For decades, your focus has been on the disciplined growth of your capital; now, the priority moves toward sustainable consumption and wealth preservation. We view the Age Pension not as a standalone benefit, but as a strategic component of a much larger financial architecture. When integrated correctly, it provides a reliable income floor that allows your private investments to be managed with a focus on long-term resilience rather than short-term necessity.
Precision through modelling. Our specialised retirement modelling allows you to project your cash flow 30 years into the future, providing a clear visual representation of how your capital will behave over time. By incorporating professional Centrelink age pension advice Miranda into these projections, we can identify the "sweet spot" where your private withdrawals and government entitlements align perfectly. This research-driven approach establishes a sustainable withdrawal rate, giving you the quiet certainty that your retirement lifestyle in the Sutherland Shire is protected against inflationary pressures and market volatility.
Strategic legacy planning. Your retirement strategy should also consider the eventual transition of your assets to the next generation. Understanding how the pension interacts with wealth transfer strategies is essential for Miranda families who wish to balance their own income needs with a desire to provide for their children. We help you structure your affairs so that your entitlement remains optimised today without compromising your long-term estate planning objectives.
Longevity and Legacy: A Balanced Approach
Structuring your estate requires a delicate touch to ensure the pension doesn't inadvertently compromise your inheritance goals. For many families in Miranda, the use of testamentary trusts provides a robust layer of protection, keeping wealth within the family line while offering significant tax advantages for beneficiaries. It's a reminder that while the pension is a valuable tool for cash flow, your personal lifestyle and the legacy you leave behind are the true destinations. We ensure these elements work in harmony, replacing complexity with a well-defined, structured path.
Your Next Steps with True North Lifestyle
Our in-house Investment Committee performs rigorous stress-testing on every plan, modelling how your portfolio would have performed during historical periods of market instability. This disciplined methodology ensures that the Centrelink age pension advice Miranda we provide is grounded in real-world probability. We invite you to experience this level of clarity firsthand through a bespoke retirement modelling session. You can take the first step toward a more secure and empowered retirement by booking a strategy consultation with our Miranda team at our local office or our Sydney CBD location.
Securing Your Future with Quiet Certainty
Your retirement should be defined by the quality of your lifestyle, not the complexity of your paperwork. We've explored how strategic asset placement and a deep understanding of the means tests can transform your financial outlook. By moving beyond a reactive stance, you can turn the pension into a reliable foundation for your broader wealth goals. Local expertise matters. Accessing tailored Centrelink age pension advice Miranda ensures that your specific circumstances in the Sutherland Shire are accounted for in every projection.
True North Lifestyle provides the structure you need to move forward with confidence. Our research-driven investment committee and comprehensive retirement modelling ensure your plan is resilient against market shifts. We invite you to book your bespoke retirement modelling session in Miranda to see exactly how your capital can work for you over the next thirty years. You've worked hard to build your legacy; now, it's time to enjoy the stability you deserve. Your path to a structured and empowered retirement starts here.
Frequently Asked Questions
Is the family home included in the Centrelink Assets Test?
No, your principal place of residence is generally an exempt asset. This exemption applies regardless of the home's value, which is particularly significant for those seeking Centrelink age pension advice Miranda given local property prices. However, if the land exceeds two hectares, the additional area may be assessable under the assets test. It's a foundational rule that provides stability for many homeowners in the Sutherland Shire.
Can I still get the Age Pension if I have a large superannuation balance?
Yes, you may still qualify for a part pension if your total assessable assets fall below the current upper thresholds. Your superannuation is counted as an asset once you reach Age Pension age, and the income it generates is assessed via deeming. We use retirement modelling to determine exactly how your specific balance influences your fortnightly payment, ensuring you don't miss out on lawful entitlements.
How much can I gift to my children without affecting my pension?
You can gift up to A$10,000 in a single financial year without triggering immediate payment reductions. Additionally, the total amount gifted cannot exceed A$30,000 over a rolling five-year period. Any amount above these limits is treated as a "deprived asset" and continues to be counted in your assets test for five years from the date of the gift. This rule prevents retirees from quickly reducing their assets to claim a higher pension.
What are the current deeming rates for the 2026 financial year?
Deeming rates are set by the Australian Government and are applied to your financial investments to calculate assessable income. While specific 2026 rates depend on upcoming legislative reviews, they typically involve a lower tier for initial assets and a higher tier for balances above a certain threshold. It's vital to monitor these changes, as they directly impact your income test results and your total fortnightly cash flow.
How does a "Transition to Retirement" strategy affect my Centrelink status?
A Transition to Retirement (TTR) income stream is generally considered an assessable asset and the payments are counted under the income test. While you're under Age Pension age, funds held in a superannuation accumulation account are usually exempt. Once you reach 67, the entire balance becomes assessable, making the timing of your TTR strategy a critical factor in your overall plan. We help you navigate this shift to ensure your income remains stable.
What happens to my pension if I decide to downsize my Miranda home?
When you downsize your Miranda home, the surplus funds from the sale transition from an exempt asset to an assessable one. This change often reduces your pension payment or may disqualify you entirely. There are specific rules that allow you to exempt the sale proceeds for a limited period if you intend to purchase another principal residence. Managing this transition requires a disciplined approach to protect your long-term income.
Can a financial adviser lodge my Centrelink application for me?
Yes, a financial adviser can be appointed as your "Correspondence Nominee" to manage your dealings with Services Australia. This allows us to lodge applications and update your asset values on your behalf. Providing Centrelink age pension advice Miranda includes reducing your administrative burden, ensuring your paperwork is accurate and your entitlements are processed without unnecessary friction. It replaces the anxiety of bureaucracy with professional oversight.
Is there a difference between the Age Pension and the Commonwealth Seniors Health Card?
Yes, the Age Pension provides a fortnightly cash payment, whereas the Commonwealth Seniors Health Card (CSHC) offers concessions on healthcare and utilities. The CSHC has a much higher income threshold and no assets test, making it a valuable alternative for self-funded retirees. Many residents in the Sutherland Shire who don't qualify for the pension still benefit significantly from the CSHC, preserving their lifestyle capital as they age.


